
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aircraft Manufacturing Market Size 2024 | USD 427.66 million |
| Aircraft Manufacturing Market, CAGR | 3.67% |
| Aircraft Manufacturing Market Size 2032 | USD 587.08 million |
Market Overview:
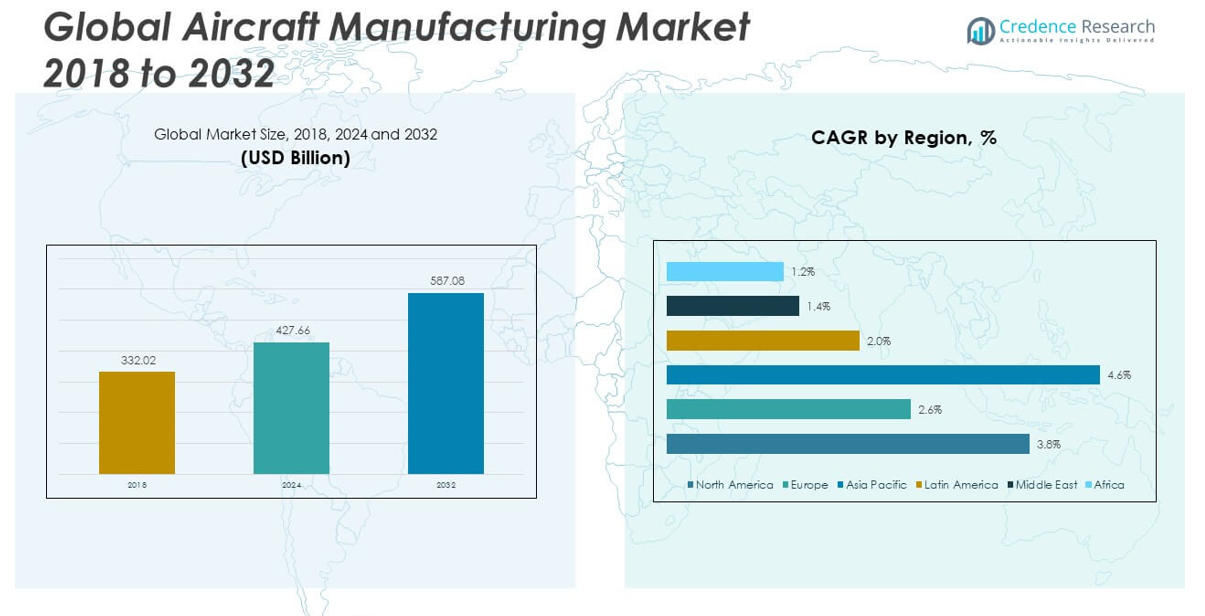
The Global Aircraft Manufacturing Market size was valued at USD 332.02 million in 2018 to USD 427.66 million in 2024 and is anticipated to reach USD 587.08 million by 2032, at a CAGR of 3.76% during the forecast period.
The aircraft manufacturing market is driven by a combination of rising global air passenger traffic, advancements in aerospace technologies, and increasing demand for fuel-efficient and environmentally friendly aircraft. As international tourism rebounds and middle-class populations expand, particularly in emerging economies, airlines are upgrading and expanding their fleets to meet growing demand. Simultaneously, aerospace manufacturers are focusing on the development of next-generation aircraft that offer reduced emissions, lower fuel consumption, and improved safety. Innovations such as hybrid-electric propulsion, sustainable aviation fuels (SAF), and lightweight composite materials are gaining momentum due to regulatory pressures and airline sustainability goals. Moreover, the defense sector plays a significant role, with rising geopolitical tensions pushing nations to invest in advanced military aircraft. Heightened defense budgets in countries like the U.S., China, and India are driving demand for fighter jets, surveillance aircraft, and unmanned aerial vehicles (UAVs), adding to the overall growth trajectory of the global aircraft manufacturing industry.
North America dominates the global aircraft manufacturing market owing to the presence of key industry players like Boeing, Lockheed Martin, and Northrop Grumman. The region benefits from strong military expenditure, robust defense aerospace contracts, and a mature commercial aviation sector. Europe remains a significant contributor, led by Airbus and a network of sophisticated aerospace suppliers. The region focuses on sustainable aviation solutions and benefits from cohesive regulatory frameworks that encourage innovation. Meanwhile, the Asia-Pacific region is experiencing the fastest growth, with China and India investing heavily in commercial aviation and defense capabilities. China’s COMAC is emerging as a competitive player, while India’s aerospace manufacturing ecosystem is gaining global attention. The Middle East, with airlines like Emirates and Qatar Airways, is a strategic hub for wide-body aircraft. Latin America and Africa are smaller markets but show potential for growth due to expanding regional connectivity and infrastructure development.
Market Insights:
- The Global Aircraft Manufacturing Market reached USD 427.66 million in 2024 and is projected to hit USD 587.08 million by 2032, growing at a CAGR of 3.76% during the forecast period.
- Surging demand for commercial air travel is driving fleet expansion and replacement, especially among low-cost carriers and operators in emerging markets.
- Technological progress in hybrid-electric propulsion, digital avionics, and composite materials is enabling more efficient, lighter, and eco-friendly aircraft designs.
- Military modernization programs in the U.S., China, and India are fueling orders for fighter jets, UAVs, and surveillance platforms, strengthening defense segment growth.
- Regulatory pressure for carbon-neutral aviation is pushing manufacturers to accelerate development of sustainable aircraft powered by SAF and electric systems.
- Persistent supply chain constraints, including delays in critical components and materials, continue to impact production schedules and delivery targets.
- North America holds the largest market share due to strong defense spending and the presence of Boeing and Lockheed Martin, while Asia Pacific leads in growth rate, driven by rising demand in China and India.
Market Drivers:
Rising Demand for Commercial Air Travel is Driving Aircraft Procurement
The rapid growth in global air passenger traffic continues to fuel demand for new commercial aircraft. Airlines across both developed and developing economies are expanding their fleets to serve increasing passenger volumes and open new routes. The Global Aircraft Manufacturing Market is responding with increased production of fuel-efficient single-aisle and wide-body aircraft. Major carriers are also retiring older, less efficient planes, accelerating fleet modernization. Growing middle-class populations and improved connectivity in regions such as Asia-Pacific and Africa are further stimulating demand. Low-cost carriers are intensifying fleet acquisition to maintain competitive pricing and expand service networks. It supports sustained growth in aircraft deliveries across commercial segments.
- For example, Airbus’ A350-900, constructed with 70% advanced materials such as carbon fiber, achieves a fuel efficiency of 2.39 liters per 100 passenger-kilometers, while Boeing’s 787-9 achieves 2.31 L/100km per passenger both representing industry-leading metrics for wide-body aircraft.4
Technological Advancements are Reshaping Aircraft Design and Efficiency
Technological innovation remains central to competitiveness in the aerospace industry. Manufacturers are focusing on lightweight materials, advanced avionics, and digital twin technologies to reduce weight and improve efficiency. It enables better fuel economy, lower emissions, and enhanced passenger comfort. The Global Aircraft Manufacturing Market is witnessing the rise of hybrid-electric propulsion systems, which promise to reduce dependency on fossil fuels. These developments align with stringent emission regulations and the aviation industry's carbon-neutral goals. The use of artificial intelligence and predictive analytics in aircraft systems enhances operational safety and maintenance. These technologies are shaping the next generation of commercial and defense aircraft.
Military Modernization and Defense Procurement are Boosting Market Growth
Heightened geopolitical tensions and defense modernization programs are increasing demand for next-generation military aircraft. Countries such as the United States, China, India, and members of NATO are upgrading air fleets to maintain strategic capabilities. The Global Aircraft Manufacturing Market benefits from sustained defense budgets directed toward fighter jets, transport aircraft, surveillance platforms, and unmanned systems. Governments are emphasizing technological superiority, speed, and interoperability, leading to investments in fifth- and sixth-generation aircraft. It strengthens the market’s military segment and supports long-term contract-based revenue models. Defense suppliers are also expanding production capacity to fulfill multi-year procurement pipelines.
- For example, The U.S. Air Force’s FY2025 budget allocates $5.9 billion for 42 F-35As and $3.1 billion for 15 Boeing KC-46 tankers, with a long-term program of record aiming for over 1,700 F-35s in total procurement.
Sustainability Pressures are Accelerating Green Aircraft Development
Environmental regulations and industry sustainability commitments are compelling aircraft manufacturers to reimagine product design. The market is shifting toward models that minimize fuel burn and meet international emission standards. The Global Aircraft Manufacturing Market is incorporating alternative fuels, electric propulsion, and recyclable materials into aircraft development. These initiatives align with targets set by aviation authorities and climate policy frameworks. Manufacturers are investing in research and development to meet customer expectations for lower operational costs and reduced environmental impact. It is creating opportunities for new entrants and reshaping the competitive landscape. Sustainability has become a critical factor in long-term product strategy.
Market Trends:
Strategic Collaborations and Joint Ventures Are Redefining Aerospace Partnerships
Aircraft manufacturers are forming strategic alliances with technology firms, suppliers, and governments to enhance capabilities and expand market reach. These collaborations focus on sharing risk, reducing costs, and accelerating access to advanced technologies. The Global Aircraft Manufacturing Market is seeing increased joint ventures between Western OEMs and suppliers in Asia and the Middle East. Companies are leveraging partnerships to localize production, improve aftermarket services, and strengthen supply chain resilience. Governments are supporting such alliances through investment incentives and defense offsets. It helps firms adapt to regional regulations while securing long-term contracts. These partnerships are shaping global competitiveness and influencing procurement decisions.
- For example, Collins Aerospace operates multiple joint ventures in China, such as the AVIC Leihua Rockwell Collins Avionics Company (ALRAC), which provides system engineering, software development, and MRO services for the COMAC C919 program.
Urban Air Mobility and eVTOL Development Are Gaining Industry Support
The push toward urban air mobility is opening a new frontier in aerospace innovation. Companies are investing in electric vertical takeoff and landing (eVTOL) aircraft to address congestion and reduce urban travel times. The Global Aircraft Manufacturing Market is responding by allocating resources toward design, testing, and certification of these next-generation platforms. Regulatory bodies and urban planners are exploring frameworks to integrate these vehicles into city infrastructure. Startups and established players are competing to launch air taxi services in the next few years. It is generating investor interest and reshaping long-term planning within traditional aircraft portfolios. Urban air mobility represents a high-growth niche in early stages of adoption.
- For example, companies such as Hyundai’s Supernal, Embraer’s Eve Air Mobility, and Joby Aviation are investing heavily in R&D, with Eve Air Mobility securing a $250 million contractand an additional $94 million in new equity to support eVTOL development.
Expansion of Digital Manufacturing Is Transforming Production Processes
Digital transformation is playing a critical role in aircraft production and assembly. Manufacturers are adopting Industry 4.0 tools such as additive manufacturing, automation, and digital twins to optimize efficiency and reduce errors. The Global Aircraft Manufacturing Market is leveraging smart factories to monitor real-time performance, improve precision, and shorten time-to-market. Integration of cloud-based systems enables better coordination across global supply chains. It also facilitates faster prototyping and enhances customization capabilities. These trends are redefining how aircraft components are designed, tested, and produced. The shift toward digital ecosystems is becoming central to competitive advantage in aerospace.
Rising Demand for Aircraft Leasing Is Influencing Production Strategies
Aircraft leasing is growing as a preferred model for airlines seeking fleet flexibility and lower capital expenditure. Leasing firms now influence a significant portion of global aircraft orders, especially for narrow-body and regional jets. The Global Aircraft Manufacturing Market is adapting by aligning delivery schedules and production volumes with lessor demand patterns. Leasing companies often prioritize standardized configurations that allow faster redeployment across airline clients. It changes how OEMs approach interior customization, financing structures, and after-sales services. The growth of aircraft leasing is shaping how manufacturers structure contracts and manage global inventories. This trend supports aircraft accessibility across emerging markets.
Market Challenges Analysis:
Supply Chain Disruptions and Raw Material Constraints Are Slowing Production
Aircraft manufacturers continue to face persistent challenges related to supply chain disruptions and material shortages. Global events, geopolitical tensions, and logistical bottlenecks have restricted the availability of critical components such as semiconductors, engines, and specialized alloys. The Global Aircraft Manufacturing Market struggles to maintain consistent production timelines due to delays from suppliers and unpredictable lead times. It affects the delivery of new aircraft and slows down assembly lines, especially for high-demand commercial models. Manufacturers are being forced to reassess sourcing strategies and increase inventory buffers, which raises operational costs. Supply chain instability remains a critical obstacle to achieving production targets and scaling output efficiently.
Regulatory Complexities and Certification Delays Are Hindering Innovation
Compliance with global aviation safety regulations remains a demanding and time-consuming process for aircraft manufacturers. New aircraft programs often experience significant delays due to evolving certification requirements and intensified scrutiny from regulatory bodies. The Global Aircraft Manufacturing Market must navigate varying regional standards, which complicates global rollouts and slows time-to-market. It limits the pace of technological adoption, especially for innovations in propulsion systems, autonomous navigation, and alternative fuels. Meeting stringent safety benchmarks without compromising innovation continues to be a delicate balance for OEMs. Delays in approval processes can disrupt launch timelines and erode competitive advantage in a fast-evolving market.
Market Opportunities:
Emerging Markets and Regional Connectivity Programs Offer Long-Term Growth
Developing countries are investing in aviation infrastructure to boost connectivity and economic growth. Governments across Asia, Africa, and Latin America are expanding airports, launching regional airlines, and implementing aviation-friendly policies. The Global Aircraft Manufacturing Market can benefit from this shift by supplying smaller jets and turboprops tailored to regional routes. It creates demand for aircraft with lower operating costs and shorter range capabilities. Domestic air travel is rising in underserved areas, supported by tourism, trade, and growing middle-class populations. These trends position regional aviation as a strong opportunity for sustained aircraft deliveries.
Demand for Sustainable Aviation and Next-Generation Technologies Is Accelerating
Airlines and regulators are prioritizing sustainability, prompting interest in aircraft powered by hydrogen, electricity, or hybrid systems. This transition creates space for new programs focused on cleaner propulsion, advanced aerodynamics, and eco-efficient materials. The Global Aircraft Manufacturing Market can leverage this momentum to develop aircraft that align with global emissions targets. It opens doors for R&D partnerships, government-backed innovation, and early-mover advantage in emerging green segments. Customers are seeking environmentally responsible fleets, creating room for differentiation and premium pricing. Sustainability-focused aircraft platforms are expected to attract long-term investment and market share.
Market Segmentation Analysis:
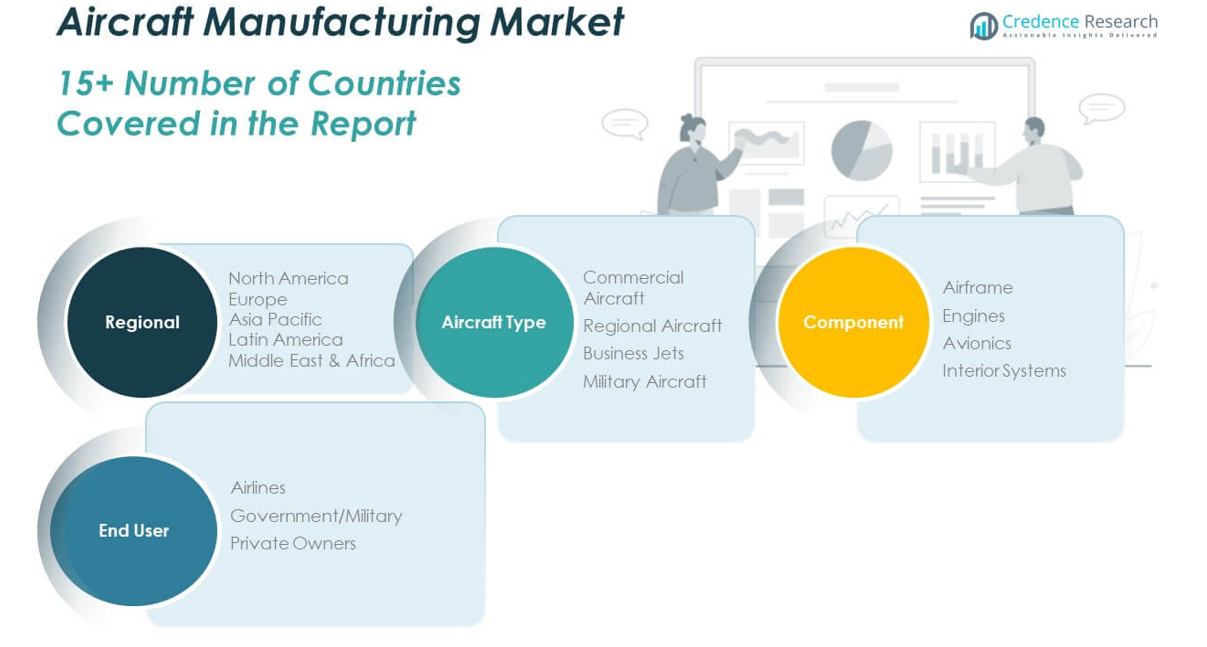
The Global Aircraft Manufacturing Market is segmented by aircraft type, component, and end user, each contributing uniquely to its growth dynamics.
By aircraft type, commercial aircraft dominate the market due to strong demand from global airlines and continued expansion of passenger traffic. Regional aircraft follow, supported by rising connectivity in emerging economies and short-haul travel growth. Business jets serve high-net-worth individuals and corporate fleets, with steady demand from the private aviation sector. Military aircraft represent a significant share, driven by defense modernization programs and national security initiatives.
- For example, Aircraft Embraer projects demand for 10,500 new regional aircraft (jets and turboprops with fewer than 150 seats) by 2045, driven by connectivity needs in developing regions and fleet renewal in mature markets.
By component, airframes account for a substantial portion of market revenue, reflecting the complexity and cost of structural manufacturing. Engines form another major segment, fueled by demand for fuel-efficient propulsion technologies. Avionics systems are gaining traction due to the need for advanced navigation, communication, and automation tools. Interior systems are evolving to enhance passenger comfort and meet airline customization needs.
By end user, airlines lead the market with continuous investments in new fleets and replacement aircraft. The government/military segment contributes robust demand, particularly for fighter jets, transport aircraft, and UAVs. Private owners, though smaller in share, drive demand in the luxury and business jet categories. The Global Aircraft Manufacturing Market serves diverse needs through these integrated segments, shaping long-term growth across both civil and defense sectors.
- For example, global military aircraft fleet stood at over 45,400 active aircraft as of January 2025, with growth driven by new deliveries such as the F-35.
Segmentation:
By Aircraft Type:
- Commercial Aircraft
- Regional Aircraft
- Business Jets
- Military Aircraft
By Component:
- Airframe
- Engines
- Avionics
- Interior Systems
By End User:
- Airlines
- Government/Military
- Private Owners
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North America Aircraft Manufacturing Market size was valued at USD 99.13 billion in 2018 to USD 125.74 billion in 2024 and is anticipated to reach USD 173.32 billion by 2032, at a CAGR of 3.8% during the forecast period. North America holds the largest share of the Global Aircraft Manufacturing Market, accounting for nearly 26%. The region benefits from a well-established aerospace ecosystem, led by major OEMs such as Boeing, Lockheed Martin, and Northrop Grumman. It is supported by significant defense spending, a high volume of commercial aircraft deliveries, and a mature MRO infrastructure. The U.S. government’s long-term defense contracts and space exploration initiatives continue to sustain demand. Canada also plays a strategic role, particularly in regional jet production and avionics. The North American market continues to emphasize innovation, automation, and next-generation military platforms.
The Europe Aircraft Manufacturing Market size was valued at USD 63.86 billion in 2018 to USD 77.88 billion in 2024 and is anticipated to reach USD 97.52 billion by 2032, at a CAGR of 2.6% during the forecast period. Europe accounts for 16% of the Global Aircraft Manufacturing Market, with Airbus driving the region’s commercial aircraft leadership. Strong government backing, a coordinated regulatory environment, and sustainability mandates shape production strategies. It supports a balanced mix of commercial, defense, and space programs across countries like France, Germany, and the U.K. European manufacturers focus on low-emission technologies and lightweight materials. Strategic programs such as the Future Combat Air System (FCAS) also contribute to long-term demand. The region remains a center of research and development for green aviation technologies.
The Asia Pacific Aircraft Manufacturing Market size was valued at USD 139.86 billion in 2018 to USD 187.05 billion in 2024 and is anticipated to reach USD 272.99 billion by 2032, at a CAGR of 4.6% during the forecast period. Asia Pacific holds the largest share of the Global Aircraft Manufacturing Market at 39%, driven by rapid expansion in commercial aviation. China and India lead demand due to growing middle-class populations, new airline launches, and infrastructure investments. It benefits from increasing government support for indigenous aircraft programs such as COMAC’s C919 and HAL’s Tejas. The region attracts global OEMs seeking to diversify their supply chains. Southeast Asia is also emerging as a critical aviation hub with high passenger growth. The market is poised for sustained momentum across both civil and defense segments.
The Latin America Aircraft Manufacturing Market size was valued at USD 14.44 billion in 2018 to USD 18.35 billion in 2024 and is anticipated to reach USD 22.05 billion by 2032, at a CAGR of 2.0% during the forecast period. Latin America contributes 4% to the Global Aircraft Manufacturing Market, with Brazil leading through Embraer’s strength in regional and executive jets. The market reflects modest growth but stable demand from domestic and regional carriers. It is supported by fleet replacement programs and increased connectivity in underserved areas. Governments are investing in airport modernization and airspace reforms. Embraer’s defense exports and innovation in electric aircraft technologies add momentum. The region shows potential for greater integration into global aerospace supply chains.
The Middle East Aircraft Manufacturing Market size was valued at USD 8.75 billion in 2018 to USD 10.24 billion in 2024 and is anticipated to reach USD 11.70 billion by 2032, at a CAGR of 1.4% during the forecast period. The Middle East holds a 2% share in the Global Aircraft Manufacturing Market, heavily influenced by commercial aviation demand. The region hosts some of the world’s largest wide-body aircraft operators such as Emirates, Qatar Airways, and Etihad. It supports demand for new aircraft and advanced MRO capabilities. Governments are diversifying into domestic manufacturing and aerospace R&D through joint ventures. It faces limited defense production but shows long-term potential through localization strategies. The regional focus remains on expanding commercial capacity and reducing reliance on imports.
The Africa Aircraft Manufacturing Market size was valued at USD 5.99 billion in 2018 to USD 8.40 billion in 2024 and is anticipated to reach USD 9.49 billion by 2032, at a CAGR of 1.2% during the forecast period. Africa contributes nearly 2% to the Global Aircraft Manufacturing Market, with gradual growth in regional aviation. Rising demand for intra-continental air travel and infrastructure development supports market activity. It remains dependent on imports for both commercial and military aircraft. Local manufacturing is limited but gaining attention through public-private partnerships. South Africa leads regional efforts in defense and aerospace engineering. It offers long-term opportunity through investments in connectivity, fleet modernization, and aviation training programs.
Key Player Analysis:
- Airbus
- Boeing
- Embraer
- COMAC
- Bombardier
- Lockheed Martin
- Northrop Grumman
- Dassault Aviation
- Gulfstream Aerospace
- Textron Aviation
Competitive Analysis:
The Global Aircraft Manufacturing Market remains highly competitive, led by major players such as Boeing, Airbus, Lockheed Martin, Northrop Grumman, Embraer, and COMAC. These companies dominate both commercial and defense segments through strong order books, advanced technologies, and global supply chains. The market also includes niche players and regional manufacturers that specialize in light aircraft and UAVs. It requires significant capital investment, regulatory compliance, and innovation to maintain market position. OEMs compete on delivery timelines, fuel efficiency, avionics integration, and customer support services. Strategic collaborations, long-term defense contracts, and sustainability-driven product development play key roles in securing growth. The Global Aircraft Manufacturing Market sees intense rivalry in single-aisle commercial aircraft, while military aircraft programs drive competition through government-backed procurement.
Recent Developments:
- In July 2025, Qantas took delivery of its first Airbus A321XLR, making it the Asia-Pacific launch operator for this latest-generation single-aisle aircraft. The delivery took place at Airbus’s Hamburg facility on June 30, 2025.
- In June 2025, JetZeroannounced a $4.7 billion investment to build a new aircraft factory in Greensboro, North Carolina, dedicated to producing its innovative blended-wing-body jets. The factory is expected to create over 14,500 jobs and will support the development of the Z4 passenger plane, which promises up to 50% better fuel efficiency compared to traditional designs.
- In April 2025, XTI Aerospaceannounced significant product and engineering milestones for the second quarter, focusing on the continued development of its flagship xVTOL aircraft, the TriFan 600. The company is advancing toward the first flight of its next subscale model, code-named "Sparrow," and plans to finalize its engine supplier selection, particularly for twin turboshaft engines. XTI also intends to reopen pre-sales for the TriFan 600 later in the year, targeting fleet operators and other prospective customers.
- In April 2025, Airbus SEentered into a definitive agreement to acquire several industrial assets from Spirit AeroSystems dedicated to Airbus’s commercial aircraft programs. The acquisition includes facilities and production lines in the United States, France, Morocco, Northern Ireland, and Scotland, covering key components for the A350, A321, and A220 aircraft.
Market Concentration & Characteristics:
The Global Aircraft Manufacturing Market shows a high level of concentration, with a few major players accounting for a significant share of total production and revenue. Boeing and Airbus dominate the commercial segment, while Lockheed Martin and Northrop Grumman lead in defense aircraft. It is capital-intensive, technology-driven, and highly regulated, requiring long development cycles and strong government relationships. Barriers to entry remain high due to certification complexity, supply chain demands, and the need for advanced engineering capabilities. The market favors firms with global manufacturing footprints, strategic alliances, and integrated service offerings. It is characterized by cyclical demand patterns influenced by airline profitability, defense budgets, and geopolitical stability.
Report Coverage:
The research report offers an in-depth analysis based on aircraft type, component, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for fuel-efficient and low-emission aircraft will drive long-term innovation and fleet replacement.
- Expansion of regional connectivity in emerging markets will create new opportunities for smaller aircraft models.
- Investment in hybrid-electric and hydrogen propulsion systems will reshape aircraft development strategies.
- Increased defense spending will support sustained demand for next-generation military aircraft and UAVs.
- Growth of aircraft leasing will influence production planning and standardization of cabin configurations.
- Digital manufacturing and automation will improve efficiency, reduce costs, and enhance customization.
- Strategic collaborations between OEMs and technology firms will accelerate development of advanced systems.
- Urban air mobility and eVTOL adoption will create a new segment within the aerospace industry.
- Supply chain diversification will reduce regional risks and strengthen global production resilience.
- Sustainability regulations will drive R&D funding and shift focus toward environmentally responsible platforms.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Fleet Expansion Driven by Commercial Air Travel Growth
The surge in global air passenger traffic, especially in emerging markets, is prompting airlines to expand and modernize their fleets, driving demand for new, fuel-efficient commercial and regional aircraft.
Technological Advancements in Aircraft Design
Innovations such as hybrid-electric propulsion, advanced avionics, and lightweight composite materials are enabling manufacturers to produce more efficient, eco-friendly, and cost-effective aircraft, meeting both regulatory and airline requirements.
Military Modernization and Defense Procurement
Rising geopolitical tensions and increased defense budgets in countries like the U.S., China, and India are fueling demand for next-generation military aircraft, including fighter jets, UAVs, and surveillance platforms.
Sustainability and Regulatory Pressure
Stringent environmental regulations and industry commitments to carbon-neutral aviation are accelerating the development and adoption of aircraft powered by sustainable aviation fuels, electric systems, and recyclable materials.
Growth of Aircraft Leasing and Flexible Fleet Models
The increasing preference for aircraft leasing among airlines is influencing production strategies, as manufacturers align delivery schedules and configurations to meet the needs of lessors and support rapid fleet redeployment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Aircraft Manufacturing Market?
What are the key segments within the Global Aircraft Manufacturing Market?
What are some challenges faced by the Global Aircraft Manufacturing Market?
Who are the major players in the Global Aircraft Manufacturing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Airlines
- 1.2.2 Government/Military
- 1.2.3 Private Owners
- 1.3 By Component
- 1.3.1 Airframe
- 1.3.2 Engines
- 1.3.3 Avionics
- 1.3.4 Interior Systems
- 1.4 By Aircraft Type
- 1.4.1 Commercial Aircraft
- 1.4.2 Regional Aircraft
- 1.4.3 Business Jets
- 1.4.4 Military Aircraft
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 427.66 million → 2032: USD 587.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aircraft Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aircraft Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aircraft Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aircraft Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aircraft Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aircraft Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aircraft Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aircraft Manufacturing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 427.66 million → 2032: USD 587.08 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aircraft Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Airlines
- 12.3.7.2 Government/Military
- 12.3.7.3 Private Owners
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Airframe
- 12.4.7.2 Engines
- 12.4.7.3 Avionics
- 12.4.7.4 Interior Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Aircraft Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Commercial Aircraft
- 12.5.7.2 Regional Aircraft
- 12.5.7.3 Business Jets
- 12.5.7.4 Military Aircraft
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aircraft Manufacturing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aircraft Manufacturing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aircraft Manufacturing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aircraft Manufacturing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Airbus
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Boeing
- 18.4 Embraer
- 18.5 COMAC
- 18.6 Bombardier
- 18.7 Lockheed Martin
- 18.8 Northrop Grumman
- 18.9 Dassault Aviation
- 18.10 Gulfstream Aerospace
- 18.11 Textron Aviation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

