
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aircraft Tires Market Size 2024 | USD 2,268.6 million |
| Aircraft Tires Market, CAGR | 4.71% |
| Aircraft Tires Market Size 2032 | USD 3,263.2 million |
Market Overview
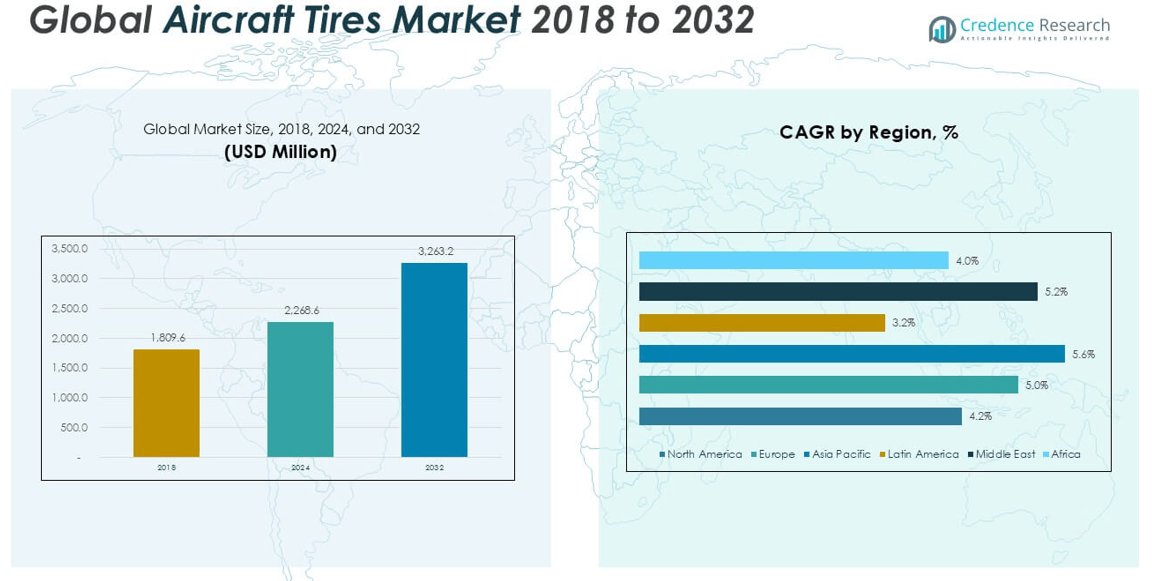
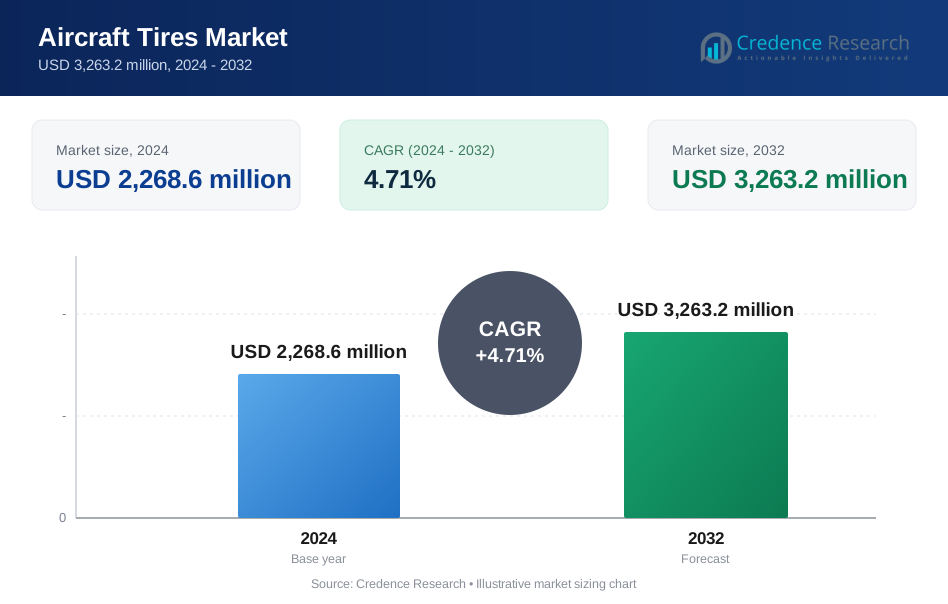
The Global Aircraft Tires Market is projected to grow from USD 2,268.6 million in 2024 to an estimated USD 3,263.2 million by 2032, with a compound annual growth rate (CAGR) of 4.71% from 2025 to 2032.
Key market drivers include the steady rise in global passenger air traffic, fleet modernization programs, and increasing investments in aircraft maintenance, repair, and overhaul (MRO) services. Trends such as the shift towards fuel-efficient and lightweight aircraft are pushing manufacturers to develop durable, high-performance tires using advanced materials like carbon composites and aramid fibers. Additionally, the growing demand for next-generation aircraft, coupled with stricter aviation safety standards, is prompting airlines to prioritize high-quality tire solutions.
Geographically, North America leads the global market due to the presence of major aircraft manufacturers and established MRO infrastructure. Europe and Asia Pacific follow closely, with Asia Pacific expected to witness the fastest growth owing to expanding aviation sectors in countries like China and India. Key players operating in the global aircraft tires market include Michelin, Goodyear Tire & Rubber Company, Bridgestone Corporation, Dunlop Aircraft Tyres Ltd., and Continental AG, all focusing on innovation, strategic collaborations, and expanding their global footprint to strengthen market position.
Market Insights
- The market is projected to grow from USD 2,268.6 million in 2024 to USD 3,263.2 million by 2032, with a CAGR of 4.71% driven by expanding airline fleets and rising air travel demand.
- Increasing commercial and military aircraft production, coupled with frequent tire replacements, fuels steady market growth worldwide.
- Advancements in tire materials and design, including the use of carbon composites and aramid fibers, enhance performance and durability.
- High costs of raw materials and complex regulatory certification processes remain key challenges limiting rapid market expansion.
- North America dominates the market due to its strong aviation infrastructure, while Asia Pacific is the fastest-growing region thanks to rising air traffic and fleet modernization.
- Strict aviation safety standards drive continuous demand for high-quality tires and support growth in the maintenance, repair, and overhaul (MRO) segment.
- Competitive strategies focus on innovation, partnerships with aircraft manufacturers, and expansion in emerging markets to capture increased demand.
Market Drivers
Expansion of Global Air Travel and Commercial Fleet Size
The Global Aircraft Tires Market is benefiting from the steady rise in global air traffic. Airlines are expanding their commercial fleets to meet growing demand for both domestic and international travel. Governments and private carriers are investing in new aircraft to support tourism and business travel. The increasing number of takeoffs and landings places greater demand on aircraft tires, which require regular replacement. Frequent short-haul flights, in particular, accelerate tire wear and drive replacement cycles. This trend is directly supporting consistent market growth.
- For instance, the global commercial aircraft fleet reached approximately 31,000 aircraft in 2024, with projections to expand to over 41,100 aircraft by 2034, driving substantial demand for new and replacement aircraft tires
Rising Investments in Military Aviation and Defense Fleets
Global defense budgets are increasing, leading to stronger investments in military aviation. Many countries are upgrading or expanding their air forces, which directly increases demand for durable and high-performance aircraft tires. The Global Aircraft Tires Market gains from both new aircraft procurements and ongoing maintenance of existing fleets. Military aircraft often operate under extreme conditions, requiring specialized tires capable of withstanding higher stress. These stringent requirements are pushing manufacturers to develop advanced tire technologies. Growth in defense spending continues to open new opportunities in the market.
- For instance, the U.S. Department of Defense allocated over $215 billion to the Air Force in its 2024 budget, including funding for the procurement of 48 new F-35A fighter jets and 15 KC-46 tankers, all of which require specialized aircraft tires for both initial outfitting and ongoing maintenance
Stringent Safety Regulations and Maintenance Protocols
Aviation authorities around the world enforce strict safety standards for aircraft operations. These regulations include detailed protocols for regular inspection and replacement of aircraft tires. The Global Aircraft Tires Market sees increased demand due to mandatory compliance with these safety measures. Airlines must ensure optimal tire performance to avoid operational risks. Maintenance, repair, and overhaul (MRO) providers play a central role in tire management. These practices promote steady sales of replacement tires across civil and military aviation segments.
Technological Advancements in Tire Materials and Design
Innovation in tire design is contributing to improved durability, performance, and cost efficiency. Manufacturers are incorporating advanced materials such as aramid fibers and carbon composites to reduce tire weight and increase load-bearing capacity. The Global Aircraft Tires Market benefits from these improvements by offering airlines products that lower fuel consumption and increase operational reliability. Smart tire technologies with embedded sensors are emerging, helping operators monitor tire conditions in real-time. These developments enhance safety and reduce unplanned maintenance. The market continues to evolve with ongoing research and product refinement.
Market Trends
Growing Emphasis on Lightweight and Fuel-Efficient Tire Materials
Aircraft manufacturers and airlines are increasingly focusing on reducing overall aircraft weight to improve fuel efficiency. This has prompted tire manufacturers to adopt advanced materials such as aramid fibers, Kevlar composites, and carbon-based compounds. These lightweight materials help reduce rolling resistance and enhance the operational performance of aircraft tires. The Global Aircraft Tires Market is responding by innovating tire designs that meet both regulatory standards and performance expectations. Manufacturers aim to deliver longer tire life and reduced fuel consumption without compromising safety. The industry is witnessing a steady shift from traditional rubber compounds to next-generation hybrid materials to meet evolving efficiency goals.
- For instance, Michelin’s Air X SKY LIGHT tires, introduced in 2024, reduced the weight of a Boeing 737 or Airbus A320 main gear by up to 75 kilograms per aircraft, and for a fleet of 40 long-haul aircraft, this weight reduction resulted in a decrease of 3,400 metric tonnes in CO2 emissions annually, according to company environmental studies and product data.
Expansion of Commercial Aviation Driving Demand for Replacement Tires
The rising number of short-haul and long-haul flights is increasing tire replacement cycles due to higher takeoff and landing frequencies. Commercial fleet expansions in emerging markets are further accelerating tire consumption. Airlines are investing in fleet modernization, prompting higher demand for durable, high-performance tires. The Global Aircraft Tires Market is seeing consistent sales growth through both OEM and aftermarket segments. More air travel activity means shorter maintenance intervals, pushing maintenance, repair, and overhaul (MRO) providers to stock high volumes of tires. Tire suppliers are scaling up production capacity to support this demand across global aviation hubs.
- For instance, in 2024, global MRO service providers completed over 25,000 aircraft engine overhauls, with tire suppliers reporting shipment of more than 1,200,000 aircraft tires to commercial airlines and maintenance centers worldwide, according to industry association reports and aviation maintenance records
Technological Integration in Tires Enhancing Safety and Monitoring Capabilities
The market is witnessing integration of smart technologies, such as embedded sensors in aircraft tires, to enable real-time monitoring. These technologies support predictive maintenance by tracking parameters like pressure, temperature, and tread wear. The Global Aircraft Tires Market is aligning with digital transformation trends in aviation safety and operations. Airlines benefit from improved operational reliability and reduced unplanned downtimes. Smart tire systems offer enhanced data visibility, allowing airlines to streamline inspection protocols. Such innovations are helping reduce costs and ensure regulatory compliance across global aviation fleets.
Rising Defense Spending Boosting Military Aircraft Tire Segment
Governments worldwide are increasing defense budgets, leading to modernization of air forces and procurement of new military aircraft. Military jets, transporters, and helicopters require highly durable tires suited for rugged conditions and complex terrains. The Global Aircraft Tires Market is expanding its military segment to meet specialized needs in durability, load-bearing capacity, and resistance to extreme temperatures. Tire manufacturers are investing in R\&D to produce products that support higher speeds and heavier loads. Military tire demand remains stable due to strict maintenance schedules and mission-readiness requirements. This segment plays a critical role in the overall growth trajectory of the market.
Market Challenges
High Costs Associated with Raw Materials and Advanced Tire Technologies
The Global Aircraft Tires Market faces significant cost pressures due to the high price of raw materials such as synthetic rubber, aramid fibers, and carbon composites. These materials are essential for producing durable, high-performance tires capable of withstanding extreme conditions. Price volatility in global raw material markets directly impacts manufacturing costs. Advanced tire designs also require substantial investment in research and development. Companies must balance innovation with affordability to remain competitive. Rising production costs can limit the adoption of new technologies, especially among smaller airlines or budget carriers. It continues to struggle with maintaining profitability without compromising product quality.
- For instance, raw materials account for around 65 to 75 units out of every 100 units of aircraft tire production costs, with natural and synthetic rubber as the major components. A single commercial aircraft tire typically costs between 1,200 and 5,500 units, reflecting the significant impact of material prices on overall manufacturing expenses
Regulatory Compliance and Complex Certification Processes Impact Growth
Strict aviation safety regulations impose rigorous certification processes for aircraft tires, which extend development timelines and increase compliance costs. Each tire model must undergo extensive testing to meet standards set by authorities such as the FAA and EASA. These procedures create entry barriers for new manufacturers and delay time-to-market for innovations. The Global Aircraft Tires Market must navigate evolving regulatory landscapes across different regions, which complicates global distribution. Frequent updates to safety protocols require ongoing technical adjustments and documentation. It demands dedicated compliance teams and sustained investment, which can burden operational efficiency.
Market Opportunities
Rising Demand from Expanding Commercial Aviation Sector Creates Strong Market Potential
The Global Aircraft Tires Market has significant growth opportunities driven by the steady expansion of commercial aviation worldwide. Increasing air travel, particularly in emerging economies like India and Southeast Asia, is prompting airlines to expand fleets and increase flight frequencies. This surge in aircraft operations fuels higher demand for tire replacements and OEM installations. Low-cost carriers are growing their presence, further increasing aircraft utilization rates. It can capitalize on this trend by enhancing supply chains and offering tailored solutions for high-cycle operations. Companies that establish partnerships with airlines and MRO providers stand to gain long-term contracts and consistent revenue streams
Advancements in Smart Tire Technologies Open New Revenue Streams
Technological innovations in smart tires offer promising opportunities for differentiation and value-added services. Integration of sensors for real-time pressure, temperature, and wear monitoring can enhance safety and operational efficiency. The Global Aircraft Tires Market can benefit by offering predictive maintenance solutions that help airlines reduce downtime and extend tire life. Adoption of digital monitoring tools supports data-driven fleet management and aligns with broader aviation digitization trends. It enables manufacturers to bundle products with services, opening recurring revenue models. Tire makers who invest early in these technologies can strengthen their market position and improve customer loyalty.
Market Segmentation Analysis
By Tire Type
The Global Aircraft Tires Market is segmented into radial and cross-ply tires. Radial tires are gaining traction due to their longer service life, lower rolling resistance, and enhanced fuel efficiency. These advantages make them a preferred choice for commercial and modern military aircraft. Cross-ply tires, though heavier, remain in use for certain aircraft types due to their strong sidewall stability and cost-effectiveness. While cross-ply dominates legacy fleets, the shift toward newer, more efficient aircraft continues to favor radial technology. It reflects the industry's transition toward performance- and sustainability-driven solutions.
- For instance, in 2023, there were 1,393 fixed wing aircraft and 862 rotary wing aircraft delivered globally, reflecting the continued dominance of fixed wing platforms in new engine installations.
By Aircraft Type
The market divides into commercial and military aircraft, with commercial aircraft holding the largest share. Within this segment, passenger aircraft account for a major portion due to the high frequency of takeoffs and landings, requiring frequent tire replacements. Cargo aircraft also contribute steadily, driven by global e-commerce growth. Military aircraft form a critical segment, with steady demand supported by defense budgets and specialized performance requirements. The Global Aircraft Tires Market benefits from both fleet expansions and ongoing maintenance needs across all aircraft categories.
- For instance, more than 18,000 turbofan engines were in active service with commercial airlines worldwide, while approximately 6,500 turboprop, 4,200 turboshaft, and 23,000 piston engines were operational across various aviation segments.
By Platform
Fixed-wing aircraft dominate the platform segment, driven by their wide application in both commercial and defense aviation. These aircraft require robust tire solutions due to longer runway operations and heavier loads. Rotary-wing aircraft, while holding a smaller share, generate consistent demand from defense, emergency response, and utility sectors. It must cater to different operational environments, necessitating tailored tire designs for both fixed- and rotary-wing platforms.
By Supplier Industry
The supplier segment consists of OEM and aftermarket categories. OEM demand aligns with new aircraft production, while the aftermarket dominates due to frequent tire replacements. Airlines and military operators rely on timely tire replacements to ensure safety and operational readiness. The Global Aircraft Tires Market benefits significantly from recurring aftermarket revenue, making it a vital focus for tire manufacturers and service providers.
Segments
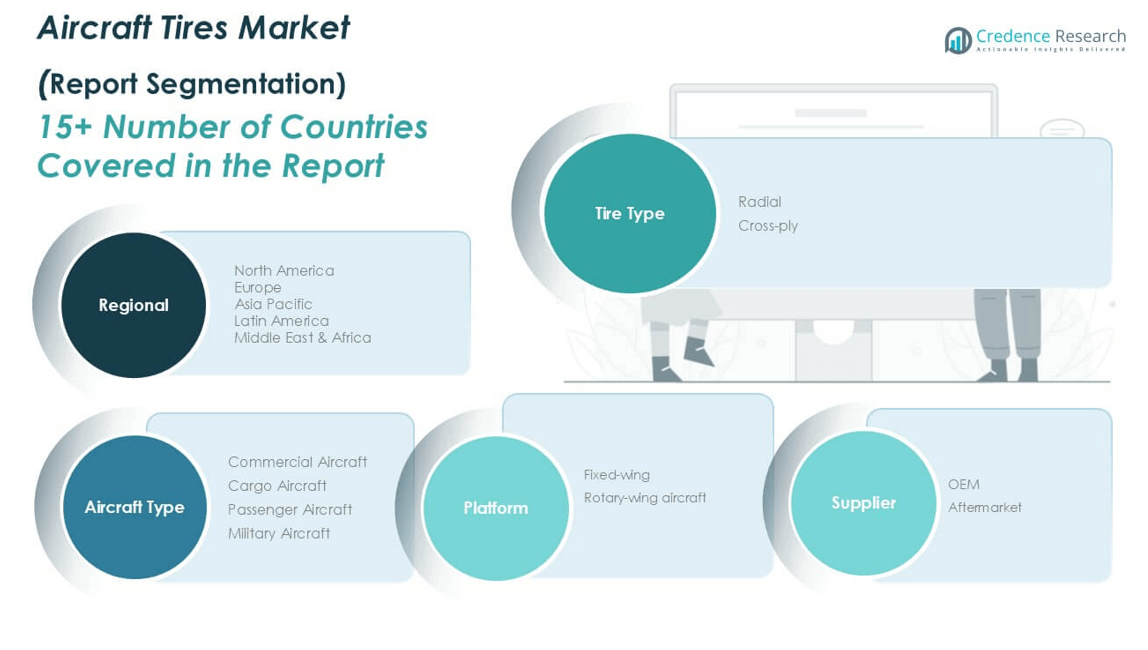
Based on Tire Type
- Radial
- Cross-ply
Based on Aircraft Type
- Commercial Aircraft
- Cargo Aircraft
- Passenger Aircraft
- Military Aircraft
Based on Platform
- Fixed-wing
- Rotary-wing aircraft
Based on Supplier Industry
- OEM
- Aftermarket
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Aircraft Tires Market
The North America Aircraft Tires Market reached USD 719.75 million in 2024 and is projected to grow to USD 997.22 million by 2032, registering a CAGR of 4.2%. It accounts for the largest regional market share at 31.7% in 2024. The United States dominates the region with its advanced aviation infrastructure, extensive commercial airline networks, and substantial military aircraft fleet. Frequent tire replacements driven by high air traffic volume and MRO activities support steady market demand. OEM demand remains high due to ongoing aircraft deliveries from major manufacturers like Boeing. The Aircraft Tires Market in this region benefits from strong aftermarket service networks and strict aviation safety compliance.
Europe Aircraft Tires Market
Europe’s Aircraft Tires Market is expected to grow from USD 601.00 million in 2024 to USD 881.05 million by 2032, registering a CAGR of 5.0%, and holding a regional market share of 26.5% in 2024. Countries such as Germany, France, and the UK lead this growth due to their expanding airline fleets and strong aviation regulatory systems. The region is seeing increased demand from both commercial carriers and defense aviation. Tire manufacturers in Europe are focusing on R\&D to develop high-durability tires suitable for regional and international flights. It benefits from close cooperation between airlines and local MRO providers. Fleet modernization initiatives continue to support long-term growth in this market.
Asia Pacific Aircraft Tires Market
Asia Pacific is the fastest-growing region, with the Aircraft Tires Market rising from USD 552.25 million in 2024 to USD 848.42 million by 2032, at a CAGR of 5.6%. It holds a regional market share of 24.3% in 2024. China, India, and Southeast Asian countries are fueling this growth through commercial aviation expansion and increased domestic travel. Rising disposable income and low-cost carrier penetration drive high aircraft utilization. The region is experiencing significant investments in airport infrastructure and new aircraft procurement. It faces growing aftermarket demand due to increased flight cycles. Manufacturers are expanding local production and partnerships to meet regional supply needs.
Latin America Aircraft Tires Market
The Latin America Aircraft Tires Market is set to increase from USD 218.70 million in 2024 to USD 280.63 million by 2032, growing at a CAGR of 3.2%, and representing a regional market share of 9.6% in 2024. Brazil and Mexico are the leading contributors, driven by the recovery in commercial aviation and tourism. Regional airlines are gradually expanding their fleets, supporting tire replacement and maintenance demand. Economic fluctuations and political instability present moderate risks, yet MRO activities remain active. It benefits from rising cargo transport and domestic air travel demand. Regional MRO facilities continue to play a vital role in maintaining operational readiness.
Middle East Aircraft Tires Market
The Middle East Aircraft Tires Market is projected to grow from USD 109.15 million in 2024 to USD 163.16 million by 2032, with a CAGR of 5.2%, and accounting for a market share of 4.8% in 2024. The region’s growth is supported by increasing investments in aviation, especially in the UAE, Qatar, and Saudi Arabia. Major international hubs in Dubai and Doha experience high aircraft traffic, boosting demand for durable, high-performance tires. Airlines in the region continue expanding their fleets to support long-haul operations. It is also benefiting from military modernization initiatives. The presence of global aviation maintenance companies strengthens regional supply chains.
Africa Aircraft Tires Market
Africa’s Aircraft Tires Market is estimated to grow from USD 67.80 million in 2024 to USD 92.67 million by 2032, with a CAGR of 4.0%, holding a regional market share of 3.0% in 2024. Growth is driven by expanding aviation infrastructure and increasing intra-regional travel. Countries like South Africa, Nigeria, and Kenya are leading the adoption of new aircraft and upgrading MRO capabilities. Fleet expansions in both commercial and humanitarian aviation segments support tire demand. Challenges such as limited airport facilities and regulatory disparities persist, yet market potential remains strong. It shows promise with ongoing international partnerships and aviation investment plans.
Key players
- Qingdao Sentury Tire Co., Ltd.
- Petlas
- Bridgestone Corporation
- Desser Tire & Rubber Co., LLC
- Dunlop Aircraft Tyres Ltd.
- Goodyear Tire & Rubber Company
- Michelin Group
- Guilin Lanyu Aircraft Tire Development Co., Ltd.
- Specialty Tires of America, Inc.
- Aviation Tires & Treads, LLC
Competitive Analysis
The Global Aircraft Tires Market is highly competitive, characterized by the presence of well-established multinational corporations alongside specialized regional players. Key companies focus on product innovation, advanced material development, and expanding their geographic footprint to maintain market leadership. It competes by offering high-quality, durable tires that meet stringent aviation safety standards while addressing cost efficiency. Strategic partnerships with aircraft manufacturers and MRO providers strengthen supply chains and customer loyalty. The market sees continuous investments in R\&D to develop smart tire technologies and improve tire performance under diverse operational conditions. Smaller players leverage niche capabilities and regional market expertise to challenge dominant firms. Overall, competitive dynamics revolve around technological advancements, regulatory compliance, and service excellence.
Recent Developments
- In May 2025, Qingdao Sentury Tire Co., Ltd. approved a final cash dividend of CNY 2.90 per 10 shares for the year 2024, which was payable on June 30, 2025. The company's A shares were eligible for this dividend. The record date for determining shareholders eligible for the dividend was June 27, 2025.
- In June 2024, Petlas showcased its innovative tire designs at The Tire Cologne 2024, attracting significant attention from industry professionals.
- In May 2025, Dunlop Aircraft Tyres Ltd. upgraded its extruders to boost production efficiency.
Market Concentration and Characteristics
The Global Aircraft Tires Market exhibits a moderately concentrated competitive landscape dominated by a few key multinational players with strong brand recognition and extensive product portfolios. These companies control a significant share through advanced manufacturing capabilities, robust distribution networks, and long-term contracts with major aircraft manufacturers and airlines. It maintains high entry barriers due to stringent regulatory requirements, significant R\&D investments, and the need for specialized materials and technologies. The market is characterized by continuous innovation focused on improving tire durability, safety, and performance under extreme operating conditions. Regional players exist but face challenges competing against established firms with global reach. The demand stability driven by both commercial and military aviation sectors supports steady revnue streams for leading companies, reinforcing the concentrated nature of the market.
Report Coverage
The research report offers an in-depth analysis based on Tire Type, Aircraft Type, Platform, Supplier Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economichanges on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Aircraft Tires Market will continue to expand, driven by increasing air travel demand and growing commercial aircraft fleets worldwide.
- Emerging economies will play a crucial role, with rising disposable incomes and improved aviation infrastructure fueling market growth.
- Technological innovation will accelerate, with manufacturers developing lighter, more durable tires to enhance fuel efficiency and reduce operational costs.
- The integration of smart tire technologies, such as embedded sensors, will improve real-time monitoring and predictive maintenance capabilities for operators.
- Military aviation demand will remain stable, supported by ongoing modernization programs and increased defense budgets globally.
- Sustainability initiatives will influence product development, encouraging the use of eco-friendly materials and manufacturing processes.
- Aftermarket services will expand due to growing maintenance, repair, and overhaul (MRO) activities, providing recurring revenue opportunities for suppliers.
- Regional market dynamics will shift, with Asia Pacific expected to register the fastest growth due to rapid fleet expansion and increasing domestic air travel.
- Collaborations between tire manufacturers, aircraft OEMs, and airlines will strengthen supply chains and foster innovation in aircraft tire solutions.
- Regulatory frameworks will continue to evolve, driving higher safety standards and compliance requirements that shape product design and market strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Global Commercial and Military Aircraft Fleets
The steady increase in global air traffic and the expansion of both commercial and military aircraft fleets are directly driving demand for aircraft tires. Frequent takeoffs and landings accelerate tire wear, necessitating regular replacements and supporting consistent market growth across both OEM and aftermarket segments.
Technological Advancements in Tire Materials and Design
Manufacturers are investing in advanced materials such as aramid fibers and carbon composites to produce lighter, more durable, and fuel-efficient tires. These innovations not only extend tire life and reduce operational costs for airlines but also align with industry trends toward sustainability and improved aircraft performance.
Stringent Aviation Safety Regulations and Maintenance Protocols
Global aviation authorities enforce rigorous safety standards that require regular inspection and timely replacement of aircraft tires. Compliance with these regulations ensures a steady demand for high-quality tires and drives growth in the maintenance, repair, and overhaul (MRO) sector.
Rising Defense Budgets and Military Modernization
Increased government spending on defense and ongoing modernization of air forces worldwide are boosting demand for specialized, high-performance aircraft tires. Military aircraft often operate under extreme conditions, requiring advanced tire technologies that can withstand higher stress and more demanding operational environments.
Integration of Smart Tire Technologies
The adoption of embedded sensors and smart tire systems enables real-time monitoring of tire pressure, temperature, and wear, supporting predictive maintenance and enhancing operational safety. These technological integrations are creating new value-added opportunities for tire manufacturers and helping airlines reduce unplanned downtime.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Aircraft Tires Market and its projected growth?
How do technological advancements influence the aircraft tires market?
Which regions dominate the Global Aircraft Tires Market?
Who are the key players in the Global Aircraft Tires Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Platform
- 1.2.1 Fixed-wing
- 1.2.2 Rotary-wing aircraft
- 1.3 By Tire Type
- 1.3.1 Radial
- 1.3.2 Cross-ply
- 1.4 By Aircraft Type
- 1.4.1 Commercial Aircraft
- 1.4.2 Cargo Aircraft
- 1.4.3 Passenger Aircraft
- 1.4.4 Military Aircraft
- 1.5 By Supplier Industry
- 1.5.1 OEM
- 1.5.2 Aftermarket
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,268.6 million → 2032: USD 3,263.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aircraft Tires Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aircraft Tires Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aircraft Tires Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aircraft Tires Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aircraft Tires Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aircraft Tires Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aircraft Tires Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aircraft Tires Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,268.6 million → 2032: USD 3,263.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aircraft Tires Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Platform - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fixed-wing
- 12.3.7.2 Rotary-wing aircraft
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Tire Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Radial
- 12.4.7.2 Cross-ply
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Aircraft Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Commercial Aircraft
- 12.5.7.2 Cargo Aircraft
- 12.5.7.3 Passenger Aircraft
- 12.5.7.4 Military Aircraft
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Supplier Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 OEM
- 12.6.7.2 Aftermarket
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aircraft Tires End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aircraft Tires Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aircraft Tires Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aircraft Tires Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Michelin Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Goodyear Tire & Rubber Company
- 18.4 Bridgestone Corporation
- 18.5 Dunlop Aircraft Tyres Ltd.
- 18.6 Continental AG
- 18.7 Qingdao Sentury Tire Co., Ltd.
- 18.8 Petlas
- 18.9 Desser Tire & Rubber Co., LLC
- 18.10 Guilin Lanyu Aircraft Tire Development Co., Ltd.
- 18.11 Specialty Tires of America, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

