
Market overview
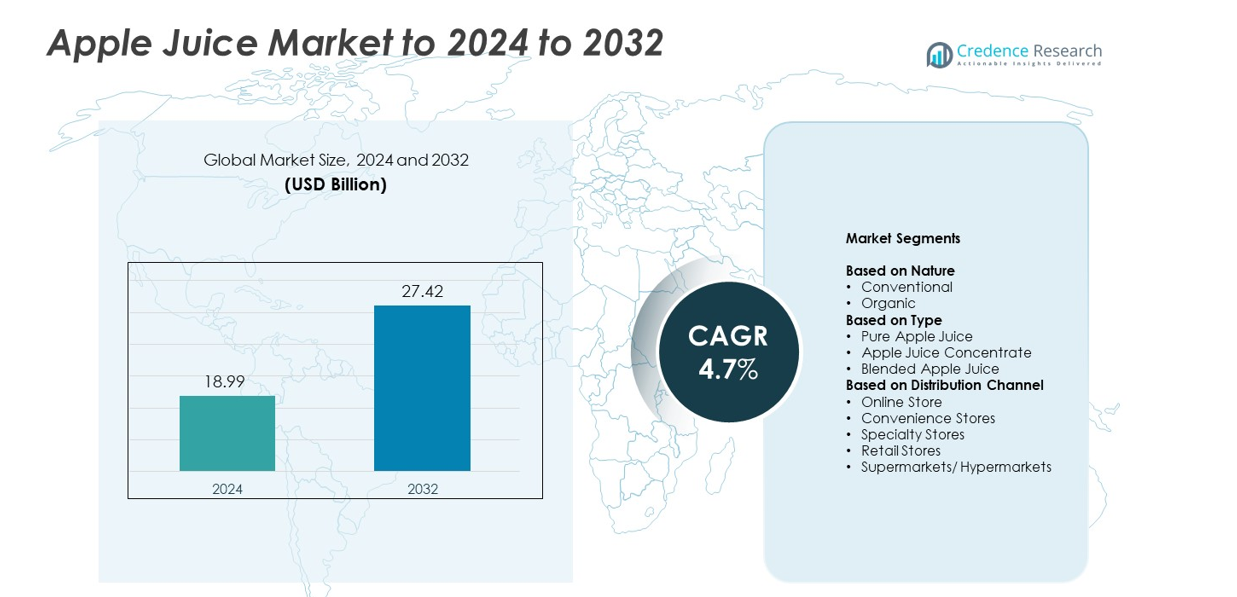
Apple Juice Market size was valued at USD 18.99 Billion in 2024 and is anticipated to reach USD 27.42 Billion by 2032, at a CAGR of 4.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Apple Juice Market Size 2024 | USD 18.99 Billion |
| Apple Juice Market, CAGR | 4.7% |
| Apple Juice Market Size 2032 | USD 27.42 Billion |
The apple juice market includes major companies such as Martinelli’s & Company, Ocean Spray Cranberries, Inc., PepsiCo, Inc., Welch’s, Rauch Fruchtsäfte GmbH & Co OG, Tree Top, Inc., Eden Foods, Inc., The Coca-Cola Company, Mott’s LLP, and The Kraft Heinz Company, all of which strengthen competition through wide product portfolios and strong retail reach. North America led the market in 2024 with about 32% share, followed by Europe at roughly 29%, supported by high consumption of natural fruit beverages. Asia Pacific held nearly 26% share and continued to grow quickly due to rising demand for convenient packaged drinks across urban regions.
Market Insights
- The apple juice market reached USD 18.99 Billion in 2024 and is projected to hit USD 27.42 Billion by 2032, expanding at a CAGR of 4.7% during the forecast period. • Strong demand for natural beverages, rising focus on clean-label drinks, and growing use of apple juice in blended and functional formulations continued to drive market expansion across global retail channels. • Key trends include rising adoption of organic products, fast growth of reduced-sugar variants, and increasing demand for convenient single-serve packaging formats in both online and offline distribution. • Competition intensified as major brands expanded product lines, improved processing technologies, and strengthened presence in supermarkets, where the leading distribution channel held about 46% share, while pure apple juice remained dominant with nearly 54% share. • North America led the market with about 32% share, followed by Europe at 29% and Asia Pacific at 26%, while conventional variants accounted for nearly 81% of total demand across regions.
Market Segmentation Analysis:
By Nature
Conventional apple juice led the market in 2024 with about 81% share. This category remained dominant due to lower production cost, wide availability, and strong demand in mass-market retail. Consumers preferred conventional juice for its stable pricing and consistent taste profile. Growth stayed steady as manufacturers improved filtration and pasteurization methods. Organic apple juice continued to expand as health-focused buyers increased, yet higher price points limited broader adoption across several regions.
- For instance, Tree Top, Inc., a prominent fruit processing cooperative headquartered in Selah, Washington, processes over 800 million pounds of fruit every year.
By Type
Pure apple juice dominated the market in 2024 with nearly 54% share. Buyers chose this type for its clean label, natural flavor, and strong presence in household consumption. Its dominance increased as brands promoted no-added-sugar formulations and transparent ingredient sourcing. Apple juice concentrate gained traction due to extended shelf life, while blended apple juice targeted younger consumers seeking flavored mixes. Pure variants maintained leadership as retailers expanded their private-label offerings across global markets.
- For instance, in the $2.63 billion U.S. chilled juice sector, Tropicana held a commanding 44 % share around that time
By Distribution Channel
Supermarkets and hypermarkets held the largest share in 2024 with around 46%. These outlets stayed dominant because buyers preferred convenient access, wide brand choices, and regular discount programs. Strong shelf visibility and frequent product rotations helped maintain category leadership. Retail stores and specialty stores also captured demand through premium and organic offerings. Online store sales grew fast with rising home delivery use, but supermarkets kept their lead due to higher footfall and established trust among family buyers.
Key Growth Drivers
Rising Demand for Natural and Ready-to-Drink Beverages
Growing preference for clean-label drinks strengthened apple juice demand across global markets. Families and young consumers shifted toward beverages with simple ingredients and no artificial additives. This trend gained support as brands marketed healthier drink options with improved transparency. Ready-to-drink formats expanded quickly due to ease of use and strong placement in supermarkets and convenience stores. The focus on natural flavor and perceived health value helped reinforce sustained volume growth in both developed and emerging regions.
- For instance, The Coca-Cola Company reports around 2.2 billion servings of its beverages are consumed every day worldwide, showing the massive global penetration of ready-to-drink drinks.
Expansion of Retail and E-Commerce Distribution
Wider access through supermarkets, specialty stores, and digital platforms boosted apple juice consumption. Retailers increased shelf space for pure and blended juice variants, while private-label products grew in visibility. Online platforms supported fast growth by offering home delivery, user reviews, and targeted promotions. Improved cold-chain logistics ensured better product quality across long distances. Strong distribution reach allowed brands to capture new consumer groups and expand their presence in competitive markets.
- For instance, in a recent fiscal period (specifically, over the 12 months preceding May 2024 earnings call), Walmart's U.S. division delivered 4.4 billion items with either same-day or next-day shipping speeds.
Increasing Use in Blended and Functional Beverage Formulations
Food and beverage companies increased apple juice use in value-added drinks such as functional blends, flavored juices, and low-sugar mixes. These new offerings attracted health-aware buyers seeking variety and lighter flavor profiles. Manufacturers also adopted innovative processing methods that improved taste consistency and nutrition retention. Growing interest in fruit-based hydration products further supported demand. Product diversification enabled brands to reach younger consumers and expand usage occasions, strengthening the market’s long-term growth outlook.
Key Trends & Opportunities
Shift Toward Organic and Premium Juice Lines
Higher interest in chemical-free and sustainably sourced products accelerated the shift toward organic apple juice. Premium variants with cold-pressed processing and reduced sugar gained attention among urban consumers. Brands highlighted orchard-to-bottle traceability and eco-friendly packaging to build trust. Rising disposable income in Asia-Pacific and Europe created room for premium positioning. This trend opened new opportunities for producers who focused on quality differentiation and ethical farming practices.
- For instance, Ocean Spray is a grower-owned cooperative with more than 700 cranberry farms and roughly 2,000 employees, illustrating how premium, origin-focused fruit beverage brands can build scale around traceable agriculture.
Growth of Convenient Packaging and On-the-Go Formats
Demand for portable drink formats increased with busy lifestyles and rising travel frequency. Lightweight bottles, single-serve packs, and recyclable materials gained popularity in retail. Manufacturers redesigned packaging to improve shelf appeal and support better portion control. These formats aligned well with consumer needs in school snacks, workplace beverages, and quick hydration moments. Expanded packaging innovation encouraged category growth across both mass and premium segments.
- For instance, Capri Sun sells about 6 billion juice pouches globally each year, demonstrating how single-serve, portable packs can dominate family and on-the-go consumption occasions.
Product Innovation with Reduced Sugar and Natural Ingredients
Consumers showed strong interest in low-sugar and naturally sweetened options. Brands responded by reformulating products using advanced filtration and gentle processing to retain flavor without added sweeteners. Innovations in fruit blending created balanced taste profiles and supported wider appeal among health-conscious groups. This shift created long-term opportunity for companies that invest in healthier, transparent, and ingredient-focused product lines.
Key Challenges
Fluctuating Raw Material Prices and Supply Uncertainty
Unstable apple crop yields caused by climate shifts and weather extremes created supply volatility. Variability in harvesting seasons influenced juice extraction costs and affected pricing across regions. Producers faced challenges maintaining consistent quality and volume, especially during poor cultivation cycles. These uncertainties pressured margins for brands dependent on large-scale sourcing. Managing long-term contracts and diversified supplier networks became essential to minimize production risks.
Rising Competition from Alternative Health Drinks
The market faced strong pressure from expanding categories such as flavored water, herbal drinks, and vitamin-enriched beverages. These alternatives attracted young buyers seeking lighter and lower-calorie hydration choices. Marketing campaigns by competing segments weakened apple juice’s position in certain urban markets. Brands needed to innovate and highlight nutritional value to maintain relevance. Increased differentiation became vital as consumer preferences continued shifting toward varied functional drink options.
Regional Analysis
North America
North America held about 32% share of the apple juice market in 2024. Strong consumption in the U.S. and Canada supported steady demand, driven by preference for pure and blended juice varieties. Retail expansion and high penetration of ready-to-drink beverages strengthened overall growth. Health-aware families continued choosing natural fruit drinks, while private-label offerings boosted affordability. Innovation in reduced-sugar formulations and convenient packaging formats helped brands maintain engagement across supermarkets and online channels.
Europe
Europe captured nearly 29% share in 2024, supported by high fruit consumption and strong adoption of organic juice options. Countries such as Germany, France, and the U.K. showed strong interest in cold-pressed and premium variants. Strict quality regulations improved product consistency and strengthened consumer trust. Growing demand for sustainable packaging and clean-label drinks supported long-term expansion. Retail chains widened shelf space for both pure and concentrate-based juices, helping maintain stable category performance.
Asia Pacific
Asia Pacific accounted for around 26% share in 2024 and remained one of the fastest-expanding regions. Rising urbanization and increasing disposable income encouraged higher consumption of packaged fruit beverages. China, Japan, South Korea, and India drove significant demand with strong interest in flavored blends and convenient on-the-go formats. E-commerce played a major role by increasing access to domestic and imported brands. Growing youth population and lifestyle shifts further supported broad market growth.
Latin America
Latin America held close to 8% share in 2024, driven by growing acceptance of packaged juices and expanding retail networks. Brazil, Mexico, and Argentina experienced rising demand for affordable pure and concentrate-based apple juice options. Consumers adopted bottled fruit beverages as daily refreshment choices, supported by improved distribution in supermarkets and convenience stores. Local producers introduced cost-effective formats to appeal to value-focused buyers. Regional growth remained modest but steady due to improving supply chains.
Middle East and Africa
Middle East and Africa accounted for about 5% share in 2024. Demand grew as consumers increased preference for packaged juices over traditional homemade drinks. Countries such as Saudi Arabia, UAE, and South Africa showed rising interest in premium and imported apple juice varieties. Expanding hypermarket chains and higher tourism activity supported stronger visibility for global brands. Growth remained supported by rising youth population and wider adoption of ready-to-drink beverages.
Market Segmentations:
By Nature
- Conventional
- Organic
By Type
- Pure Apple Juice
- Apple Juice Concentrate
- Blended Apple Juice
By Distribution Channel
- Online Store
- Convenience Stores
- Specialty Stores
- Retail Stores
- Supermarkets/ Hypermarkets
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the apple juice market features major players such as Martinelli’s & Company, Ocean Spray Cranberries, Inc., PepsiCo, Inc., Welch’s, Rauch Fruchtsäfte GmbH & Co OG, Tree Top, Inc., Eden Foods, Inc., The Coca-Cola Company, Mott’s LLP, and The Kraft Heinz Company. Market competition intensified as brands focused on strong distribution networks, diverse product portfolios, and steady innovation in pure, concentrate, and blended juice lines. Companies strengthened their retail presence through targeted promotions, improved packaging designs, and shelf optimization across supermarkets, convenience outlets, and online platforms. Many producers expanded their organic and reduced-sugar offerings to match rising consumer interest in healthier beverages. Investment in advanced processing and cold-pressed technologies helped enhance product quality and extend shelf life. Firms also prioritized sustainability through eco-friendly bottling and responsible sourcing practices. Competitive intensity remained high as private-label ranges gained popularity, pushing established brands to maintain differentiation through quality, flavor innovation, and marketing initiatives.
Key Player Analysis
- Martinelli’s & Company
- Ocean Spray Cranberries, Inc.
- PepsiCo, Inc.
- Welch’s
- Rauch Fruchtsäfte GmbH & Co OG
- Tree Top, Inc.
- Eden Foods, Inc.
- The Coca-Cola Company
- Mott’s LLP
- The Kraft Heinz Company
Recent Developments
- In 2025, PepsiCo completed the acquisition of poppi, a functional soda brand made with prebiotics, fruit juice, and apple cider vinegar.
- In 2025, Tree Top completed a brand refresh with a new logo and packaging design aimed at enhancing shelf appeal and consumer attraction for its apple juices and sauces.
- In 2024, Mott’s launched Mott’s Active, a new apple juice blend combined with coconut water and electrolytes, targeting hydration for children without added sugars.
Report Coverage
The research report offers an in-depth analysis based on Nature, Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow as consumers continue choosing natural fruit-based beverages.
- Demand for organic and clean-label apple juice will rise across major regions.
- Brands will expand reduced-sugar and functional juice blends to attract health-focused buyers.
- Convenience packaging and single-serve formats will gain stronger shelf presence.
- E-commerce platforms will play a larger role in global distribution and product discovery.
- Manufacturers will invest more in sustainable farming and eco-friendly packaging.
- Premium cold-pressed and minimally processed juice lines will expand in urban markets.
- Private-label products will strengthen competition in retail channels.
- Supply-chain efficiency will improve as producers adopt advanced processing technologies.
- Emerging markets will drive new consumption due to rising incomes and lifestyle shifts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Preference for Natural and Clean-Label Beverages
Consumers are increasingly seeking beverages with simple, recognizable ingredients and no artificial additives, driving demand for apple juice as a natural, clean-label option. This trend is reinforced by health-conscious families and young buyers who prioritize transparency and perceived health benefits.
Expansion of Retail and E-Commerce Distribution
Wider availability of apple juice through supermarkets, specialty stores, and online platforms has made it more accessible to a broader consumer base. Enhanced cold-chain logistics and the growth of e-commerce have enabled brands to reach new markets and offer convenient home delivery options.
Growth in Functional and Blended Juice Formulations
Manufacturers are innovating with apple juice by incorporating it into functional blends, low-sugar mixes, and flavored beverages, appealing to health-aware consumers seeking variety and added nutritional benefits. This diversification attracts younger demographics and expands usage occasions.
Rising Demand for Convenient Packaging and On-the-Go Formats
Busy lifestyles and increased travel have boosted demand for single-serve, portable, and recyclable packaging formats. These innovations cater to consumers looking for quick, easy hydration solutions, especially in school, workplace, and travel settings.
Shift Toward Organic and Premium Juice Lines
Growing interest in organic, sustainably sourced, and premium apple juice - often featuring cold-pressed processing and eco-friendly packaging - has opened new market opportunities. Urban consumers and those with higher disposable incomes are driving this shift, encouraging brands to differentiate through quality and ethical sourcing.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for APPLE JUICE Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the APPLE JUICE Market projected to grow between 2025 and 2032?
Which is the leading region of the market for apple juice?
What are the key drivers for the growth of the apple juice market?
Which is the major segment in the apple juice market by nature?
Who are the leading companies in the APPLE JUICE Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Pure Apple Juice
- 1.2.2 Apple Juice Concentrate
- 1.2.3 Blended Apple Juice
- 1.3 By Nature
- 1.3.1 Conventional
- 1.3.2 Organic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 18.99 Billion → 2032: USD 27.42 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Apple Juice Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Apple Juice Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Apple Juice Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Apple Juice Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Apple Juice Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Apple Juice Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Apple Juice Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Apple Juice Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 18.99 Billion → 2032: USD 27.42 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Apple Juice Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pure Apple Juice
- 12.3.7.2 Apple Juice Concentrate
- 12.3.7.3 Blended Apple Juice
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Nature - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional
- 12.4.7.2 Organic
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Apple Juice Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Apple Juice Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Apple Juice Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Martinelli’s & Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Ocean Spray Cranberries, Inc.
- 17.4 PepsiCo, Inc.
- 17.5 Welch’s
- 17.6 Rauch Fruchtsäfte GmbH & Co OG
- 17.7 Tree Top, Inc.
- 17.8 Eden Foods, Inc.
- 17.9 The Coca-Cola Company
- 17.10 Mott’s LLP
- 17.11 The Kraft Heinz Company
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

