
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Asia Pacific Healthcare Supply Chain Management Market Size 2023 | USD 729.14 million |
| Asia Pacific Healthcare Supply Chain Management Market, CAGR | 13.5% |
| Asia Pacific Healthcare Supply Chain Management Market Size 2032 | USD 2,278.06 million |
Market Overview
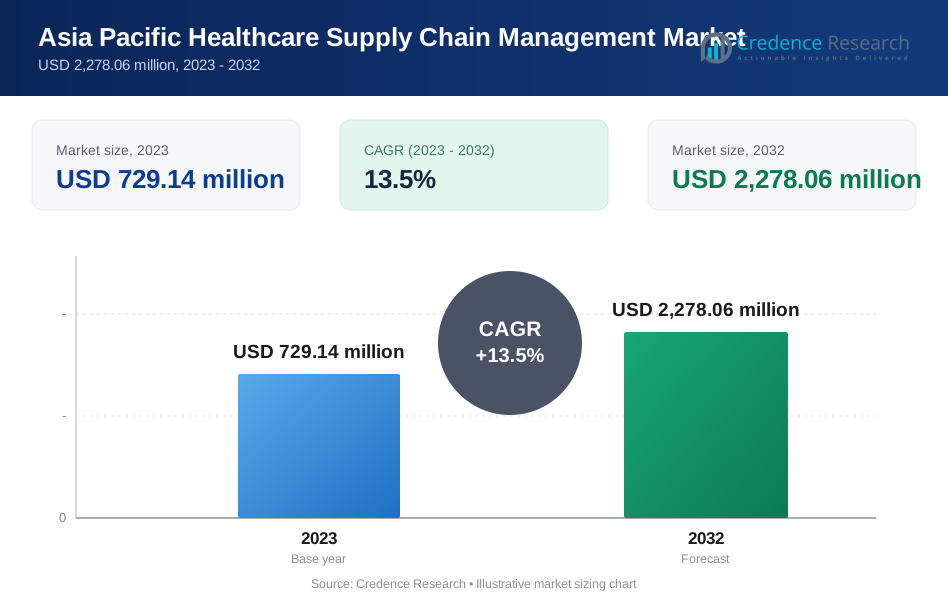
Asia Pacific Healthcare Supply Chain Management market size was valued at USD 729.14 million in 2023 and is anticipated to reach USD 2,278.06 million by 2032, at a CAGR of 13.5% during the forecast period (2023-2032).
The Asia Pacific Healthcare Supply Chain Management market is witnessing robust growth driven by increasing healthcare expenditures, rapid digital transformation, and the growing need for efficient inventory and logistics management. Governments across the region are investing in healthcare infrastructure and adopting regulatory frameworks that encourage transparency and traceability in supply chains. The rising prevalence of chronic diseases and aging populations further intensify the demand for timely delivery of medical products and services. Additionally, advancements in technologies such as artificial intelligence (AI), blockchain, and the Internet of Things (IoT) are streamlining operations, reducing costs, and improving decision-making across the supply chain. The shift toward value-based healthcare and the integration of cloud-based solutions are also enhancing real-time visibility and collaboration among stakeholders. These trends collectively contribute to the market’s strong growth trajectory and reflect a broader transformation toward resilient, data-driven, and patient-centric supply chain ecosystems in the Asia Pacific healthcare sector.
The Asia Pacific Healthcare Supply Chain Management market demonstrates diverse growth patterns across its key geographies, with countries like China, Japan, India, and Australia leading advancements due to strong healthcare infrastructure, rapid digital adoption, and government support for health system modernization. Emerging economies such as Indonesia, Vietnam, and the Philippines are witnessing accelerated growth, driven by increasing healthcare investments and the expansion of pharmaceutical and logistics networks. These regions are focusing on improving supply chain efficiency to meet rising demand for quality care and timely delivery of medical products. The market features the presence of several prominent players offering integrated supply chain solutions, including IBM Corporation, SAP SE, Oracle Corporation, GEP, and Workday, Inc. These companies are enhancing their regional footprint through strategic partnerships, technology innovation, and tailored offerings that address the unique challenges of the Asia Pacific healthcare landscape. Their efforts are shaping a more agile, transparent, and data-driven supply chain ecosystem across the region.
Market Insights
- The Asia Pacific Healthcare Supply Chain Management market was valued at USD 729.14 million in 2023 and is projected to reach USD 2,278.06 million by 2032, growing at a CAGR of 13.5%.
- The global healthcare supply chain management market was valued at USD 2,480.91 million in 2023 and is projected to reach USD 6,991.12 million by 2032, growing at a CAGR of 12.2% during the forecast period.
- Rising healthcare expenditure and infrastructure development across emerging economies are driving the demand for efficient supply chain solutions.
- Increasing adoption of AI, IoT, and cloud-based platforms is transforming supply chain operations and improving real-time visibility.
- The market is witnessing growing competition with key players like IBM, SAP, Oracle, and GEP expanding their regional presence.
- Fragmented infrastructure, regulatory complexities, and data privacy concerns continue to restrain seamless market growth.
- China, Japan, India, and Australia are leading the regional market due to advanced digital adoption and strong healthcare systems.
- Demand for resilient, patient-centric, and sustainable supply chains is shaping investment strategies and innovation across the sector.
Report Scope
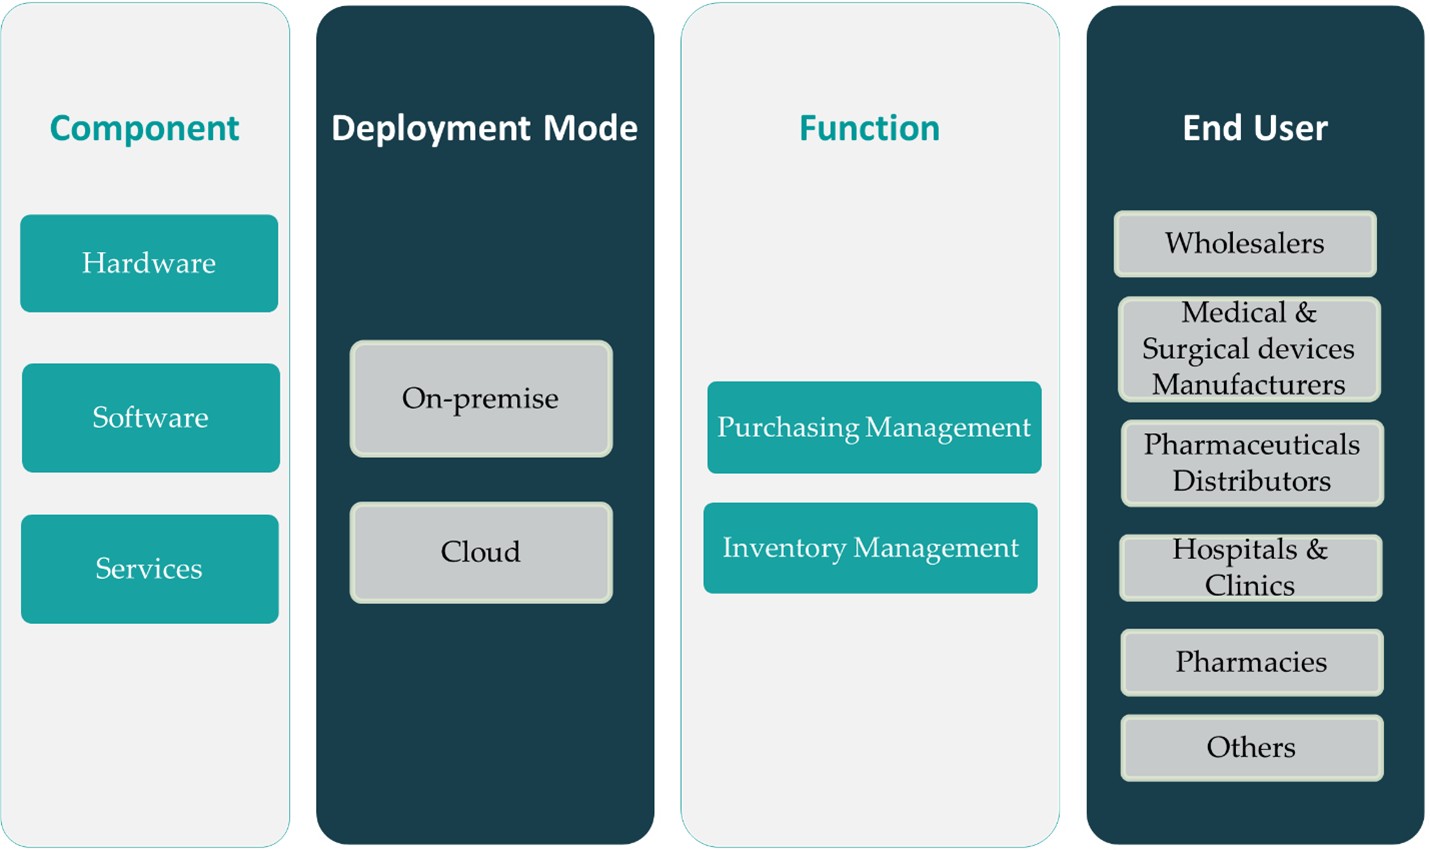
This report segments the Asia Pacific Healthcare Supply Chain Management Market as follows:
Market Drivers
Rising Healthcare Expenditure and Infrastructure Development
One of the key drivers of the Asia Pacific Healthcare Supply Chain Management market is the significant increase in healthcare expenditure across the region. Governments and private sectors are investing heavily in expanding healthcare infrastructure to address the growing population and rising disease burden. For instance, the Indian government has launched initiatives like Ayushman Bharat to provide universal health coverage, which includes the establishment of new hospitals and clinics. Countries like China, India, Japan, and Australia are prioritizing healthcare modernization, which necessitates more advanced and efficient supply chain systems. With the establishment of new hospitals, clinics, and diagnostic centers, there is a heightened demand for timely and streamlined delivery of medical supplies and equipment. This surge in infrastructure development creates a parallel need for robust supply chain solutions that ensure operational efficiency, minimize delays, and support optimal resource allocation.
Regulatory Support and Policy Initiatives
Supportive government regulations and policy initiatives are significantly contributing to the market's growth. Several countries in the Asia Pacific region are implementing healthcare reforms and regulatory frameworks that promote the adoption of advanced supply chain management systems. For instance, Japan's Ministry of Health, Labour and Welfare has introduced serialization mandates to ensure the safety and quality of healthcare products. These include mandates for serialization, quality assurance, and stricter compliance with global standards. In addition, regional collaborations and trade agreements are fostering cross-border pharmaceutical trade, which further drives the need for harmonized and efficient supply chains. Governments are also investing in public-private partnerships to build digital infrastructure and encourage innovation in supply chain logistics. These policy-driven efforts are helping to standardize processes, ensure the safety and quality of healthcare products, and promote sustainability in healthcare delivery.
Technological Advancements and Digital Transformation
Rapid digital transformation is playing a pivotal role in enhancing healthcare supply chain operations across the Asia Pacific region. The adoption of technologies such as Artificial Intelligence (AI), Machine Learning (ML), Internet of Things (IoT), and blockchain is driving improvements in forecasting, inventory management, and real-time tracking. These technologies facilitate greater transparency, reduce operational inefficiencies, and enable data-driven decision-making. For example, predictive analytics can help forecast demand for critical medical supplies, while blockchain ensures product traceability and prevents counterfeiting. Cloud-based platforms are also gaining traction, offering scalable solutions that allow healthcare providers and distributors to manage supply chains with improved coordination and lower overhead costs. This digital evolution not only boosts productivity but also strengthens resilience during disruptions such as pandemics or natural disasters.
Growing Demand for Patient-Centric and Value-Based Healthcare
The shift toward patient-centric care and value-based healthcare models is another important market driver. Healthcare providers are increasingly focused on improving patient outcomes and ensuring timely access to essential treatments and medications. This requires a more agile, responsive, and integrated supply chain system. Customized delivery models, temperature-sensitive logistics for biologics and vaccines, and last-mile delivery solutions are gaining prominence. Additionally, as patient expectations evolve and demand for home-based care and telehealth services increases, supply chains must adapt to support these emerging service models. As a result, healthcare organizations are prioritizing supply chain modernization to enhance service quality, reduce costs, and achieve better clinical and operational outcomes.
Market Trends
Adoption of Advanced Analytics and Predictive Technologies
One of the most significant trends shaping the Asia Pacific healthcare supply chain landscape is the growing integration of advanced analytics and predictive technologies. Organizations are leveraging big data, artificial intelligence (AI), and machine learning (ML) to improve demand forecasting, manage inventory, and optimize logistics. For instance, the National Center for Asia-Pacific Economic Cooperation (APEC) highlighted in a report that healthcare firms are using AI-driven predictive analytics to anticipate supply needs and reduce waste during disruptions. By analyzing patterns and behaviors in real-time, healthcare providers can better manage stock levels of critical medicines and medical devices, thereby enhancing operational efficiency and patient care outcomes. The use of predictive analytics is becoming a cornerstone of strategic decision-making across the supply chain.
Emphasis on Supply Chain Resilience and Risk Management
The COVID-19 pandemic underscored the importance of building resilient and flexible supply chains in the healthcare sector. As a result, organizations in the Asia Pacific region are prioritizing risk mitigation strategies and resilience planning. For instance, a survey conducted by APEC revealed that healthcare companies are increasingly adopting multi-sourcing strategies and digital twin technology to mitigate risks. Multi-sourcing of suppliers, diversification of logistics partners, and the use of digital twin technology are gaining traction. Companies are investing in scenario planning and contingency frameworks to ensure uninterrupted supply of essential healthcare products during unforeseen events. In addition, there is a growing emphasis on local sourcing and regional distribution hubs to minimize dependency on global supply routes and reduce lead times. These efforts collectively aim to build agile and responsive supply chain systems capable of withstanding future challenges.
Expansion of Cold Chain and Specialty Logistics
With the rise in demand for temperature-sensitive pharmaceuticals, biologics, and vaccines, the expansion of cold chain logistics is emerging as a key trend. Asia Pacific markets are witnessing increased investment in cold storage infrastructure, specialized transportation, and monitoring systems to maintain product integrity throughout the supply chain. The development of end-to-end cold chain solutions ensures compliance with stringent regulatory standards and guarantees the safe delivery of high-value therapeutics. Furthermore, the growth of personalized medicine and precision therapies necessitates advanced logistics capabilities, including real-time temperature tracking and last-mile delivery services. This trend is reshaping the logistics landscape and prompting healthcare organizations to strengthen their cold chain capabilities.
Sustainability and Green Supply Chain Initiatives
Sustainability has become a strategic priority for healthcare supply chains in the Asia Pacific region. Companies are increasingly adopting environmentally responsible practices, including reducing packaging waste, optimizing transportation routes, and transitioning to eco-friendly materials. Regulatory pressure and stakeholder expectations are driving the shift toward green supply chains that align with broader environmental, social, and governance (ESG) goals. The implementation of circular economy principles, such as recycling and reverse logistics, is gaining momentum. By integrating sustainability into supply chain operations, healthcare organizations aim to not only reduce their environmental footprint but also improve efficiency and enhance brand reputation in a competitive market.
Market Challenges Analysis
Fragmented Infrastructure and Lack of Standardization
One of the primary challenges facing the Asia Pacific healthcare supply chain is the fragmented infrastructure and lack of standardization across countries and regions. The diversity of healthcare systems, regulatory environments, and logistical capabilities leads to inconsistencies in supply chain practices and limited interoperability. For instance, a report by the National Center for Asia-Pacific Economic Cooperation (APEC) highlighted that many developing nations in the region still rely on manual or semi-automated systems, which hinder real-time visibility and increase the risk of errors or stockouts. Furthermore, inadequate transportation networks and underdeveloped cold chain infrastructure in rural or remote areas create bottlenecks, particularly in the distribution of temperature-sensitive medical supplies and vaccines. These disparities complicate the implementation of unified supply chain strategies and limit the scalability of digital and automated solutions across the region.
Regulatory Complexities and Data Security Concerns
The complex and evolving regulatory landscape presents another major challenge for healthcare supply chain stakeholders in the Asia Pacific region. Each country enforces its own set of compliance requirements related to pharmaceutical distribution, product traceability, and import-export controls, which can be difficult for multinational companies to navigate. Frequent policy changes, customs delays, and lack of harmonization often lead to supply chain disruptions and increased administrative burdens. Additionally, as more organizations adopt digital platforms and cloud-based systems, concerns around data security and patient privacy are intensifying. Cybersecurity threats and the lack of standardized data protection laws across the region create vulnerabilities that can compromise critical healthcare operations. To overcome these challenges, companies must invest in robust compliance frameworks, secure IT infrastructure, and cross-border collaboration strategies to ensure seamless and compliant supply chain operations.
Market Opportunities
The Asia Pacific Healthcare Supply Chain Management market presents significant growth opportunities driven by increasing digital adoption, expanding healthcare access, and rising demand for efficiency in logistics and inventory management. As governments across the region continue to invest in healthcare infrastructure, there is a growing need for advanced supply chain solutions that can support rapid urbanization, population growth, and the rising burden of chronic diseases. Emerging markets such as India, Indonesia, Vietnam, and the Philippines are undergoing healthcare modernization, opening doors for technology providers and logistics firms to offer scalable and localized supply chain services. The integration of cloud-based platforms, AI-powered analytics, and IoT-enabled tracking systems enables healthcare providers to enhance transparency, reduce costs, and improve service delivery—making these technologies critical enablers for long-term growth.
Furthermore, the growing focus on regional self-reliance and localized manufacturing in the wake of global supply chain disruptions has created new avenues for investment and collaboration. The rise in domestic pharmaceutical production and medical device manufacturing presents an opportunity for supply chain solution providers to offer specialized services tailored to the needs of local producers. Additionally, the increasing demand for home healthcare, telemedicine, and personalized treatment options is prompting a shift toward more agile and patient-centric supply chains. This transformation supports innovation in last-mile delivery, cold chain management, and automated fulfillment systems. As regulatory frameworks become more supportive and harmonized, stakeholders who invest in digital transformation, sustainability, and resilience will be well-positioned to capitalize on the growing demand for efficient, secure, and scalable healthcare supply chain solutions across the Asia Pacific region.
Market Segmentation Analysis:
By Component:
The Asia Pacific Healthcare Supply Chain Management market, when segmented by component, comprises hardware, software, and services. Among these, the software segment holds a dominant share due to the increasing adoption of integrated supply chain platforms that enhance visibility, analytics, and decision-making capabilities across healthcare organizations. Software solutions, including inventory management, procurement, and transportation management systems, enable end-to-end coordination, reduce costs, and improve operational efficiency. The demand for these platforms is further driven by the rising focus on data-driven supply chain management and regulatory compliance. Meanwhile, the hardware segment, which includes RFID tags, barcode scanners, and sensors, supports real-time tracking and data collection but accounts for a smaller share. The services segment is witnessing rapid growth, driven by the need for system integration, training, and ongoing technical support. As healthcare systems expand and digitalize, service providers play a critical role in ensuring the successful implementation and optimization of supply chain technologies across diverse healthcare settings in the region.
By Deployment Mode:
In terms of deployment mode, the Asia Pacific Healthcare Supply Chain Management market is segmented into on-premise and cloud-based solutions. While on-premise systems have traditionally been favored due to greater control over infrastructure and data security, the market is experiencing a notable shift toward cloud-based deployment. Cloud solutions offer scalability, flexibility, and cost-effectiveness, making them especially attractive to mid-sized and emerging healthcare providers in the region. The growing availability of secure cloud infrastructure and advancements in cybersecurity are helping to alleviate concerns about data breaches and privacy, further supporting this transition. Moreover, cloud-based platforms facilitate real-time collaboration, remote access, and seamless integration with other digital health systems, which is crucial in managing complex supply chain networks across geographically dispersed locations. As digital transformation accelerates, particularly in developing countries, cloud deployment is expected to outpace on-premise systems, offering significant growth opportunities for vendors delivering agile and customizable solutions tailored to evolving healthcare supply chain needs.
Segments:
Based on Component:
- Hardware
- Software
- Services
Based on Deployment Mode:
- On-premise
- Cloud
Based on Function:
- Purchasing Management
- Inventory Management
Based on End User:
- Medical & Surgical Device Manufacturers
- Pharmaceutical Distributors
- Wholesalers
- Hospital & Clinics
- Pharmacies
- Others
Based on the Geography:
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
Regional Analysis
China
China holds the largest market share in the Asia Pacific Healthcare Supply Chain Management market, accounting for approximately 30% of the total regional revenue in 2023. This dominance is driven by China's vast and rapidly expanding healthcare infrastructure, substantial investments in digital health technologies, and robust pharmaceutical manufacturing base. The Chinese government’s strategic initiatives to modernize healthcare systems such as the “Healthy China 2030” plan—have accelerated the adoption of smart supply chain solutions. Additionally, the presence of major domestic players and growing international partnerships have strengthened the technological capabilities within the country’s healthcare logistics ecosystem. China's ongoing push toward digital transformation and regional leadership in artificial intelligence and cloud computing further supports the expansion of advanced supply chain management systems.
Japan
Japan is the second-largest contributor, with a market share of approximately 19% in 2023. Japan’s highly developed healthcare system and its early adoption of automation and IT-driven logistics solutions have positioned it as a mature market for supply chain management technologies. The country’s aging population and growing demand for long-term care services necessitate efficient and reliable supply chains to manage the delivery of medical supplies and pharmaceuticals. Furthermore, Japanese healthcare organizations are emphasizing precision and compliance, creating a strong demand for traceability solutions, automated inventory control, and real-time monitoring. The government’s support for digitization and investments in smart hospital infrastructure continue to drive innovation in the sector.
India
India holds a significant and fast-growing share of the market, capturing approximately 14% in 2023. The country’s expanding healthcare infrastructure, increasing digitization initiatives, and booming pharmaceutical industry are major growth drivers. India’s push for public-private partnerships and government-led initiatives like Ayushman Bharat and the National Digital Health Mission have boosted the adoption of technology in healthcare logistics. The rise in domestic manufacturing of medical devices and pharmaceuticals has led to increased demand for integrated supply chain platforms that support visibility, compliance, and efficiency. Additionally, the increasing focus on rural healthcare delivery presents an opportunity for the development of last-mile logistics and cold chain systems.
Australia
Australia accounts for approximately 9% of the regional market share, benefiting from a well-regulated and technologically advanced healthcare system. The country’s emphasis on healthcare quality, data transparency, and operational efficiency drives the adoption of end-to-end supply chain management platforms. Australia’s strong focus on innovation and sustainability aligns with broader trends in green supply chains and resilient logistics frameworks. Moreover, collaborations between public health institutions and technology providers foster continuous advancements in supply chain automation, analytics, and risk management. Australia's strategic geographic location also enhances its role as a distribution hub for medical products across Oceania and Southeast Asia.
Key Player Analysis
- IBM Corporation
- SAP SE
- GEP
- Workday, Inc.
- Oracle Corporation
- Infor
- Epicor Software Corporation
- Cardinal Health
- Blue Yonder Group, Inc.
- LogiTag Systems
- Coupa
- Medsphere Systems Corporation
- Manhattan Associates
- Others
Competitive Analysis
The Asia Pacific Healthcare Supply Chain Management market is characterized by intense competition among leading global and regional players striving to enhance operational capabilities, expand market presence, and deliver innovative solutions. Key players such as IBM Corporation, SAP SE, Oracle Corporation, GEP, Workday Inc., Infor, Epicor Software Corporation, Cardinal Health, Blue Yonder Group Inc., LogiTag Systems, Coupa, Medsphere Systems Corporation, and Manhattan Associates are actively shaping the competitive landscape. These companies focus on integrating advanced technologies like artificial intelligence, blockchain, cloud computing, and real-time analytics to improve supply chain transparency, efficiency, and responsiveness. Strategic collaborations, mergers and acquisitions, and regional expansions are common tactics employed to gain a competitive edge. Players are also tailoring solutions to meet local regulatory requirements and healthcare challenges unique to Asia Pacific markets. Additionally, the shift toward SaaS-based and cloud-deployed platforms has intensified competition in delivering scalable, secure, and cost-effective solutions. As demand for data-driven, patient-centric, and resilient supply chains grows, these key players are expected to continue investing in R&D, digital transformation, and customer-centric services to maintain and grow their market share in this dynamic region.
Recent Developments
- In March 2025, SAP unveiled its vision for autonomous supply chains embedded with AI-first strategies and launched SAP Business Data Cloud for enhanced operational visibility.
- In February 2025, GHX celebrated its Supply Chains of Distinction Award, recognizing top-performing hospitals that excelled in automation and clinical integration.
- In January 2025, McKesson's Practice Insights was named a Qualified Clinical Data Registry by CMS, enabling oncology practices to streamline data reporting and improve patient care.
- In November 2024, IBM integrated generative AI into its cognitive control tower, enabling natural language queries for faster decision-making. This transformation saved $388 million in inventory and shipping costs.
- In September 2024, Oracle introduced RFID-powered replenishment solutions in its Cloud SCM platform to automate inventory management and improve visibility across healthcare supply chains.
Market Concentration & Characteristics
The Asia Pacific Healthcare Supply Chain Management market exhibits moderate to high market concentration, with a mix of established global technology providers and emerging regional players. Leading companies such as IBM, SAP, Oracle, and GEP dominate the market due to their robust technological capabilities, wide solution portfolios, and strong client networks. These players primarily cater to large healthcare providers, pharmaceutical manufacturers, and government health systems, offering integrated platforms that support real-time visibility, compliance, and predictive analytics. The market is characterized by rapid digital transformation, increasing demand for cloud-based and AI-powered solutions, and growing emphasis on supply chain resilience and sustainability. Despite the dominance of key players, opportunities exist for smaller firms and startups to address localized needs, especially in underserved and emerging economies. Customization, affordability, and regulatory alignment are critical success factors in this competitive landscape. The sector continues to evolve dynamically, driven by innovation, policy reforms, and growing healthcare delivery demands across the region.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, Function, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of AI, IoT, and predictive analytics will continue to drive smarter and more responsive supply chain operations.
- Cloud-based supply chain management solutions will see accelerated growth due to their scalability and cost-efficiency.
- Demand for end-to-end visibility and real-time data will increase across healthcare providers and pharmaceutical companies.
- Cold chain logistics will expand significantly to support the rising use of biologics, vaccines, and temperature-sensitive therapies.
- Healthcare organizations will prioritize supply chain resilience to mitigate risks from global disruptions.
- Regional governments will increase investments in digital infrastructure and supply chain modernization.
- Sustainability initiatives will influence supply chain strategies, emphasizing eco-friendly packaging and waste reduction.
- Partnerships between technology firms and healthcare providers will grow to deliver tailored, localized solutions.
- Regulatory harmonization efforts will simplify cross-border supply chain operations in Asia Pacific.
- Emerging markets will drive demand for agile, patient-centric, and technology-enabled supply chain solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asia Pacific Healthcare Supply Chain Management market?
What factors are driving the growth of the Asia Pacific Healthcare Supply Chain Management market?
What are some challenges faced by the Asia Pacific Healthcare Supply Chain Management market?
Who are the major players in the Asia Pacific Healthcare Supply Chain Management market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia Pacific Healthcare Supply Chain Management Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Asia Pacific Healthcare Supply Chain Management Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 729.14 million → 2032: USD 2,278.06 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia Pacific Healthcare Supply Chain Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia Pacific Healthcare Supply Chain Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia Pacific Healthcare Supply Chain Management Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Asia Pacific Healthcare Supply Chain Management Market Drivers
- 3.3 Asia Pacific Healthcare Supply Chain Management Market Restraints & Challenges
- 3.4 Asia Pacific Healthcare Supply Chain Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia Pacific Healthcare Supply Chain Management Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia Pacific Healthcare Supply Chain Management Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia Pacific Healthcare Supply Chain Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia Pacific Healthcare Supply Chain Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Asia Pacific Healthcare Supply Chain Management Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Asia Pacific Healthcare Supply Chain Management market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia Pacific Healthcare Supply Chain Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia Pacific Healthcare Supply Chain Management Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Asia Pacific Healthcare Supply Chain Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia Pacific Healthcare Supply Chain Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Asia Pacific Healthcare Supply Chain Management Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Asia Pacific Healthcare Supply Chain Management Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Asia Pacific Healthcare Supply Chain Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Asia Pacific Healthcare Supply Chain Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Asia Pacific Healthcare Supply Chain Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Asia Pacific Healthcare Supply Chain Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Asia Pacific Healthcare Supply Chain Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Asia Pacific Healthcare Supply Chain Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Asia Pacific Healthcare Supply Chain Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
