
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Assets Under Management (AUM) Market Size 2023 | USD 126,987.45 Billion |
| Assets Under Management (AUM) Market, CAGR | 5.50% |
| Assets Under Management (AUM) Market Size 2032 | USD 205,604.65 Billion |
Market Overview
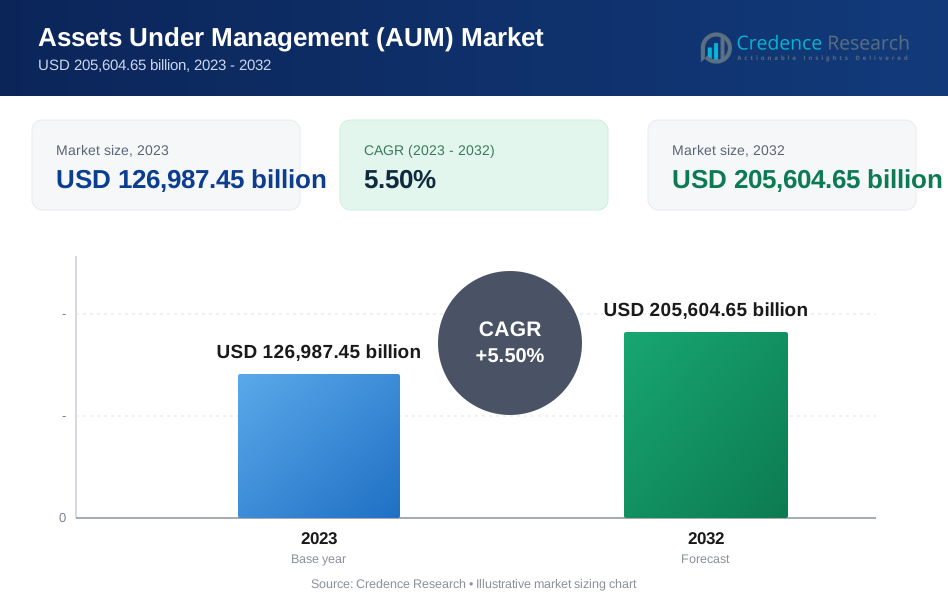
The Assets Under Management (AUM) market encapsulates the total market value of investments managed by financial institutions on behalf of clients. AUM covers a broad range of asset classes, including equities, bonds, real estate, and alternative investments such as private equity and hedge funds. The magnitude of AUM can serve as a barometer for the financial health of investment firms and the confidence of investors. The Assets Under Management (AUM) market is projected to grow from USD 126,987.45 billion in 2023 to USD 205,604.65 billion in 2032, at a Compound Annual Growth Rate (CAGR) of 5.50%.
The proliferation of AUM has been bolstered by economic expansion in emerging markets, advancements in financial technology, and regulatory developments that have opened new channels for investments. Demographic shifts, such as the aging population in developed nations, have also played a critical role as more individuals turn towards retirement savings plans and wealth management services to secure their financial future. Moreover, the low-interest environment over the past decade has pushed investors to diversify their portfolios beyond traditional safe havens like bonds, steering them towards equities and alternative investments that promise higher yields.
The AUM market is also characterized by its competitive and dynamic nature, with firms constantly innovating to offer differentiated products and capture market share. Asset managers are increasingly leveraging technology to enhance operational efficiency and personalize customer service, incorporating robo-advisors and platforms that offer algorithm-driven advice and portfolio management.
Despite the recent economic turbulence caused by global events such as the COVID-19 pandemic, the AUM market has shown resilience, with rapid recoveries in asset values fueled by aggressive monetary policies and fiscal stimuli. This resilience underscores the robust nature of the market and its critical role in global finance.
Key Market Drivers
Economic growth and wealth accumulation
One of the primary drivers of the Assets Under Management (AUM) market is the increasing accumulation of wealth among individuals and institutional investors. As global economies expand and personal income levels rise, there is a noticeable growth in capital available for investment. This trend is especially prominent in emerging markets, where financial institutions are witnessing a surge in demand for investment services. For instance, the Assets Under Management (AUM) under India’s National Pension System (NPS) and Atal Pension Yojana (APY) crossed Rs. 10 lakh crore, reflecting the growing wealth among Indian citizens. More individuals are seeking to augment their wealth through financial markets. Additionally, the institutional sector, which includes entities like pension funds, insurance companies, and endowments, continues to significantly boost AUM growth due to their substantial investment needs.
Technological Advancements in Financial Services
Another significant catalyst for AUM growth is the technological advancements in financial services. Fintech innovations have democratized access to investment markets, enabling a wider range of investors to participate. Digital platforms now provide users with access to sophisticated investment tools and information that were previously exclusive to professional investors. Moreover, the integration of artificial intelligence and machine learning has enhanced the efficiency and effectiveness of investment strategies, allowing asset managers to offer more competitive and appealing investment options, thus attracting more AUM.
Assets Under Management (AUM): Drivers of Market Diversification and Investor Participation
The AUM market is experiencing a transformative shift, characterized by diversification into new asset classes and increased participation from both retail and institutional investors. The post-COVID-19 economic recovery has spurred interest in alternative investments, such as cryptocurrencies and commodities, broadening the scope and appeal of the investment landscape. Furthermore, historically low interest rates have redirected capital from traditional deposits to more lucrative equity markets, enhancing capital growth and market appreciation.
Market conditions and investment strategies
Market conditions, particularly economic uncertainties, have also played a significant role in shaping the AUM market. During the early stages of the COVID-19 pandemic, reduced asset valuations presented lucrative opportunities for institutional investors, who anticipated gains from a market rebound. In response to ongoing market volatility, investors have adopted strategic investment management practices, including tactical asset allocation and hedging strategies. These approaches help diversify investment portfolios geographically and across different asset types, effectively managing risk and leveraging opportunities in fluctuating market conditions.
Enhancing Fund Attractiveness
Strategies to enhance the attractiveness of investment funds are crucial to driving AUM growth. Fund managers are increasingly focusing on portfolio diversification, aggressive marketing, and performance-based incentives to attract and retain investors. Competitive fee structures are also essential in drawing a broader investor base, ensuring growth and sustainability in the AUM market.
Growth and expansion tactics
Furthermore, tactics aimed at growth and expansion, such as acquiring new clients and managing additional assets, play a pivotal role. Through strategic acquisitions and expanding their client base, fund managers are able to significantly increase the overall volume of assets under management, cementing their presence and influence in the global market. This comprehensive approach ensures that the AUM market not only adapts to current economic and market challenges but also positions itself for future growth and resilience.
Key Market Restraints
Regulatory and Compliance Pressures
One of the most significant challenges in the AUM market is the increasing regulatory scrutiny and compliance requirements. Financial markets around the world are subject to evolving regulations aimed at ensuring transparency, protecting investors, and preventing financial crimes such as money laundering and fraud. For asset managers, adapting to these regulations requires significant investments in compliance programs and systems, which can increase operational costs and complexity.
Technological Disruptions
As the financial sector continues to integrate advanced technologies, asset managers must keep pace with these changes to remain competitive. The rise of fintech and digital investment platforms has transformed traditional investment strategies, requiring existing asset managers to innovate continually. However, implementing these technologies-such as artificial intelligence, big data analytics, and blockchain-demands substantial capital investment and expertise, posing a barrier particularly for smaller firms.
Market Volatility and Economic Uncertainty
Market volatility remains a perennial challenge in the AUM market. Economic uncertainties, such as those triggered by geopolitical tensions, pandemics, or financial crises, can lead to sudden and severe market fluctuations. These conditions affect asset valuations and can prompt rapid shifts in investor behavior, making it difficult for asset managers to maintain stable growth and meet investment objectives.
Competition and Fee Pressure
The AUM industry is highly competitive, with numerous firms vying for the same pool of investors. This competition has led to fee compression, as firms lower their fees to attract and retain clients. While reduced fees can benefit investors, they also squeeze profit margins for asset managers, challenging their ability to deliver high-quality services and maintain profitability.
Client Retention and Acquisition
Retaining and acquiring clients in a competitive and evolving market is another significant challenge. Investors are increasingly expecting personalized services and better returns on their investments. Asset managers must develop more client-centric models and innovative offerings to meet these expectations and differentiate themselves from competitors. Additionally, the generational transfer of wealth and the rise of socially responsible and impact investing are reshaping client demands, requiring asset managers to adapt their strategies accordingly.
Environmental, Social, and Governance (ESG) Integration
The growing emphasis on environmental, social, and governance (ESG) factors presents both a challenge and an opportunity. Investors are increasingly prioritizing sustainable and ethical investment options, prompting asset managers to integrate ESG criteria into their investment processes. However, developing expertise in ESG, along with the necessary reporting and compliance, can be complex and resource-intensive.
Market Opportunities
- Emerging Markets Expansion: As wealth grows in developing regions, there is substantial potential for asset managers to tap into new client bases.
- ESG Investments: With rising awareness of environmental, social, and governance (ESG) issues, investors are increasingly favoring sustainable investments.
- Technological Integration: Incorporating advanced technologies like blockchain and AI can enhance portfolio management and client engagement.
- Retirement Solutions: Developing tailored retirement products to cater to the aging population in developed markets.
- Alternative Investments: Diversifying offerings to include real estate, private equity, and commodities can attract investors seeking higher returns.
- Customization and Personalization: Offering bespoke investment solutions that cater to individual investment profiles.
- Global Collaborations: Forming strategic alliances with global partners to facilitate cross-border investment opportunities.
Market Segmentations:
By Traditional Asset Management
- Mutual Funds
- Pension Funds
- Insurance Companies
- Banks and Wealth Managers
By Alternative Investments
- Hedge Funds
- Private Equity
- Venture Capital
- Real Estate
By Regional
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Top Leading Players
Some of the top players in the AUM market include:
- BlackRock
- Vanguard Group
- Fidelity Investments
- P. Morgan Asset Management
- UBS Asset Management
- State Street Global Advisors (SSGA)
- PIMCO
- The Vanguard Group
- Capital Group
- Goldman Sachs Asset Management
- Northern Trust Asset Management
- Morgan Stanley Investment Management
- BNY Mellon Investment Management
- Invesco
- Schroders
These firms are distinguished by their large scale, global presence, and comprehensive service offerings ranging from mutual funds to personalized wealth management and institutional consulting. The competitive landscape is marked by intense competition, innovation, and an ongoing struggle to retain and grow client assets.
Competitive Landscape
The AUM market is fiercely competitive, with firms vying for market share through product innovation, customer service excellence, and strategic mergers and acquisitions. The rise of fintech and digital-only investment platforms has intensified competition, pushing traditional asset managers to evolve digitally and personalize their offerings. Competitive strategies also include expanding into less saturated markets and developing niche products that meet specific investor needs.
Recent Developments:
- BlackRock reported record assets under management (AUM) of about $10.5 trillion as of Q1 2024. This is a significant increase from the second quarter of 2023, where the AUM was around $10 trillion.
- Vanguard’s total assets under management (AUM) increased more than eightfold in the roughly two decades since 2005, reaching a value of $8.6 trillion as of 2024.
- As of the end of 2023, Fidelity Investments had assets under administration of $12.6 trillion, including discretionary assets of $4.9 trillion.
- P. Morgan’s asset and wealth management business ended 2023 with $3.4 trillion in assets under management, up 24%, or $656 billion, on the back of market-related gains and net inflows, primarily to liquidity products.
- UBS Asset Management’s ETF assets under management have increased from around USD 30 billion five years ago to USD 100 billion today. The total assets held by UBS now rest at 9.9 trillion U.S. dollars.
- State Street Global Advisors had $2.81 trillion in assets under management as of March 31, 2023, up 11.7% from three months earlier and 2.8% higher than a year earlier. As of the end of 2023, they reported an AUM of $3.5 trillion.
Regional Analysis
North America
North America, particularly the United States, dominates the global AUM market due to its large number of high-net-worth individuals, sophisticated institutional investors, and a well-established financial services sector. The region benefits from advanced technological infrastructure, which enables innovative investment services and products. However, it also faces challenges such as regulatory complexities and intense competition among asset managers.
Europe
Europe's AUM market is characterized by a strong presence of diverse investment products and a robust regulatory framework shaped by directives such as MiFID II and GDPR. The region's focus on sustainable and responsible investments is growing, driven by both regulatory pressures and investor demand. European asset managers are increasingly incorporating ESG factors into their investment strategies, reflecting the shift towards sustainability.
Asia-Pacific
The Asia-Pacific region is witnessing rapid growth in AUM due to economic growth, rising wealth levels, and increasing financial literacy among its population. Countries like China and India are emerging as major players in the AUM space, with their expanding middle classes showing a growing interest in investment products. The region offers significant growth opportunities, although it also presents challenges due to diverse regulatory environments and cultural differences in investment practices.
Latin America
Latin America's AUM market is evolving, with increased activity in mutual funds and pension funds. Economic volatility and political instability in some countries pose risks, but these are counterbalanced by the high interest rates that attract investors seeking higher returns. The market is gradually maturing, with improvements in regulatory frameworks and greater transparency enhancing investor confidence.
Middle East and Africa
The AUM market in the Middle East and Africa is smaller but growing, driven by the accumulation of wealth in Gulf countries and South Africa. The market is benefiting from infrastructural investments and regulatory reforms aimed at attracting foreign investment. However, the region faces challenges such as political instability and underdeveloped financial markets in many areas.
Each region's AUM market is shaped by its unique economic, regulatory, and demographic factors. Asset managers looking to expand globally must navigate these regional nuances carefully to tailor their strategies effectively and capitalize on local opportunities.
Future Outlook
- Greater Focus on ESG: ESG factors will become a core part of investment strategies.
- Technological Advancements: Ongoing innovation in AI and data analytics will drive further efficiencies in asset management.
- Expansion into New Markets: Asset managers will look to establish a presence in emerging economies.
- Increased Regulatory Scrutiny: Firms will need to adapt to tighter regulatory environments globally.
- More Sophisticated Investor Tools: Tools that offer deeper insights and predictive capabilities will become standard.
- Rising Demand for Customization: The demand for personalized investment strategies will continue to grow.
- Integration of Non-Traditional Assets: Including digital assets like cryptocurrencies in mainstream portfolios.
- Demographic Shifts: Adapting to the changing needs of an aging population in developed markets.
- Global Economic Shifts: Adapting strategies to cope with global economic changes and crises.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Economic Growth and Wealth Accumulation
Rising income levels and expanding economies, especially in emerging markets, are increasing the pool of investable assets, driving demand for asset management services and boosting overall AUM.
Technological Advancements in Financial Services
Innovations such as digital investment platforms, robo-advisors, and AI-driven portfolio management have democratized access to investment products, attracting a broader client base and increasing assets managed.
Market Diversification and Investor Participation
The shift towards alternative investments and the inclusion of new asset classes like cryptocurrencies and commodities are broadening the investment landscape, drawing in both retail and institutional investors and expanding total AUM.
Demographic Shifts and Retirement Planning
Aging populations in developed markets are fueling demand for retirement savings products and wealth management services, leading to greater inflows into managed assets.
Regulatory Developments and Market Access
Evolving regulations in various regions are opening new channels for investment and increasing transparency, which enhances investor confidence and encourages greater participation in managed investment products.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the AUM market from 2023 to 2032?
What factors are contributing to the growth of the AUM market?
How has the AUM market adapted to recent global economic challenges, such as the COVID-19 pandemic?
How are asset managers in the AUM market responding to increased competition and changing investor needs?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Alternative Investments
- 1.2.1 Hedge Funds
- 1.2.2 Private Equity
- 1.2.3 Venture Capital
- 1.2.4 Real Estate
- 1.3 By Traditional Asset Management
- 1.3.1 Mutual Funds
- 1.3.2 Pension Funds
- 1.3.3 Insurance Companies
- 1.3.4 Banks and Wealth Managers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 126,987.45 billion → 2032: USD 205,604.65 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Assets Under Management (AUM) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Assets Under Management (AUM) Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Assets Under Management (AUM) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Assets Under Management (AUM) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Assets Under Management (AUM) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Assets Under Management (AUM) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Assets Under Management (AUM) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Assets Under Management (AUM) Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 126,987.45 billion → 2032: USD 205,604.65 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Assets Under Management (AUM) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Alternative Investments - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Base-Year Market Share, 2023
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Hedge Funds
- 12.3.6.2 Private Equity
- 12.3.6.3 Venture Capital
- 12.3.6.4 Real Estate
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Traditional Asset Management - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Base-Year Market Share, 2023
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Mutual Funds
- 12.4.6.2 Pension Funds
- 12.4.6.3 Insurance Companies
- 12.4.6.4 Banks and Wealth Managers
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Assets Under Management (AUM) Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Assets Under Management (AUM) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2023-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Assets Under Management (AUM) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 BlackRock
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Vanguard Group
- 17.4 Fidelity Investments
- 17.5 J.P. Morgan Asset Management
- 17.6 UBS Asset Management
- 17.7 State Street Global Advisors
- 17.8 PIMCO
- 17.9 Capital Group
- 17.10 Goldman Sachs Asset Management
- 17.11 Invesco
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

