
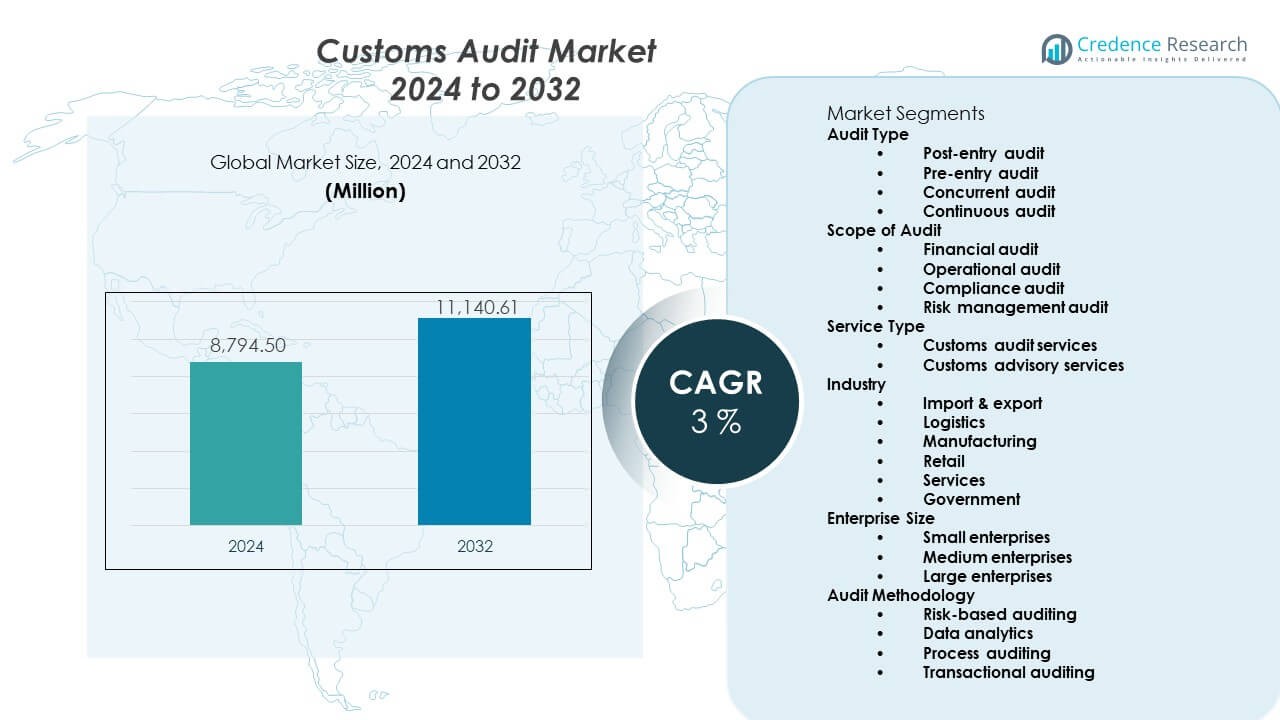
The Customs audit market is projected to grow from USD 8,794.5 million in 2024 to an estimated USD 11,140.61 million by 2032, with a compound annual growth rate (CAGR) of 3% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Customs audit Market Size 2024 | USD 8,794.5 Million |
| Customs audit Market, CAGR | 3% |
| Customs audit Market Size 2032 | USD 11,140.61 Million |
The market expands due to rising enforcement, stricter compliance norms, and growing supply-chain complexity. Audit teams monitor duty payments, classification accuracy, and documentation alignment to avoid disruptions. Traders adopt digital tools that help meet evolving data-submission rules. Governments push automation across customs checkpoints to cut delays. Multinational enterprises use structured audit cycles to improve risk control. Trade agreements drive process revisions that require frequent compliance checks. Technology vendors support teams with AI-based review tools that speed error detection. Strong regulatory pressure keeps adoption high across major industries.
North America leads due to strong digital adoption and mature trade-compliance frameworks. Europe follows with strict regulatory standards and structured customs modernization programs. Asia Pacific emerges as a fast-growing region due to rising cross-border trade and complex tariff structures. China, India, and Southeast Asian countries invest in customs digitalization to reduce processing delays. The Middle East strengthens its position with new free-trade zones and updated compliance rules. Latin America shows steady progress as countries modernize border systems and expand electronic documentation. Africa gains traction through customs reform efforts and improved digital infrastructure.
Market Insights:
- The Customs audit market is valued at USD 8,794.5 million in 2024 and is projected to reach USD 11,140.61 million by 2032, advancing at a 3% CAGR driven by stricter enforcement requirements and expansion of automated audit systems.
- North America holds 34–36%, supported by mature compliance systems; Europe follows with 28–30%, backed by harmonized regulatory frameworks; Asia-Pacific holds 22–24%, driven by rising trade flows and large manufacturing hubs.
- Asia-Pacific is the fastest-growing region with a 22–24% share, expanding due to customs modernization, rising export volumes, and rapid adoption of digital compliance tools.
- The audit type segment is led by post-entry audits with around 40% share, driven by strong demand for duty verification and post-clearance checks across high-volume importers.
- The scope-of-audit segment is dominated by compliance audits holding nearly 35% share, supported by increased regulatory scrutiny and the need to validate classification, valuation, and documentation accuracy.
Market Drivers:
Rising Enforcement Pressure and Stronger Regulatory Alignment
Governments tighten inspection rules that push enterprises to raise compliance efforts across borders. The Customs audit market gains steady demand due to rising documentation checks. Trade groups adopt standard procedures that lower classification errors. Companies use automated review tools that improve data accuracy. Regulators promote structured record-keeping to reduce fraud risk. Audit teams track tariff changes that influence supply-chain decisions. High-risk sectors adopt internal review cycles to maintain control. Digital frameworks support faster verification across global shipments.
- For instance, SAP Global Trade Services (GTS) is used by approximately 1,150 to over 2,000 companies globally and automates classification and compliance checks across thousands of daily cross-border transactions. The exact number of verified companies as of August 2025 is reported to be 943.
Growing Digital Integration Across Audit and Trade Compliance Systems
Digital tools support faster evaluation of customs records and clear workflow steps for teams. The Customs audit market benefits from wider shifts toward automated controls. Enterprises deploy AI-driven systems that highlight risk zones. Analytics tools improve decision quality during review cycles. Electronic documentation helps teams cut manual delays and avoid dispute cases. Governments build digital gateways that streamline border processes. Automation increases visibility across import and export filings. Audit teams use integrated dashboards to monitor compliance gaps in real time.
- For instance, Thomson Reuters ONESOURCE Global Trade, deployed across more than 180 countries, automates customs documentation and supports compliance screening for major multinational importers.
Expansion of Cross-Border Trade and Higher Documentation Volumes
Import growth lifts the need for error-free classification and duty checks across regions. The Customs audit market gains traction due to rising shipment volumes. Traders manage strict timelines that demand clean documentation. Businesses strengthen internal controls to avoid penalties. Review teams evaluate supplier data more closely for accuracy. Global supply chains rely on updated tariff structures to reduce risk. Companies revise audit procedures to meet new compliance demands. Digital filing platforms reduce bottlenecks across review processes.
Stronger Focus on Internal Risk Controls Among Global Enterprises
Large companies adopt structured audit cycles that reduce exposure to penalties. The Customs audit market grows with rising attention on internal governance. Audit groups monitor repeat classification issues that impact cash flow. Firms build compliance training programs for staff handling freight data. Leadership teams push transparency to avoid dispute cases. Importers and exporters adjust processes to meet dynamic regulatory shifts. Digital workflows reduce human error during complex filings. Global enterprises use predictive tools to identify risk trends early.
Market Trends:
Rising Shift Toward Predictive Analytics and Automated Risk Scoring Models
Enterprises deploy predictive tools that help audit teams flag irregularities. The Customs audit market adapts to rapid growth in automated risk scoring. Machine learning supports deeper trend evaluation across trade data. Companies use behavior-based alerts to focus on high-risk shipments. Cloud-based tools enable real-time access to audit outcomes. Governments experiment with AI-driven inspection engines. Audit teams trust automated models to reduce review cycles. Predictive scoring raises efficiency in large-volume environments.
- For instance, IBM Sterling Supply Chain Intelligence Suite uses AI models that analyze millions of supply-chain data points daily, helping enterprises detect anomalies linked to customs and trade-compliance risks.
Growing Adoption of Centralized Audit Management Platforms
Businesses unify customs review systems to avoid fragmented workflows and data silos. The Customs audit market evolves with rising interest in central dashboards. Unified platforms improve tracking of duty payments and tariff updates. Teams use controlled workflows to manage complex record sets. Cloud-based storage increases access for global compliance units. Central audit trails support faster dispute resolution. Vendors expand features to include full lifecycle monitoring. Enterprises depend on consolidated tools to maintain seamless oversight.
- For instance, KPMG operates in more than 143 countries, enabling enterprises to centralize customs audit oversight through globally aligned trade-compliance frameworks supported by a unified advisory network.
Expansion of Trade Automation Ecosystems and Digital Gateways
Governments upgrade border systems that integrate customs filing with real-time validation. The Customs audit market responds to stronger digitization across trade routes. Automated gateways cut clearance delays and reduce manual checks. Importers adopt structured data standards that lower document risks. Blockchain pilots support tamper-proof verification for sensitive goods. Cloud APIs support faster integration with enterprise systems. End-users gain better transparency through shared digital channels. Automated review stages shrink error rates across high-volume operations.
Growing Focus on Compliance Intelligence and Continuous Monitoring Cycles
Compliance units deploy intelligence tools that reveal early gaps in filing accuracy. The Customs audit market sees strong interest in continuous monitoring systems. Enterprises rely on rule-based engines to prevent classification errors. Dashboards offer real-time updates on changing regulatory rules. Teams evaluate supplier behavior to identify recurring risks. New monitoring models support faster documentation audits. Global traders integrate smart alerts into daily workflows. Businesses gain resilience through structured oversight tools.
Market Challenges Analysis
High Regulatory Complexity and Limited Standardization Across Global Trade Systems
Trade environments vary across regions, which increases compliance challenges for global companies. The Customs audit market faces hurdles due to frequent rule changes. Audit teams struggle to interpret new tariff schedules with limited notice. Variations in documentation formats slow verification cycles. Businesses face difficulty maintaining uniform internal procedures. Lack of standard digital adoption across borders raises review delays. Enterprises deal with repeated updates that demand constant training. Regulators introduce new rules that stretch internal audit resources.
Rising Skill Gaps and Limited Availability of Experienced Audit Professionals
Audit teams face shortages in trained experts who understand complex customs laws. The Customs audit market experiences strain due to growing demand for specialized skills. Companies deal with longer review cycles when talent gaps widen. Training programs require continuous updates to match new regulations. Many regions lack advanced compliance education that supports workforce needs. Teams struggle to manage large datasets without strong analytical expertise. Enterprises invest more to retain qualified professionals. Skill gaps slow improvement in audit efficiency across global markets.
Market Opportunities
Expansion of Digital Ecosystems and Adoption of AI-Powered Audit Solutions
Technology vendors launch advanced tools that automate classification and documentation checks. The Customs audit market gains opportunity from rising interest in predictive systems. AI engines help teams reduce manual review pressure. Cloud models expand access for global compliance units. Digital records support smoother integration with customs gateways. Enterprises upgrade infrastructure to meet regulatory digitalization. Predictive analytics helps traders avoid costly errors. Automation lifts accuracy across high-volume audits.
Rising Demand for Third-Party Compliance Services Across Global Trade Networks
Businesses outsource audit functions to reduce workload and gain expert support. The Customs audit market benefits from wider acceptance of managed services. Third-party firms offer deeper knowledge across regional rules. Enterprises focus on core operations while partners manage risk-heavy tasks. Outsourcing improves turnaround time for detailed reviews. Provider networks expand coverage across new trade routes. Demand rises in emerging markets with limited internal expertise. Managed services strengthen compliance resilience for global companies.
Market Segmentation Analysis:
Audit Type
The Customs audit market covers post-entry, pre-entry, concurrent, and continuous audits that support structured compliance across global trade operations. Post-entry audits verify duty accuracy after clearance. Pre-entry checks help reduce filing errors before shipment release. Concurrent audits track real-time movements to limit classification issues. Continuous audits support automated oversight for high-volume traders. Each audit type helps importers and exporters maintain stronger governance.
- For instance, EY’s global trade team operates across more than 150 countries, supporting companies with continuous audit and classification reviews aligned with multi-jurisdiction trade regulations.
Scope of Audit
Financial, operational, compliance, and risk management audits shape review depth across supply chains. Financial audits verify duty payments and valuation accuracy. Operational audits focus on workflow stability. Compliance audits measure alignment with regulatory rules. Risk management audits identify vulnerabilities in complex documentation cycles. This scope helps companies strengthen transparency.
- For instance, Deloitte’s Global Trade Advisory practice, operating across more than 150 countries, conducts financial, operational, and compliance audits for multinational importers under harmonized global review structures.
Service Type
Customs audit services and customs advisory services guide traders through evolving regulatory demands. Service teams support document checks, record validation, and strategic planning. Advisory units help enterprises redesign internal controls and avoid penalties. It gains value from rising complexity in multi-country operations.
Industry
Import and export groups lead adoption due to strict documentation needs. Logistics and manufacturing follow with high shipment volumes. Retail and service sectors adopt structured audits for smoother clearance cycles. Government agencies use audit programs to validate trade data quality.
Enterprise Size
Small, medium, and large enterprises deploy audit models that match their risk exposure. Large firms use integrated systems, while smaller firms rely on external support to manage complex checks.
Audit Methodology
Risk-based auditing, data analytics, process auditing, and transactional auditing help teams increase accuracy. Digital review tools highlight errors early. Structured methods lift reliability across audit stages.
Segmentation:
Audit Type
- Post-entry audit
- Pre-entry audit
- Concurrent audit
- Continuous audit
Scope of Audit
- Financial audit
- Operational audit
- Compliance audit
- Risk management audit
Service Type
- Customs audit services
- Customs advisory services
Industry
- Import & export
- Logistics
- Manufacturing
- Retail
- Services
- Government
Enterprise Size
- Small enterprises
- Medium enterprises
- Large enterprises
Audit Methodology
- Risk-based auditing
- Data analytics
- Process auditing
- Transactional auditing
Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the Customs audit market with around 34–36% due to strong regulatory oversight and high digital adoption across trade operations. The region benefits from advanced compliance frameworks that guide importers and exporters through complex documentation rules. Audit teams use structured digital tools that reduce classification errors and improve workflow efficiency. Large enterprises deploy integrated audit platforms to manage growing data volumes. Government agencies enforce strict customs procedures that increase demand for professional audit support. The market grows as traders expand cross-border flows with Canada and Mexico. It maintains leadership due to mature compliance culture and strong advisory presence.
Europe
Europe accounts for 28–30% share of the Customs audit market, supported by harmonized customs rules and high regulatory transparency. Companies operate under regional frameworks that demand detailed record-keeping and periodic audit cycles. Enterprises rely on advisory teams to manage complex VAT, duty, and classification obligations. It gains steady traction due to rising digitalization efforts under customs modernization programs. Manufacturing and logistics sectors drive strong adoption across high-volume trade corridors. Cross-border movements within the EU create a consistent need for structured verification processes. Audit service providers expand operations to meet demand from both regional and extra-EU traders.
Asia-Pacific
Asia-Pacific holds 22–24% share and remains the fastest-growing region due to expanding trade networks and complex tariff structures. Rapid industrial growth raises the need for structured audit systems across import and export operations. Enterprises face diverse regulatory environments that demand strong compliance management. The Customs audit market strengthens in the region due to rising adoption of automated filing and data analytics tools. It gains momentum as countries upgrade customs digital platforms to reduce clearance delays. Small and medium enterprises seek advisory support to manage new documentation standards. Growth accelerates in China, India, and Southeast Asia due to rising shipment volumes and supply-chain diversification.
Key Player Analysis:
- Deloitte Touche Tohmatsu Ltd.
- KPMG International Ltd.
- Ernst & Young Global Ltd. (EY)
- PricewaterhouseCoopers LLP (PwC)
- BDO International Ltd.
- Grant Thornton International Ltd.
- Baker Tilly International Ltd.
- Crowe LLP
- Mazars
- RSM International
- AlixPartners
- FTI Consulting
Competitive Analysis:
The Customs audit market features strong competition among global consulting firms, specialized audit providers, and technology-driven compliance platforms. Large firms expand service depth through integrated audit, advisory, and analytics solutions. The Customs audit market benefits from high domain expertise offered by leading players that support complex multi-country operations. It faces growing digital disruption as vendors introduce automated review engines and risk-scoring systems. Firms invest in AI tools to improve accuracy and shorten review cycles. Mid-size providers gain traction by offering niche audit capabilities and flexible service models. The competitive landscape remains dynamic as companies target regulated and high-volume trade sectors.
Recent Developments:
- In November 2025, PwC Ukraine's Customs Regulation and International Trade team hosted business meetings to discuss key issues arising from amendments to Ukraine's Customs Code. These changes have significantly impacted companies operating under various customs regimes, and PwC provided practical guidance on compliance assessments and effective use of authorisations to simplify customs procedures.
- In September 2025, Deloitte announced an expanded multi-year co-innovation agreement with HundredX Inc., a data and predictive insights company. This exclusive partnership is designed to deliver actionable, predictive insights that help C-suite leaders across industries reshape business strategy and drive stronger financial performance. The collaboration combines Deloitte's Converge platforms with HundredX's predictive analytics to provide real-time market intelligence.
- In September 2025, PwC US launched Data PRO and Acquisition Hub, two integrated AI audit tools that represent significant innovations in the firm's 2025 audit experience. These tools automate data collection and preparation processes, making audit data gathering easier for clients and audit teams. The advancement reflects PwC's ongoing multi-year audit transformation, combining advanced technology with deep industry knowledge.
- In August 2025, the U.S. Department of Justice, in coordination with the Department of Homeland Security, announced the creation of a Trade Fraud Task Force to increase enforcement against customs violations. PwC has been actively advising clients on compliance requirements and risk management strategies in response to this heightened enforcement environment, which targets duty evasion, smuggling, and other illicit trade activities.
Report Coverage:
The research report offers an in-depth analysis based on Audit Type and Scope of Audit. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing digital audit platforms will expand automation across high-volume trade operations.
- AI-driven risk scoring will strengthen early detection of classification errors.
- Advisory services will gain demand from SMEs with limited internal compliance teams.
- Cloud-based audit tools will improve cross-border document visibility.
- Data-driven audit methodologies will replace manual verification cycles.
- Regulatory tightening will increase adoption of continuous audit frameworks.
- Enterprise-wide compliance integration will create steady growth opportunities.
- Regional modernization programs will shape new digital filing standards.
- Outsourced audit models will rise in markets facing talent shortages.
- Advanced analytics will guide proactive customs audit planning for global traders.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Enforcement Pressure and Regulatory Alignment
Governments are tightening inspection rules and increasing documentation checks, compelling enterprises to enhance compliance efforts and driving demand for customs audit services to avoid penalties and disruptions.
Growing Digital Integration and Automation
The adoption of digital tools, AI-driven systems, and automated audit platforms enables faster, more accurate customs record evaluation and compliance monitoring, making audits more efficient and increasing market adoption.
Expansion of Cross-Border Trade and Documentation Volumes
Increasing global trade volumes and complex tariff structures require more frequent and thorough customs audits to ensure error-free classification and duty checks, fueling market growth.
Stronger Focus on Internal Risk Controls
Large enterprises are implementing structured audit cycles and predictive analytics to proactively manage compliance risks, reduce exposure to penalties, and maintain control over complex, multi-jurisdictional trade operations.
Demand for Third-Party Compliance Services
As regulatory complexity rises and internal expertise becomes scarce, businesses are increasingly outsourcing customs audit and advisory functions to specialized providers, expanding the market for managed compliance services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Customs audit market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Customs audit market projected to grow between 2024 and 2032?
Which Customs audit market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Customs audit market?
Who are the leading companies in the Customs audit market?
Which region commanded the largest share of the Customs audit market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Industry
- 1.2.1 Import & export
- 1.2.2 Logistics
- 1.2.3 Manufacturing
- 1.2.4 Retail
- 1.2.5 Services
- 1.2.6 Government
- 1.3 By Audit Type
- 1.3.1 Post-entry audit
- 1.3.2 Pre-entry audit
- 1.3.3 Concurrent audit
- 1.3.4 Continuous audit
- 1.4 By Service Type
- 1.4.1 Customs audit services
- 1.4.2 Customs advisory services
- 1.5 By Scope of Audit
- 1.5.1 Financial audit
- 1.5.2 Operational audit
- 1.5.3 Compliance audit
- 1.5.4 Risk management audit
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,794.5 million → 2032: USD 11,140.61 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Customs Audit Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Customs Audit Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Customs Audit Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Customs Audit Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Customs Audit Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Customs Audit Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Customs Audit Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Customs Audit Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,794.5 million → 2032: USD 11,140.61 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Customs Audit Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Industry - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Import & export
- 12.3.6.2 Logistics
- 12.3.6.3 Manufacturing
- 12.3.6.4 Retail
- 12.3.6.5 Services
- 12.3.6.6 Government
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Audit Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Post-entry audit
- 12.4.6.2 Pre-entry audit
- 12.4.6.3 Concurrent audit
- 12.4.6.4 Continuous audit
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Service Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Customs audit services
- 12.5.6.2 Customs advisory services
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Scope of Audit - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Financial audit
- 12.6.6.2 Operational audit
- 12.6.6.3 Compliance audit
- 12.6.6.4 Risk management audit
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Customs Audit End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Customs Audit Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Customs Audit Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Customs Audit Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Deloitte Touche Tohmatsu Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 KPMG International Ltd.
- 18.4 Ernst & Young Global Ltd. (EY)
- 18.5 PricewaterhouseCoopers LLP (PwC)
- 18.6 BDO International Ltd.
- 18.7 Grant Thornton International Ltd.
- 18.8 Baker Tilly International Ltd.
- 18.9 Crowe LLP
- 18.10 Mazars
- 18.11 RSM International
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

