
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Augmented And Virtual Reality In Education Market Size 2024 | USD 20102.25 Million |
| Augmented And Virtual Reality In Education Market, CAGR | 16.4% |
| Augmented And Virtual Reality In Education Market Size 2032 | USD 67743.63 Million |
Market Overview
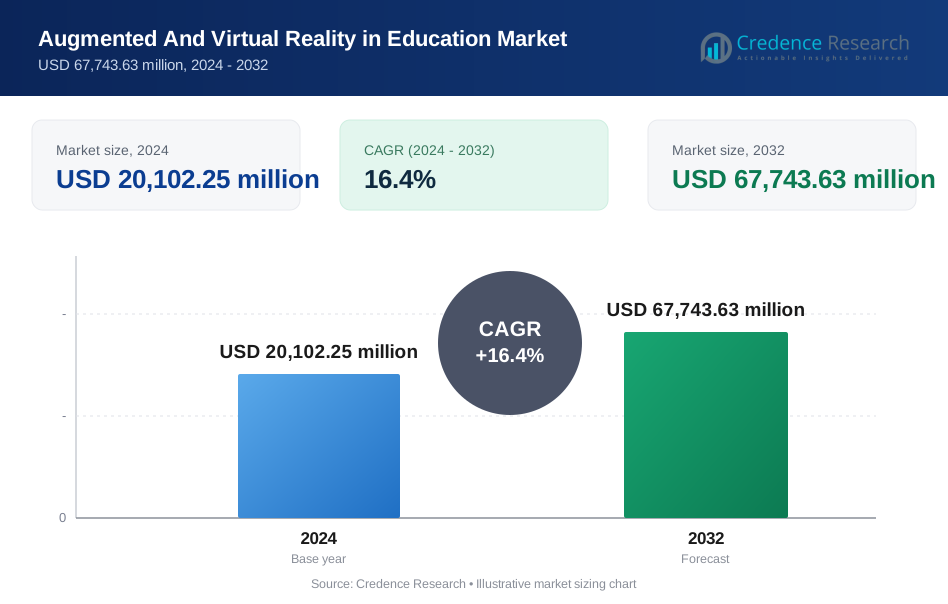
The Augmented And Virtual Reality In Education Market is projected to grow from USD 20102.25 million in 2024 to an estimated USD 67743.63 million by 2032, with a compound annual growth rate (CAGR) of 16.4% from 2024 to 2032.
Key drivers of augmented and virtual reality in the education market include the increasing demand for interactive and immersive learning experiences. Educational institutions are adopting AR and VR technologies to enhance student engagement, improve learning outcomes, and provide real-world simulations that are otherwise difficult to achieve in traditional classroom settings. Moreover, the growing popularity of remote learning and digital education solutions is accelerating the integration of AR and VR tools into educational curriculums. Technological advancements in AR and VR hardware and software are also contributing to the market's growth, with more affordable and accessible devices becoming available. The rise of 5G connectivity is expected to further enhance the potential of AR and VR applications in education by enabling high-speed, low-latency experiences. Additionally, partnerships between tech companies and educational institutions are driving innovation and the development of customized AR and VR solutions tailored to specific learning needs.
Regionally, North America and Europe are leading the augmented and virtual reality in the education market, supported by high technological adoption rates and strong investments in educational technology. In Asia Pacific, countries like China, India, and Japan are anticipated to experience significant growth, driven by the rapid adoption of digital learning solutions, large student populations, and increasing government initiatives to modernize education. Latin America and the Middle East & Africa are also expected to witness growth in the AR and VR education sector as educational institutions in these regions seek to improve learning environments and access to quality education.
Market Insights:
- The AR and VR in education market is projected to grow from USD 20,102.25 million in 2024 to USD 67,743.63 million by 2032, with a CAGR of 16.4%.
- The need for interactive and immersive learning experiences is a key driver, enhancing student engagement and improving educational outcomes.
- The rise of remote learning and digital education solutions is accelerating the integration of AR and VR technologies in schools and universities.
- Innovations in AR and VR hardware, software, and 5G connectivity are enhancing the effectiveness and accessibility of AR/VR in education.
- High initial costs of AR/VR equipment and the lack of skilled educators to implement these technologies may hinder market growth.
- North America and Europe lead the market, with significant investments in educational technology, while Asia Pacific is expected to experience rapid growth due to large student populations and government initiatives.
- Regions like Latin America, the Middle East, and Africa are gradually adopting AR and VR for education, driven by the need for improved learning environments and access to quality education.
Market Drivers:
Increasing Demand for Interactive and Immersive Learning:
The adoption of AR and VR technologies in education is driven by the increasing demand for immersive and interactive learning experiences that engage students more effectively than traditional methods. With AR and VR, students can visualize and experience complex concepts firsthand, leading to deeper understanding and retention of knowledge. According to a 2021 report by the World Bank, countries are incorporating immersive technologies to bridge gaps in education quality, especially in underserved areas. For instance, in 2021, a pilot program in New York City saw a 25% increase in student engagement in middle schools that integrated VR into their history and science curricula. Students used VR to virtually visit historical sites and conduct science experiments in 3D simulations. A similar program in the UK found that VR increased student understanding in medical training, with students reporting a 30% higher retention rate of complex procedures when learned through VR simulations compared to traditional textbook methods.
Government and Institutional Support:
The role of governments and educational institutions in supporting AR and VR integration is a significant driver of market growth. Governments recognize the importance of digital education tools, particularly in addressing educational disparities and enhancing learning outcomes. The European Union, through its Horizon 2020 and Horizon Europe programs, has been investing heavily in educational technology. These initiatives focus on making immersive learning accessible across Europe, with funding directed toward schools and universities adopting AR/VR tools. For instance, the European Commission’s Horizon 2020 program allocated over €80 million for educational technology projects in 2021, including those focused-on AR/VR in classrooms.
Technological Advancements and Decreasing Costs:
Technological advancements, including the reduction in the cost of VR hardware, are driving the adoption of AR/VR in educational institutions. With more cost-effective solutions available, schools can now integrate immersive technologies without incurring prohibitively high expenses. A report by the International Monetary Fund (IMF) revealed that the cost of VR headsets dropped by 35% from 2019 to 2022, largely due to advancements in hardware and competition among key players like Oculus and HTC. For instance, the Oculus Quest 2, which was released in late 2020, priced at around $299, is considered a breakthrough in terms of cost and functionality. Prior to this, high-quality VR systems like the HTC Vive and Oculus Rift were priced above $800, limiting their accessibility. In India, the National Institute of Technology has adopted VR in engineering curricula, reducing the need for physical labs and hands-on training, which saves the institution up to 40% of training costs annually.
Expanding Remote and Hybrid Learning Models:
The COVID-19 pandemic drastically accelerated the shift toward remote and hybrid learning models. This transition has created new opportunities for AR and VR technologies to replace traditional in-person experiences, particularly in fields requiring practical, hands-on learning. As remote education continues to be a long-term trend, AR and VR will play an essential role in facilitating interactive and immersive learning environments. For instance, during the pandemic, Harvard University incorporated VR into its remote learning programs, offering virtual laboratory exercises and interactive field trips to students in 2020.
Market Trends:
Integration of AR/VR into STEM Education:
One of the most prominent trends in the education sector is the growing integration of AR and VR technologies into STEM (Science, Technology, Engineering, and Mathematics) education. These technologies are helping to bridge the gap between theoretical learning and real-world applications, providing students with hands-on experiences that enhance their understanding of complex concepts. Institutions are increasingly adopting AR/VR tools to support STEM programs, such as virtual engineering labs and medical simulations. For instance, the United States Department of Education's Office of Educational Technology released a report in 2021 highlighting the use of immersive technologies in STEM classrooms. This shift is expected to continue as educational institutions recognize the value of AR/VR in improving critical thinking and problem-solving skills among students.
Expansion of Immersive Learning in Remote and Hybrid Environments:
The shift towards remote and hybrid learning environments has created a strong demand for AR and VR solutions that can deliver immersive educational experiences. As schools and universities continue to offer online courses, these technologies are being used to simulate physical classroom interactions, making remote learning more engaging and effective. Virtual reality is providing immersive field trips and laboratory experiences that were previously unavailable in a virtual setting. For instance, in 2021, the World Bank launched a global initiative aimed at providing remote students in developing countries with access to AR/VR tools for virtual field trips and hands-on learning experiences. Countries like Kenya and Indonesia have been utilizing VR to offer biology and history lessons to students, with the intention of scaling these projects to reach over 100,000 students by 2025. This initiative aims to improve the quality of remote education, especially in regions where traditional educational resources are limited.
Growth in Corporate Training and Professional Development:
AR and VR are increasingly being used not only in educational institutions but also in corporate training and professional development programs. Companies are adopting these technologies to provide employees with immersive learning experiences, such as simulations of real-world scenarios and virtual job training. This trend is expected to accelerate as industries look for more effective ways to train and upskill their workforce. For instance, the International Labour Organization (ILO) highlighted in a 2022 report that major corporations in sectors like manufacturing, healthcare, and aviation have started using AR/VR technologies for training purposes. Similarly, the International Air Transport Association (IATA) has partnered with several airlines to provide VR-based training for pilots and cabin crew.
Adoption of AR/VR in Special Education:
A growing trend in the AR and VR market is the adoption of these technologies in special education. AR and VR are increasingly used to support students with disabilities by providing customized learning experiences. These technologies offer a more personalized and inclusive approach to education by helping students with autism, dyslexia, and other learning challenges. For instance, the U.S. Department of Education's Office of Special Education Programs funded a pilot program in 2021 that incorporated VR for students with learning disabilities. The initiative included 15 schools across the U.S., where students used VR to enhance social skills and interact in controlled, immersive environments. According to the program evaluation, students showed improvement in communication skills and emotional regulation after six months of VR usage.
Market Challenges Analysis:
High Initial Costs and Budget Constraints:
One of the most significant challenges in the widespread adoption of augmented reality (AR) and virtual reality (VR) in education is the high initial cost of the required hardware and software. While AR and VR technologies offer substantial benefits in terms of enhancing learning experiences, the upfront investment in AR/VR equipment can be a major barrier for many educational institutions, particularly those in developing countries or with limited budgets. The cost of high-quality VR headsets, specialized software, and necessary infrastructure, such as 5G or high-bandwidth internet connections, can place a heavy financial burden on schools and universities. For instance, in the U.S., while schools have increasingly adopted AR/VR tools, the high cost of VR headsets (ranging from $200 to over $1,000) has restricted full implementation across all educational levels. Moreover, ongoing maintenance costs, updates to software, and training for educators to effectively use AR/VR technologies add further financial pressure on schools.
Lack of Content Development and Standardization:
Another critical challenge is the lack of high-quality, accessible, and standardized content for AR/VR applications in education. For AR/VR to be effective in the classroom, there needs to be a robust library of educational content that is tailored to the curriculum and diverse learning needs. The absence of a universal platform or content standard for AR/VR applications means that educators often have to choose between various solutions that may not be compatible with existing learning management systems or educational tools. This lack of content standardization makes it difficult for educational institutions to create seamless, scalable solutions for integrating AR/VR into their teaching. For instance, the World Bank's 2021 report on digital education technology pointed out that the absence of a cohesive content ecosystem for AR/VR is preventing large-scale adoption in schools worldwide. Many educational institutions face challenges in integrating these technologies into their curriculums because there is no universally accepted or globally available content. Schools are also facing difficulty in tailoring AR/VR experiences to different age groups or educational stages, from primary education to higher education. Additionally, educators often lack the necessary resources to create custom content that suits their students' specific needs, which can hinder the effectiveness of these technologies. As the AR/VR market grows, there will be a need for more collaboration between governments, educational organizations, and content developers to create standardized, high-quality educational content that can be widely adopted across diverse educational systems.
Market Opportunities:
The ongoing shift toward remote and hybrid learning models presents a significant opportunity for AR and VR technologies in education. As more institutions embrace flexible learning environments, the need for immersive, interactive tools that replicate real-world experiences becomes more pronounced. AR and VR offer the potential to bridge the gap between physical and digital learning by enabling virtual field trips, hands-on simulations, and interactive lessons that engage students in ways traditional online learning cannot. This trend is especially crucial in subjects like science, medicine, and engineering, where practical experience is key. With global education systems increasingly investing in digital platforms to support remote learning, the integration of AR/VR into these systems will allow institutions to provide richer educational experiences that cater to diverse student needs. Governments and educational organizations worldwide are allocating significant resources to support the adoption of immersive technologies, further driving growth opportunities in this market.
Beyond traditional education, AR and VR technologies offer significant potential in the professional training and corporate education sector. Companies across industries such as healthcare, manufacturing, and aviation are leveraging immersive technologies to train employees in real-world scenarios without the risk or cost of physical simulations. The ability to create realistic training environments that can replicate complex situations makes AR/VR an invaluable tool for enhancing skills, improving safety, and reducing training costs. As industries continue to recognize the efficiency and effectiveness of AR/VR for upskilling employees, this market segment is expected to grow substantially. The increasing adoption of immersive technologies in corporate learning provides a lucrative opportunity for AR/VR providers to expand their offerings and collaborate with organizations to develop customized training solutions tailored to specific industry needs.
Market Segmentation Analysis:
By Type
The augmented and virtual reality in the education market can be segmented based on the type of technology used, which includes both hardware and software. Hardware-based solutions, such as VR headsets, AR glasses, and sensors, are essential for creating immersive experiences in the educational environment. These devices provide the physical platform for AR/VR applications to interact with students. On the software side, applications and platforms designed for education, such as simulation tools, virtual classrooms, and interactive learning environments, are becoming increasingly popular. The combination of both hardware and software enables institutions to offer a completely immersive learning experience.
By Technology
The technology segment within the AR/VR market for education can be divided into augmented reality (AR) and virtual reality (VR). Augmented reality enhances the real world by overlaying digital information, allowing students to interact with both physical and virtual elements. This is especially beneficial for subjects like history, where students can view 3D models of historical artifacts in real time. Virtual reality, on the other hand, creates a completely immersive environment that students can explore and interact with. VR is used in fields such as medicine, engineering, and arts education, where hands-on, simulated experiences are required.
By End-User
The end-user segment of augmented and virtual reality in the education market includes K-12 schools, higher education institutions, and corporate training organizations. K-12 schools have increasingly adopted AR/VR for subjects like science and math, where visualizing complex concepts can significantly enhance understanding. Higher education institutions, particularly in fields such as medicine, engineering, and architecture, are adopting AR/VR technologies to offer immersive learning experiences that simulate real-world scenarios. Corporate training is also a growing segment, as companies use AR/VR to train employees in various industries like healthcare, manufacturing, and aviation, where practical, hands-on experience is crucial.
Segmentations
Based on Product Type:
- Hardware Solutions • Software Solutions • Content Development Tools
Based on Technology:
- Augmented Reality (AR) • Virtual Reality (VR)
Based on End-User:
- K-12 Schools • Higher Education Institutions • Corporate Training
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is one of the leading regions in the adoption of augmented and virtual reality (AR/VR) technologies in education. The market in this region is driven by significant investments from both public and private sectors, as well as strong technological infrastructure. The United States, in particular, is at the forefront, with various educational institutions incorporating AR/VR solutions for both K-12 education and higher education. The market in Canada is also expanding, supported by educational institutions integrating digital tools and immersive technologies to enhance student engagement and learning outcomes. Furthermore, with the rise of hybrid and remote learning models, especially after the COVID-19 pandemic, AR/VR technologies have gained prominence in delivering interactive and experiential learning, bridging the gap between virtual and physical classroom environments. This trend is expected to continue growing in the coming years, with AR/VR becoming a key component of modern education.
Europe
Europe is another significant market for AR/VR in education, with countries like the United Kingdom, Germany, and Sweden leading the adoption of immersive technologies in academic institutions. Europe’s education sector has increasingly incorporated AR/VR to enhance both teaching methods and student learning outcomes, particularly in higher education and vocational training. The European Union has also shown strong support for digital learning initiatives, funding projects that explore the use of immersive technologies in schools, universities, and training centers. The European market is also supported by a robust content development ecosystem, with many startups and research institutions focusing on creating educational AR/VR content for diverse subjects. The growing trend of hybrid learning models has further accelerated the adoption of these technologies, enabling institutions to provide interactive, hands-on experiences to students regardless of their physical location.
Asia Pacific
Asia Pacific is experiencing rapid growth in the AR/VR in education market, driven by increasing government investments in educational technology and growing demand for digital learning solutions. Countries like China, India, Japan, and South Korea are at the forefront of integrating AR/VR in schools, universities, and corporate training programs. In particular, China and India are expected to witness significant market growth due to the expansion of the digital infrastructure and government-backed initiatives promoting digital education. Japan and South Korea are also significant players, with both countries integrating AR/VR in their education systems, particularly in fields like healthcare, robotics, and engineering. These countries have strong technological infrastructure, and the adoption of AR/VR is seen as a means to enhance practical learning and provide students with real-world simulations. As the demand for personalized, immersive learning experiences grows, the Asia Pacific region is expected to continue its rapid adoption of AR/VR technologies, both in formal education settings and corporate training environments.
Key Player Analysis:
- Google LLC (Alphabet, Inc.) (U.S.)
- EON Reality (U.S.)
- Schell Games (U.S.)
- Avantis Systems Ltd. (U.K.)
- zSpace, Inc. (U.S.)
- VRSim, Inc. (U.S.)
- Veative Group (U.K.)
- Mursion (U.S.)
- Immersion VR (U.K.)
- Unimersiv (U.S.)
- Alchemy Immersive (U.S.)
Competitive Analysis:
The competitive landscape of the Augmented and Virtual Reality (AR/VR) in Education market is rapidly evolving, driven by a mix of established technology companies and specialized education-focused startups. Major players such as Microsoft, Google, and Apple lead the market with their robust hardware solutions, including AR glasses, VR headsets, and development platforms. For instance, Microsoft’s HoloLens and Google’s Cardboard and Expeditions are among the most widely used AR/VR tools in educational settings. Additionally, companies like Sony and HTC are enhancing the VR experience with devices that cater to both education and entertainment sectors. Tech giants are also collaborating with educational institutions to develop tailored solutions that meet specific learning needs, driving market innovation and product differentiation. Alongside these major players, edtech startups are carving out significant market share by developing specialized AR/VR content and platforms. Companies like zSpace, ClassVR, and Nearpod offer immersive learning environments and content development tools focused on enhancing student engagement and experiential learning. Moreover, government initiatives and public-private partnerships are accelerating the development and deployment of AR/VR in education, providing further opportunities for companies to capture a larger share of the market, especially in emerging regions like Asia Pacific, Latin America, and the Middle East.
Recent Developments:
- November 2024, Google introduced an AI-powered feature within its AR/VR education tools to enhance personalized learning experiences. This update integrates generative AI with immersive environments, allowing educators to create tailored content for students based on real-time performance analytics.
- December 2024, EON Reality published a comprehensive white paper titled "Reimagining Indian Education: A Strategic Roadmap for Immersive VR/AR Integration," highlighting how immersive technologies can transform education in India by improving learning outcomes and bridging skill gaps.
- August 2023, EON Reality launched its EON-XR platform in Vietnam, enabling educators to create AR/VR content without coding. The platform includes access to a library of over 6 million educational assets, supporting diverse learning needs from K-12 to vocational training.
- October 2023, Avantis Systems launched an upgraded version of ClassVR, incorporating AI-assisted lesson planning tools to help teachers create customized VR experiences aligned with specific learning objectives.
Market Concentration & Characteristics:
The Augmented and Virtual Reality (AR/VR) in Education market is characterized by a moderate to high concentration, with several large technology companies dominating the landscape alongside a growing number of specialized edtech firms. Major players like Microsoft, Google, Apple, and Sony hold a significant market share, leveraging their established reputations, extensive financial resources, and broad technological expertise. These companies offer comprehensive AR/VR hardware and software solutions and are actively investing in the development of immersive learning tools tailored to various educational sectors. Their focus on product innovation, such as advanced VR headsets (e.g., Microsoft’s HoloLens, Google Cardboard) and AR platforms, positions them as market leaders. However, alongside these industry giants, smaller edtech companies such as zSpace, ClassVR, and Nearpod are gaining traction by offering niche, customizable AR/VR solutions designed for specific educational applications, such as STEM education and virtual field trips. The market is also marked by a strong collaborative ecosystem, where partnerships between educational institutions and technology providers are increasingly common. These collaborations help accelerate the integration of AR/VR into curricula and allow for the co-creation of customized learning experiences.
Report Coverage:
The research report offers an in-depth analysis based on product type, technology and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The adoption of AR and VR in education will continue to grow as institutions seek to enhance student engagement through immersive learning experiences.
- Technological advancements will make AR and VR tools more affordable and accessible, encouraging wider use across various educational levels.
- Increasing demand for remote and hybrid learning solutions will drive further integration of AR/VR technologies into digital education platforms.
- Educational institutions will focus on creating customized learning experiences, utilizing AR/VR to cater to diverse learning styles and needs.
- Governments and educational organizations will invest in research and development to explore innovative uses of AR/VR in curriculum design and teaching methodologies.
- The rise of 5G technology will facilitate faster and more seamless AR/VR experiences, broadening their application in education.
- Collaboration between educational institutions and technology companies will foster the development of tailored AR/VR tools to address specific educational goals.
- As virtual classrooms become more common, AR/VR will play a crucial role in offering real-world simulations and interactive training for students.
- Growth in emerging markets will create new opportunities for AR/VR adoption, driven by the need to modernize education systems and provide equal learning opportunities.
- The increasing focus on STEM (Science, Technology, Engineering, and Mathematics) education will fuel demand for AR/VR tools to aid in complex subject learning and skill development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Interactive and Immersive Learning
Educational institutions are increasingly adopting AR and VR to create engaging, hands-on learning experiences that improve student understanding and retention, especially for complex or abstract subjects.
Expansion of Remote and Hybrid Learning Models
The shift toward remote and hybrid education, accelerated by the COVID-19 pandemic, has driven the need for AR/VR tools that can simulate real-world environments and practical experiences outside the traditional classroom.
Technological Advancements and Cost Reductions
Improvements in AR/VR hardware and software, along with decreasing device costs and the rollout of 5G connectivity, are making immersive technologies more accessible and practical for widespread educational use.
Government and Institutional Support
Government initiatives and funding programs, particularly in regions like the EU and Asia Pacific, are supporting the integration of AR/VR in education to modernize curricula and bridge educational disparities.
Growth in Corporate Training and Professional Development
Corporations are increasingly leveraging AR/VR for employee training and upskilling, driving demand for educational AR/VR solutions beyond traditional academic settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Augmented and Virtual Reality in Education Market?
What are the key drivers of growth in this market?
How does 5G connectivity impact the AR/VR education market?
Which regions are leading the AR/VR in education market?
How are government initiatives influencing the AR/VR education market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 K-12 Schools
- 1.2.2 Higher Education Institutions
- 1.2.3 Corporate Training
- 1.3 By Technology
- 1.3.1 Augmented Reality (AR)
- 1.3.2 Virtual Reality (VR)
- 1.4 By Product Type
- 1.4.1 Hardware Solutions
- 1.4.2 Software Solutions
- 1.4.3 Content Development Tools
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20,102.25 million → 2032: USD 67,743.63 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Augmented And Virtual Reality in Education Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Augmented And Virtual Reality in Education Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Augmented And Virtual Reality in Education Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Augmented And Virtual Reality in Education Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Augmented And Virtual Reality in Education Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Augmented And Virtual Reality in Education Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Augmented And Virtual Reality in Education Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Augmented And Virtual Reality in Education Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20,102.25 million → 2032: USD 67,743.63 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Augmented And Virtual Reality in Education Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 K-12 Schools
- 12.3.7.2 Higher Education Institutions
- 12.3.7.3 Corporate Training
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Augmented Reality (AR)
- 12.4.7.2 Virtual Reality (VR)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hardware Solutions
- 12.5.7.2 Software Solutions
- 12.5.7.3 Content Development Tools
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Augmented And Virtual Reality in Education End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Augmented And Virtual Reality in Education Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Augmented And Virtual Reality in Education Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Augmented And Virtual Reality in Education Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Google LLC (Alphabet, Inc.)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft Corporation
- 18.4 Apple Inc.
- 18.5 EON Reality
- 18.6 Schell Games
- 18.7 Avantis Systems Ltd.
- 18.8 zSpace, Inc.
- 18.9 VRSim, Inc.
- 18.10 Veative Group
- 18.11 Sony Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

