
Market Overview
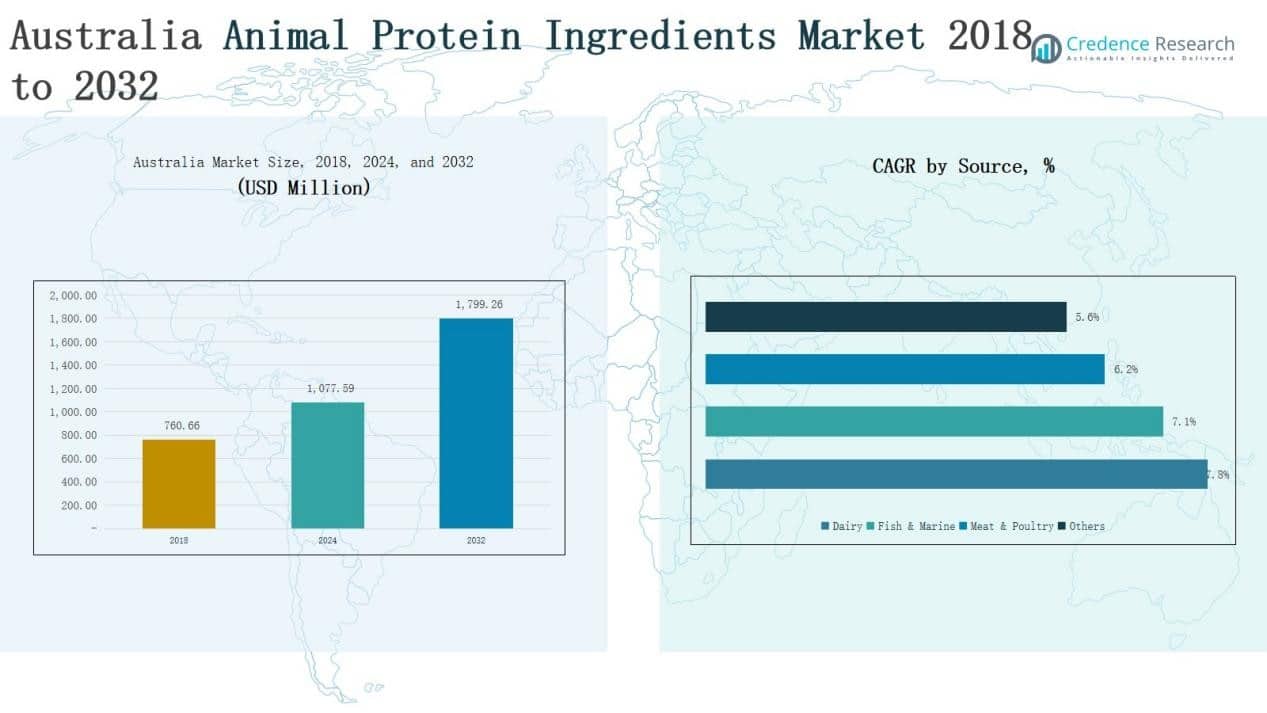
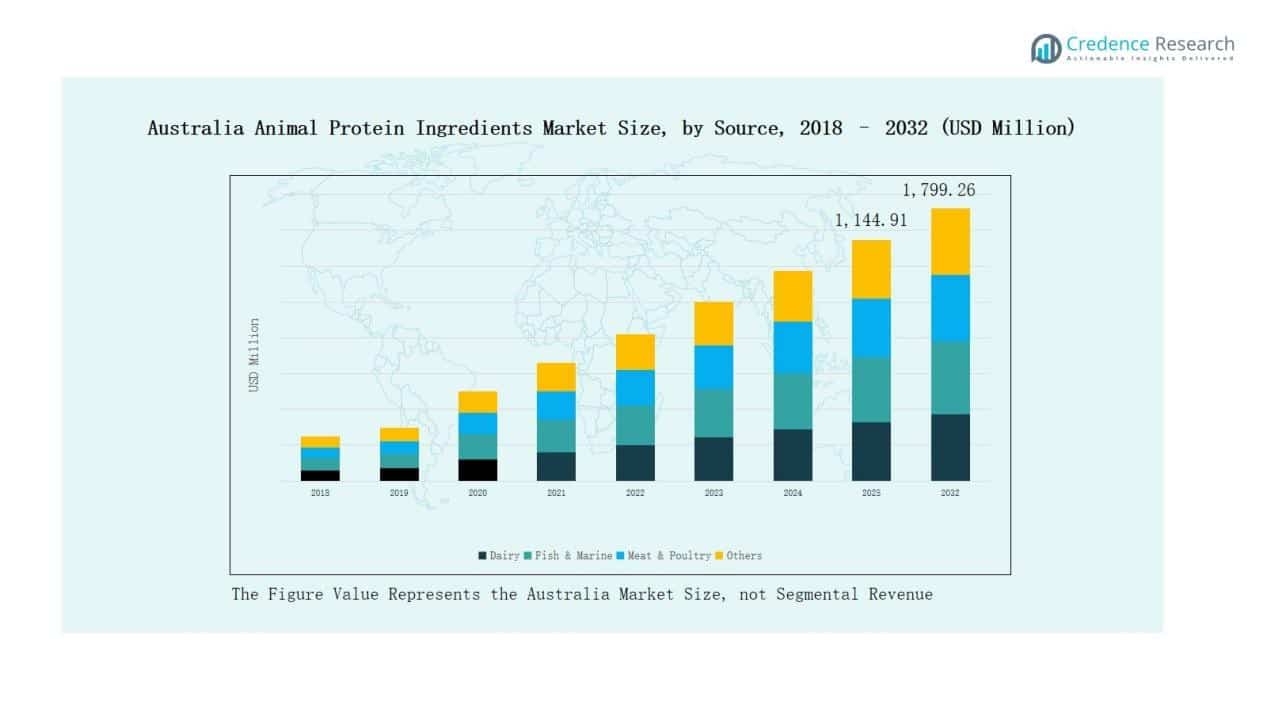
Australia Animal Protein Ingredients Market size was valued at USD 760.66 million in 2018, rising to USD 1,077.59 million in 2024, and is anticipated to reach USD 1,799.26 million by 2032, at a CAGR of 5.42% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Animal Protein Ingredients Market Size 2024 | USD 1,077.59 Million |
| Australia Animal Protein Ingredients Market, CAGR | 5.42% |
| Australia Animal Protein Ingredients Market Size 2032 | USD 1,799.26 Million |
The Australia Animal Protein Ingredients Market is shaped by the presence of leading global and regional companies that focus on diversified product portfolios, innovation, and strong distribution networks. Key players include Cargill, Tyson Foods, Darling Ingredients, Fonterra Co-operative Group Limited, Maxum Foods, ADM Trading Australia, Eurial I&N, Kemin Industries, Prinova, and Armor Proteines, all of which strengthen their positions through clinical nutrition solutions, sports and active nutrition products, and premium pet food offerings. Among regions, New South Wales leads with 32% market share in 2024, supported by its robust food processing base, advanced dairy infrastructure, and strong consumer demand for functional and sports nutrition products. This concentration positions it as the dominant hub for both domestic consumption and exports.
Market Insights
- The Australia Animal Protein Ingredients Market grew from USD 760.66 million in 2018 to USD 1,077.59 million in 2024 and is projected to reach USD 1,799.26 million by 2032, expanding at 5.42% CAGR.
- Dairy leads the source segment with 41z share in 2024, driven by whey and casein demand in sports and clinical nutrition, while fish, meat, and other proteins provide complementary growth.
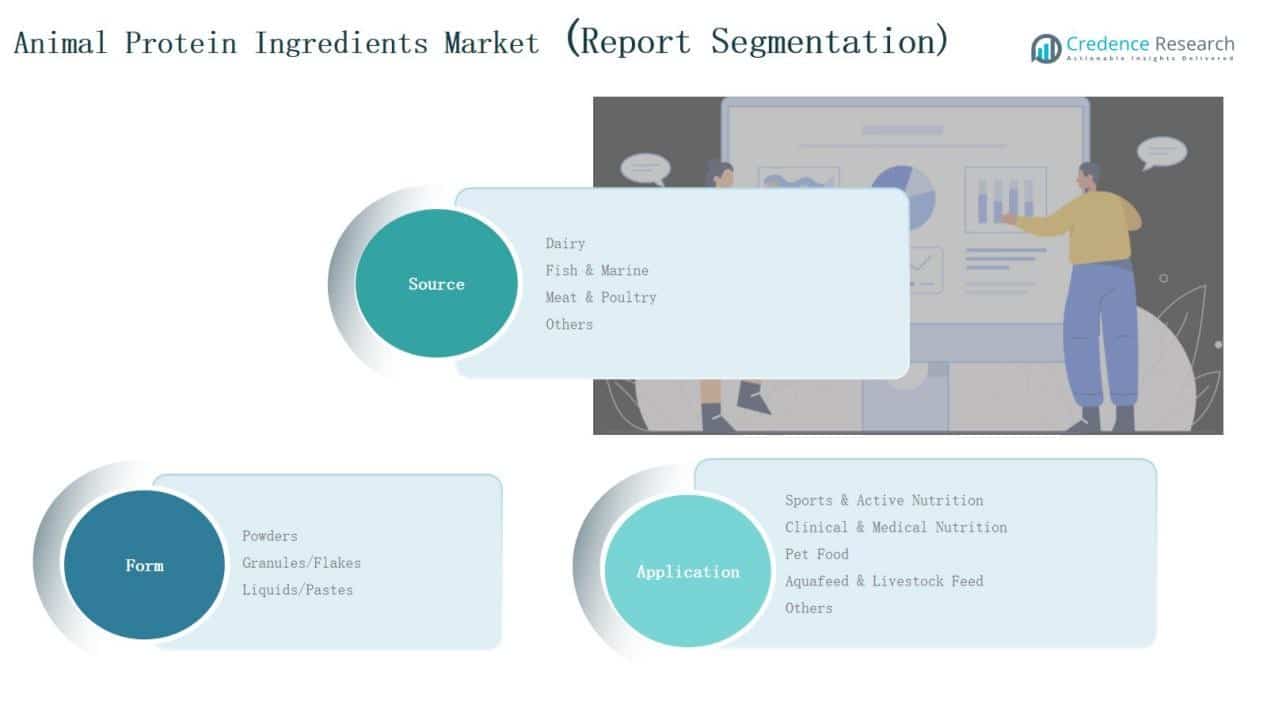
- Powders dominate the form segment with 64% share in 2024, supported by stability, ease of use, and wide applications in supplements, feeds, and medical nutrition products.
- Sports and active nutrition holds the largest application share at 34% in 2024, followed by clinical nutrition and pet food, while aquafeed and others contribute steady demand.
- Regionally, New South Wales leads with 32% share in 2024, followed by Victoria at 28%, Queensland at 21%, Western Australia at 11%, and other regions collectively at 8%.
Market Segment Insights
By Source
Dairy dominates the Australia Animal Protein Ingredients Market, holding around 41% share in 2024. Strong demand for whey and casein proteins in sports nutrition and clinical nutrition drives this dominance. Fish and marine proteins follow, supported by rising interest in collagen and omega-rich applications. Meat and poultry proteins maintain a steady share due to use in functional foods and feed. The “Others” category, including insect proteins, remains niche but shows growth potential from sustainability trends.
- For instance, Arla Foods Ingredients signed a distribution agreement with Alchemy Agencies to supply Nutrilac and Lacprodan branded whey protein isolates to the Australian sports nutrition market.
By Form
Powders account for the largest share, representing about 64% of the market in 2024. Their stability, easy handling, and longer shelf life make powders preferred in sports nutrition, clinical products, and animal feed. Granules and flakes secure a moderate share as they cater to feed and functional food applications. Liquids and pastes remain limited to specialized formulations, but demand is rising for high-value medical nutrition and pet food solutions.
- For instance, FrieslandCampina Ingredients launched Nutri Whey ProHeat, a heat-stable whey protein powder designed for performance nutrition, enabling use in convenient, ready-to-drink beverages.
By Application
Sports and active nutrition emerges as the leading application segment, contributing nearly 34% of the market in 2024. Growing fitness trends and high protein intake among younger consumers fuel this growth. Clinical and medical nutrition follows closely, supported by the aging population and rising focus on dietary supplements. Pet food secures a strong share due to Australia’s high pet ownership levels. Aquafeed and livestock feed remain essential in supporting the agricultural economy, while the “Others” category covers specialty uses in niche food and beverage products.
Key Growth Drivers
Rising Demand for Functional and Sports Nutrition
The Australia Animal Protein Ingredients Market benefits from strong demand for functional and sports nutrition products. Rising health awareness and fitness adoption among younger consumers continue to boost protein-based supplements. Whey and casein proteins remain particularly popular, given their proven benefits for muscle recovery and performance. Increasing availability of protein powders and ready-to-drink beverages across supermarkets and online platforms further expands access. This driver ensures steady consumption growth, especially in urban markets where lifestyle-driven health products dominate.
- For instance, CSIRO launched "Just Meat" red meat protein powder in Australia, offering a nutrient-rich, allergen-free supplement for shakes and energy drinks with a complete amino acid profile
Expanding Clinical and Medical Nutrition Applications
Clinical and medical nutrition is a vital growth driver as protein-enriched products gain importance in elderly and patient care. With Australia’s aging population, demand for specialized nutrition to support muscle maintenance, immune health, and recovery is increasing. Dairy-derived proteins such as casein hydrolysates are widely used in medical formulations. Hospitals, aged care facilities, and pharmacies increasingly rely on protein ingredients in supplements and nutraceuticals. This expanding adoption strengthens the market’s role in healthcare, ensuring steady long-term demand beyond conventional food and beverage applications.
- For instance, Nestlé Health Science launched Novasource Renal protein supplements in Australia to support nutrient needs of patients with chronic kidney disease, reflecting rising clinical adoption.
Growth in Pet Food and Animal Feed Industry
Australia’s high pet ownership rates and strong livestock industry fuel steady demand for animal protein ingredients. Pet food manufacturers rely heavily on meat, poultry, and marine proteins to produce premium and functional pet diets. Simultaneously, the livestock and aquaculture sectors utilize protein-rich feed to improve animal health and productivity. This dual demand stream strengthens market stability and growth. The expansion of branded pet food lines and increased investments in animal husbandry further support rising consumption of diverse protein sources.
Key Trends & Opportunities
Sustainability and Alternative Protein Exploration
Sustainability is shaping opportunities in the Australia Animal Protein Ingredients Market, as companies explore ethical sourcing and eco-friendly practices. Marine collagen and alternative sources like insect-based proteins are gaining research and development attention. Growing consumer demand for traceability and reduced carbon footprint supports premium positioning of responsibly sourced proteins. This trend not only enhances brand value but also opens new market opportunities in functional foods and supplements. Firms investing in sustainable supply chains and alternative ingredients are well-placed for future growth.
- For instance, NiHTEK launched NiHPRO, a hydrolyzed protein isolate for lactose-intolerant consumers, reflecting growing demand for dairy-free and sustainable protein alternatives in the functional foods segment.
Innovation in Protein Processing and Functional Ingredients
Technological advancements in protein extraction and formulation create opportunities for product innovation. Companies are focusing on high-quality hydrolysates, isolates, and blends tailored for specific health benefits. Customized protein solutions for weight management, immune support, and clinical recovery are entering the market. The ability to enhance solubility, flavor, and bioavailability of proteins improves their appeal in both food and healthcare products. These innovations expand application potential across sports nutrition, medical nutrition, and pet care, enabling companies to differentiate portfolios in a competitive market.
- For instance, Friesland Campina Ingredients introduced its Nutri Whey Isolate Clear, a high-protein solution with clean taste and fast digestion, aimed at supporting recovery in clinical and active lifestyle nutrition.
Key Challenges
Price Volatility in Raw Material Supply
Fluctuations in dairy, meat, and marine raw material prices pose a challenge for ingredient manufacturers. Feed costs, seasonal supply variations, and global demand shifts affect input costs significantly. For Australian producers, reliance on imports of certain specialty proteins also raises exposure to international market volatility. Companies often struggle to maintain stable pricing while ensuring profitability. This challenge increases the need for cost optimization strategies and long-term supplier agreements to balance risks and ensure competitive pricing in the domestic market.
Stringent Regulatory and Quality Standards
Compliance with strict food safety, labeling, and nutritional standards remains a key challenge in the Australia Animal Protein Ingredients Market. Authorities enforce stringent testing and documentation, particularly for clinical and pet food applications. Companies must invest in certification and traceability systems to secure consumer trust and regulatory approval. While this ensures product safety, it adds to operational costs and slows product launches. Smaller firms often face higher entry barriers, making it difficult to compete against established multinational players with larger compliance budgets.
Rising Competition from Plant-Based Proteins
The rapid growth of plant-based alternatives challenges the expansion of animal protein ingredients. Consumers seeking sustainable, ethical, and allergen-free options are shifting toward soy, pea, and other plant proteins. Marketing campaigns promoting plant-based diets, combined with environmental and health awareness, intensify this trend in Australia. While animal proteins maintain advantages in functionality and amino acid profiles, competition is pressuring companies to highlight unique benefits. This challenge underscores the need for differentiation and innovation to retain relevance in a diversifying protein market.
Regional Analysis
New South Wales
New South Wales holds the largest share of the Australia Animal Protein Ingredients Market, accounting for 32% in 2024. The state’s strong food processing sector, combined with a high concentration of fitness-oriented consumers, drives protein demand. Dairy proteins dominate, supported by advanced manufacturing facilities. Rising health awareness and preference for sports nutrition strengthen adoption across urban populations. The state also benefits from its strong distribution networks and innovation in clinical nutrition products. It remains a core hub for both domestic consumption and exports of protein ingredients.
Victoria
Victoria represents 28% of the market share in 2024, making it the second-largest region. The state’s dominance in dairy production and processing supports its position in protein ingredients. Companies in Victoria actively supply powders and functional proteins to the sports and medical nutrition industries. Urban demand from Melbourne further boosts product penetration. Pet food and livestock feed also see steady growth, driven by the state’s agricultural base. It maintains strong collaboration between local producers and global firms to expand product offerings.
Queensland
Queensland accounts for 21% of the market share in 2024. Its role as a leading hub for livestock and aquaculture supports high demand for animal protein ingredients. Meat and poultry proteins contribute significantly to the region’s consumption. Expanding pet ownership and rising premium pet food sales further enhance growth prospects. Dairy proteins also see consistent uptake in health supplements and clinical products. The region continues to attract investment in feed and functional protein manufacturing to meet domestic and export needs.
Western Australia
Western Australia holds 11% of the market share in 2024. Its growing aquaculture and fisheries sector drives demand for marine-based proteins. The state is gradually developing its processing base, focusing on exports and specialized nutrition markets. Urban centers contribute through rising demand for health-focused food and beverage applications. Pet food consumption also adds to steady market expansion. While smaller than eastern states, Western Australia benefits from strong resource availability and emerging opportunities in sustainable protein sourcing.
Other Regions
Other regions, including South Australia, Tasmania, and the Northern Territory, collectively hold 8% of the market share in 2024. These markets are smaller but play a role in regional supply chains and niche applications. Dairy and meat proteins see modest demand, largely for local consumption. Growth opportunities lie in aquaculture and specialized feed industries. Consumer demand for functional food products is rising slowly in urban pockets. These regions contribute to the overall balance of production and consumption across the country.
Market Segmentations:
By Source
- Dairy
- Fish & Marine
- Meat & Poultry
- Others
By Form
- Powders
- Granules/Flakes
- Liquids/Pastes
By Application
- Sports & Active Nutrition
- Clinical & Medical Nutrition
- Pet Food
- Aquafeed & Livestock Feed
- Others
By Region
- New South Wales
- Victoria
- Queensland
- Western Australia
- Other Regions
Competitive Landscape
The Australia Animal Protein Ingredients Market features a competitive landscape shaped by global corporations and strong regional players. Multinational leaders such as Cargill, Tyson Foods, and Darling Ingredients maintain their positions through diverse product portfolios, global sourcing capabilities, and investment in innovation. Regional firms, including Maxum Foods, ADM Trading Australia, and Eurial I&N, strengthen market presence by focusing on localized supply chains, dairy specialization, and tailored solutions for sports, clinical, and pet nutrition. Fonterra Co-operative Group Limited holds a significant role, leveraging its dominance in dairy production and advanced processing facilities. Companies actively invest in R&D to improve protein purity, solubility, and functionality, while sustainability initiatives enhance brand value. The competitive environment is further intensified by partnerships, acquisitions, and collaborations aimed at expanding market reach. It continues to evolve as players focus on differentiation through product innovation, compliance with strict regulatory standards, and expansion into premium applications across Australia.
Key Players
- Eurial I&N
- ADM Trading Australia Pty Ltd
- Maxum Foods
- Fonterra Co-operative Group Limited
- Cargill
- Kemin Industries
- Prinova
- Darling Ingredients
- Armor Proteines
- Tyson Foods
- Other Key Players
Recent Developments
- In August 2025, v2food acquired US vegan chicken startup Daring Foods and entered a strategic partnership with Ajinomoto to drive global expansion.
- In March 2025, Australian Plant Proteins (APP) was acquired by My Co., strengthening its financial and operational base.
- In May 2025, Arla Foods Ingredients partnered with Alchemy Agencies for distribution of performance-nutrition proteins across Australia and New Zealand.
- In March 2025, FrieslandCampina Ingredients launched Nutri Whey ProHeat, a heat-stable whey protein solution, in the active nutrition segment targeting ready-to-drink functional beverages.
Report Coverage
The research report offers an in-depth analysis based on Source, Form, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for dairy proteins will remain strong due to sports and clinical nutrition.
- Fish and marine proteins will gain traction with rising interest in collagen and omega-rich products.
- Pet food applications will expand further, driven by premiumization and high pet ownership.
- Clinical nutrition will strengthen as aging populations seek protein-enriched dietary solutions.
- Powder form will continue to dominate, supported by convenience and longer shelf life.
- Sustainability and traceability will become key factors influencing consumer preferences.
- Innovation in protein isolates, hydrolysates, and functional blends will drive product diversification.
- Partnerships between local producers and global firms will increase to enhance distribution.
- Regulatory compliance and quality assurance will remain central to market competitiveness.
- Alternative proteins, including insect-based and marine-derived options, will open new growth opportunities.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Sports and Active Nutrition
Increasing health awareness and fitness trends among younger consumers in Australia are driving demand for high-quality animal protein ingredients, particularly whey and casein, in sports and active nutrition products. The popularity of protein powders and ready-to-drink beverages is expanding access and boosting market growth.
Expansion of Clinical and Medical Nutrition
Australia's aging population and rising focus on dietary supplements are fueling demand for protein-enriched clinical and medical nutrition products. Dairy-derived proteins, especially casein hydrolysates, are widely used in medical formulations to support muscle maintenance, immune health, and recovery.
Premiumization and Growth in Pet Food
High pet ownership rates and consumer willingness to spend on premium and functional pet food are increasing the use of animal protein ingredients in pet nutrition. Manufacturers are innovating with meat, poultry, and marine proteins to meet demand for high-quality, health-focused pet diets.
Innovation and Diversification in Protein Processing
Technological advancements in protein extraction and formulation are enabling the development of high-quality hydrolysates, isolates, and functional blends. These innovations are expanding the application of animal protein ingredients across sports, clinical, and pet nutrition, supporting product differentiation and market expansion.
Sustainability and Alternative Protein Exploration
Growing consumer demand for traceability, ethical sourcing, and reduced carbon footprint is encouraging companies to invest in sustainable supply chains and alternative protein sources such as marine collagen and insect proteins. This trend is opening new market opportunities and enhancing brand value.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Australia Animal Protein Ingredients Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Australia Animal Protein Ingredients Market projected to grow between 2025 and 2032?
Which Australia Animal Protein Ingredients Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Australia Animal Protein Ingredients Market?
Who are the leading companies in the Australia Animal Protein Ingredients Market?
Which region commanded the largest share of the Australia Animal Protein Ingredients Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Powders
- 1.2.2 Granules/Flakes
- 1.2.3 Liquids/Pastes
- 1.3 By Source
- 1.3.1 Dairy
- 1.3.2 Fish & Marine
- 1.3.3 Meat & Poultry
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Sports & Active Nutrition
- 1.4.2 Clinical & Medical Nutrition
- 1.4.3 Pet Food
- 1.4.4 Aquafeed & Livestock Feed
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,077.59 million → 2032: USD 1,799.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Animal Protein Ingredients Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Animal Protein Ingredients Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Animal Protein Ingredients Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Animal Protein Ingredients Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Animal Protein Ingredients Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Animal Protein Ingredients Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Animal Protein Ingredients Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Animal Protein Ingredients Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,077.59 million → 2032: USD 1,799.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Animal Protein Ingredients Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Powders
- 12.3.7.2 Granules/Flakes
- 12.3.7.3 Liquids/Pastes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dairy
- 12.4.7.2 Fish & Marine
- 12.4.7.3 Meat & Poultry
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Sports & Active Nutrition
- 12.5.7.2 Clinical & Medical Nutrition
- 12.5.7.3 Pet Food
- 12.5.7.4 Aquafeed & Livestock Feed
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Animal Protein Ingredients End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Animal Protein Ingredients Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Animal Protein Ingredients Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Animal Protein Ingredients Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cargill
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Tyson Foods
- 18.4 Darling Ingredients
- 18.5 Fonterra Co-operative Group Limited
- 18.6 Maxum Foods
- 18.7 ADM Trading Australia Pty Ltd
- 18.8 Eurial I&N
- 18.9 Kemin Industries
- 18.10 Prinova
- 18.11 Armor Proteines
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

