
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Feminine Hygiene Products Market Size 2023 | USD 174.29 million |
| Australia Feminine Hygiene Products Market, CAGR | 7.49% |
| Australia Feminine Hygiene Products Market Size 2032 | USD 334.23 million |
Market Overview:
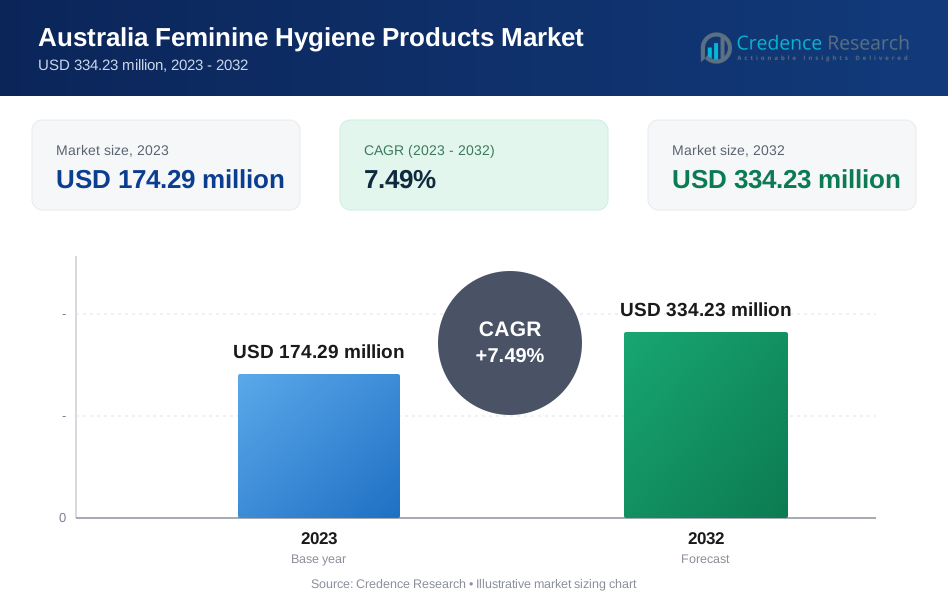
Australia Feminine Hygiene Products size was valued at USD 174.29 million in 2023 and is anticipated to reach USD 334.23 million by 2032, at a CAGR of 7.49% during the forecast period (2023-2032).
The growth of the Australian feminine hygiene products market is being driven by several key factors. Increased awareness and education about menstrual health have empowered consumers to make more informed decisions regarding hygiene products. This shift is further amplified by the rising demand for sustainable alternatives, as more consumers opt for eco-friendly products like menstrual cups and period underwear, driven by growing environmental concerns. Additionally, government initiatives aimed at improving access to menstrual products, particularly in schools and public spaces, have helped to reduce period poverty and increase product availability. The introduction of innovative product offerings, such as organic cotton pads and hypoallergenic tampons, has further expanded the market, catering to consumers’ desires for health-conscious and ethically produced alternatives. As a result, these drivers are positioning the market for steady growth, with eco-friendly and reusable products expected to experience particularly strong demand in the coming years.
The market for feminine hygiene products in Australia is largely concentrated in urban areas, where there is a higher demand for premium, sustainable products, reflecting the population's growing disposable income and environmental awareness. In contrast, rural and remote regions face challenges in terms of access to these products, with a significant portion of the population struggling with product affordability. This gap in accessibility highlights the need for targeted solutions, such as subsidies or outreach programs, to ensure that all Australians, regardless of location, have equitable access to essential menstrual hygiene products. The distribution of products is diverse, with supermarkets, pharmacies, and health stores being the primary retail channels, although e-commerce is rapidly growing, particularly among younger, tech-savvy consumers. This trend toward online shopping allows consumers to explore a wider variety of products, fueling further market expansion.
Market Insights:
- The Australian feminine hygiene products market was valued at USD 174.29 million in 2023 and is expected to reach USD 334.23 million by 2032, growing at a CAGR of 7.49%.
- The global feminine hygiene products market, valued at USD 23,490.00 million in 2023, is projected to reach USD 43,917.35 million by 2032, growing at a CAGR of 7.2% from 2023 to 2032.
- Increased awareness and education about menstrual health are empowering consumers to make more informed choices about hygiene products, contributing to the market’s growth.
- A strong shift toward sustainable products, such as menstrual cups, period underwear, and organic cotton pads, is driven by growing environmental concerns and eco-conscious consumer behavior.
- Government initiatives to combat period poverty are improving access to menstrual products, particularly in underserved areas, enhancing overall market penetration.
- Innovations in product offerings, such as hypoallergenic tampons, breathable pads, and biodegradable packaging, are diversifying the market and meeting evolving consumer needs.
- Despite growth, affordability remains a challenge, particularly for lower-income individuals in rural and remote areas, limiting access to premium sustainable products.
- Social and cultural barriers, including stigmatization and hesitancy around discussing menstruation, continue to affect product adoption, especially in conservative areas.
Market Drivers:
Increased Awareness and Education
The growing awareness of menstrual health and hygiene is one of the most significant drivers of the Australian feminine hygiene products market. Over recent years, there has been a marked shift in how menstruation is perceived, with greater openness and educational initiatives helping to destigmatize the topic. Campaigns in schools, social media, and healthcare platforms have significantly contributed to a more informed population, encouraging individuals to make better choices when selecting feminine hygiene products. This shift in awareness has not only increased product demand but also led to greater adoption of healthier, more sustainable products. Consequently, the market is witnessing a growing consumer preference for high-quality, reliable, and hygienic products that cater to various needs, from organic materials to hypoallergenic options.
Shift Towards Sustainable Products
Sustainability is another critical factor propelling the growth of the Australian feminine hygiene market. As consumers become more environmentally conscious, there has been an increased demand for eco-friendly and reusable hygiene products. Traditional products such as disposable pads and tampons, which contribute to significant plastic waste, are being replaced by more sustainable alternatives like menstrual cups, period underwear, and organic cotton pads. For instance, Breezy Body has introduced seamless period underwear made with eco-friendly materials and free from harmful chemicals, which customers praise for comfort, leak-proof protection, and discretion under clothing. These products are not only environmentally friendly but are also cost-effective in the long run, providing an attractive proposition for many consumers. This transition aligns with broader global sustainability trends, where individuals and organizations are seeking solutions that minimize their environmental footprint. The rise in demand for sustainable products is expected to continue shaping the market, particularly as more consumers become aware of the environmental impact of traditional menstrual products.
Government Support and Initiatives
Government support has played a crucial role in enhancing market growth by improving access to feminine hygiene products across the country. In recent years, Australian policymakers have increasingly recognized the importance of menstrual hygiene, leading to initiatives that aim to reduce period poverty and ensure equitable access to sanitary products. Programs that provide free products in schools, universities, and public facilities have helped make menstrual products more accessible to those in need. For instance, in the 2024–25 federal budget, the Commonwealth allocated $12.5 million to supply free period products to women and girls in remote First Nations communities. Additionally, there have been several public health campaigns to raise awareness about the importance of menstrual health and hygiene. These efforts have reduced barriers to access and further fueled the demand for feminine hygiene products, with particular emphasis on ensuring all women, regardless of socio-economic status, have access to high-quality products.
Product Innovation and Diversity
Innovation in product offerings is another essential driver of the Australian feminine hygiene market. Manufacturers are continuously developing new and improved products to meet the diverse needs of consumers. This includes innovations in product material, such as the use of organic cotton, as well as technological advancements in product design. For example, period underwear that combines comfort and absorbency, and tampons and pads designed with more breathable, natural materials, are becoming more popular. Furthermore, advances in biodegradable and eco-friendly packaging are attracting environmentally conscious consumers. The increasing variety of products available ensures that consumers can find products tailored to their specific preferences, such as hypoallergenic options, odor control, and enhanced comfort features. This ongoing innovation helps drive market growth by expanding product choices and meeting the evolving needs of consumers across the country.
Market Trends:
Growth in Period Underwear Adoption
Period underwear is becoming an increasingly popular choice among Australian consumers. This product category is gaining traction due to its comfort, reusability, and eco-friendly nature. Many consumers are shifting toward period underwear as it provides a sustainable alternative to traditional products like pads and tampons. The growing demand for such products reflects broader consumer trends favoring sustainability and cost-effective menstrual care solutions. As awareness of these products' benefits continues to rise, more consumers are incorporating them into their menstrual care routines.
Expansion of Online Retail Channels
The Australian feminine hygiene market is experiencing a shift towards online retail platforms. E-commerce has become a preferred shopping method for many, especially among younger, tech-savvy consumers. The convenience of online shopping, coupled with a wider range of product options available through digital channels, has contributed to this trend. Online platforms offer consumers the ability to browse a variety of products, compare brands, and read reviews, providing a more informed shopping experience. This growth in online sales is reshaping the retail landscape for feminine hygiene products, enabling brands to reach a broader audience.
Government Initiatives to Combat Period Poverty
Government initiatives are playing an essential role in addressing period poverty and ensuring greater accessibility to menstrual products across Australia. Various programs have been introduced to provide free products in schools, universities, and public facilities, particularly for underserved communities. These initiatives are designed to alleviate the financial burden of menstrual products for individuals from low-income households and help break down barriers to accessing basic hygiene. For instance, in the Australian Capital Territory (ACT), the government has committed $2.8 million to roll out free period products in public places, schools, and health services, making ACT the first jurisdiction in Australia to enshrine this provision in law. As these programs expand, the market will likely see an increase in the adoption of feminine hygiene products, particularly among groups that previously faced challenges in obtaining them.
Innovation in Product Offerings
Continuous innovation in the feminine hygiene product category is another key trend shaping the Australian market. Companies are focusing on introducing products with enhanced features, such as ultra-thin pads, improved absorbency, and more breathable materials. For example, ModiBodi’s patented Modifier Technology provides leak-proof, odour-resistant, and moisture-wicking protection, with ranges tailored for sports, swimwear, and everyday use. Additionally, the demand for organic and biodegradable products is on the rise, driven by consumers' growing concerns about health and environmental sustainability. These innovations not only cater to consumer preferences for high-performance products but also align with the broader global shift toward environmentally conscious consumerism. As more brands introduce innovative and healthier alternatives, the product offering continues to diversify and expand, attracting a wider range of consumers.
Market Challenges Analysis:
Affordability and Period Poverty
Despite increasing access to feminine hygiene products, affordability remains a significant challenge, particularly for lower-income groups. While government initiatives are addressing period poverty by providing free products in select locations, many individuals, especially in rural and remote areas, still struggle to afford high-quality products. The cost of premium menstrual products, such as organic and eco-friendly alternatives, may deter budget-conscious consumers from purchasing these products, limiting their accessibility. In these cases, more affordable but less sustainable options may be favored, posing a challenge to the widespread adoption of eco-friendly products.
Cultural and Social Barriers
In Australia, like many other countries, menstrual health remains a sensitive subject for some segments of the population. Despite growing awareness and education, there are still cultural and social barriers to openly discussing menstruation. This can result in stigmatization, which may prevent some individuals from seeking out the products they need or trying new, more sustainable alternatives. In particular, younger generations and those in rural or conservative areas may face challenges in fully embracing available menstrual care solutions due to lingering taboos. Breaking down these barriers requires continuous education and open conversations about menstrual health.
Sustainability Concerns and Product Performance
While there is a growing demand for sustainable products, concerns over product performance can act as a restraint. Eco-friendly products, such as biodegradable pads and menstrual cups, may not always offer the same level of convenience, comfort, or performance as traditional products. This can lead to hesitation among consumers, particularly those who prioritize reliability and ease of use. For instance, in a survey of 600 Victorian women aged 15–29, 24% had used period underwear and 17% a menstrual cup during their last period, but many cited challenges with cleaning and changing reusable products outside the home. Manufacturers face the challenge of creating products that meet both sustainability goals and the high-performance standards expected by consumers.
Market Opportunities:
The Australian feminine hygiene products market presents significant opportunities for growth, particularly driven by the increasing consumer demand for sustainable and eco-friendly alternatives. As more individuals become conscious of the environmental impact of traditional menstrual products, there is a rising shift towards reusable and biodegradable options such as menstrual cups, period underwear, and organic cotton pads. This shift aligns with broader global sustainability trends, providing manufacturers with the opportunity to innovate and introduce products that cater to health-conscious and environmentally aware consumers. Additionally, expanding product offerings that combine comfort, convenience, and sustainability can help companies tap into this growing market segment, attracting environmentally conscious consumers who are willing to invest in long-term, eco-friendly solutions.
Another key opportunity lies in expanding access to feminine hygiene products in underserved regions, particularly in rural and remote areas where access may be limited. Government initiatives aimed at reducing period poverty have already made a positive impact, but there remains room for more comprehensive solutions that ensure equitable access to products for all demographics. Companies that can successfully partner with governmental and non-governmental organizations to distribute products in these regions will not only contribute to social good but also strengthen their brand image and consumer loyalty. Furthermore, the growing popularity of online shopping presents a valuable channel for expanding product availability and reaching a broader audience, particularly among younger consumers who prioritize convenience and variety in their purchasing decisions. These opportunities provide a clear path for growth in an evolving and increasingly competitive market.
Market Segmentation Analysis:
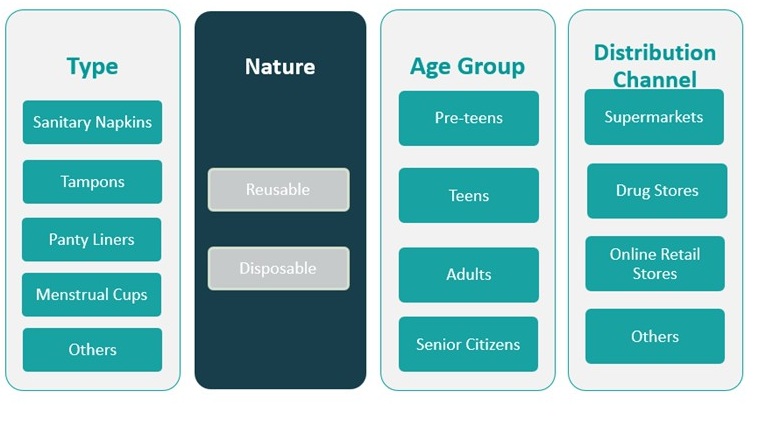
The Australian feminine hygiene products market is characterized by several key segments, each catering to different consumer needs and preferences.
By product type, sanitary napkins remain the most widely used, followed by tampons and panty liners. Menstrual cups are gaining traction due to their sustainability and eco-friendly nature, while other products such as feminine hygiene wipes and period underwear cater to niche consumer demands.
By nature, these products are available in both disposable and reusable options, with disposable products dominating the market. However, reusable products like menstrual cups and period underwear are experiencing significant growth due to increasing environmental awareness among consumers.
By age groups, with products tailored to specific life stages. Pre-teens and teens typically use smaller, lighter products such as panty liners and pads, while adults and senior citizens may prefer more absorbent products like tampons and menstrual cups. The shift toward eco-friendly and reusable products is particularly noticeable among adults, driven by health and sustainability concerns.
By distribution channels, supermarkets and drugstores remain the primary retail outlets for feminine hygiene products, providing consumers with easy access to a wide range of options. However, online retail stores are rapidly growing in popularity, particularly among younger consumers, offering convenience and a broader selection of products. Other channels, such as health stores and pharmacies, also play a role in reaching more specialized consumer segments. As consumer preferences evolve, these segments will continue to shape the market dynamics.
Segmentation:
By Type
- Sanitary Napkins
- Tampons
- Panty Liners
- Menstrual Cups
- Others
By Nature
- Reusable
- Disposable
By Age-Group
- Pre-teens
- Teens
- Adults
- Senior Citizens
By Distribution Channel
- Supermarkets
- Drug Stores
- Online Retail Stores
- Others
Regional Analysis:
Australia's feminine hygiene products market exhibits regional variations influenced by demographic factors, urbanization, and consumer preferences. While comprehensive regional market share data is limited, insights from various sources provide a general understanding of regional dynamics.
New South Wales and Australian Capital Territory
New South Wales (NSW), encompassing Sydney, and the Australian Capital Territory (ACT), including Canberra, are among the leading regions in the feminine hygiene market. These areas benefit from high population densities, urbanization, and increased awareness of menstrual health. The demand for both traditional and sustainable products is robust, driven by a health-conscious and environmentally aware consumer base. Government initiatives and educational programs further support market growth in these regions.
Victoria and Tasmania
Victoria, with Melbourne as a cultural and commercial hub, and Tasmania, exhibit significant market activity. Melbourne's commitment to sustainability has fostered a preference for eco-friendly menstrual products. The presence of various retail outlets and increased product availability contribute to the market's expansion in these regions. Additionally, awareness campaigns and community outreach programs have played a role in educating consumers about menstrual health.
Queensland
Queensland, with Brisbane as its capital, shows a growing market for feminine hygiene products. The state's expanding urban population and rising disposable income levels have led to increased demand for a diverse range of menstrual care products. The popularity of online retail platforms has also facilitated access to a broader selection of products, catering to the preferences of consumers in both urban and rural areas.
South Australia and Northern Territory
South Australia, including Adelaide, and the Northern Territory face challenges related to accessibility and affordability of menstrual products, particularly in remote and rural areas. However, government programs and nonprofit initiatives aimed at reducing period poverty are making strides in improving access to essential products. These efforts are gradually enhancing market penetration and consumer trust in feminine hygiene products.
Western Australia
Western Australia, with Perth as its capital, presents a unique market landscape. The state's vast geographical expanse and varying population densities influence product distribution and accessibility. Urban centers like Perth experience demand for a wide range of menstrual products, while rural areas benefit from targeted initiatives aimed at improving product availability and affordability.
Key Player Analysis:
- Johnson & Johnson
- Procter & Gamble
- Kimberly-Clark
- Essity Aktiebolag
- Kao Corporation
- Daio Paper Corporation
- Unicharm Corporation
- Premier FMCG
- Ontex
- Hengan International Group Company Ltd
- Drylock Technologies
- Natracare LLC
- First Quality Enterprises, Inc
- TABOO
Competitive Analysis:
The Australian feminine hygiene products market is highly competitive, with a mix of multinational corporations and emerging local brands. Established players such as Procter & Gamble, Kimberly-Clark, and Johnson & Johnson hold significant market share due to their strong brand recognition, wide distribution networks, and comprehensive product portfolios. These global brands offer a range of products, including sanitary napkins, tampons, and panty liners, catering to diverse consumer needs. However, local brands are increasingly gaining market share, particularly in the eco-friendly segment. Companies like Modibodi and TOM Organic have capitalized on the growing demand for sustainable, reusable products such as menstrual cups and period underwear. These brands appeal to environmentally conscious consumers seeking alternatives to traditional, disposable products. The market is also seeing a shift towards online retail platforms, providing both established and new players with opportunities to reach a broader consumer base, further intensifying competition. Innovation in product design and sustainability is key to staying competitive.
Recent Developments:
- In March 2025, Hub Australia announced a partnership with Share the Dignity and Femmé Organic to address period poverty in the workplace. This collaboration, revealed during International Women’s Month, aims to normalize menstruation and empower individuals with menstrual cycles by increasing access to feminine hygiene products and promoting menstrual health awareness across Australia.
- In November 2024, TLC Healthcare formed a significant partnership with Australian company Femmé Organic to make feminine hygiene products available across its healthcare sites. This initiative reflects the growing demand for organic and eco-friendly menstrual products and aligns with broader trends in the Australian market toward sustainable and premium feminine hygiene solutions.
- In Feb 2023, Kimberly-Clark announced its partnership with the New South Wales government in Australia to address period poverty by providing free tampons and pads to public school students. The company will also install over 4,600 feminine product dispensers in school restrooms throughout the state, supporting both access to products and menstrual education for students
Market Concentration & Characteristics:
The Australian feminine hygiene products market is moderately concentrated, with a blend of established multinational corporations and emerging local brands. Major international players such as Procter & Gamble (P&G), Kimberly-Clark, and Unicharm hold significant market shares, benefiting from extensive distribution networks and strong brand recognition. These companies offer a wide range of products, including sanitary pads, tampons, and panty liners, catering to diverse consumer needs. In recent years, there has been a notable rise in local brands focusing on sustainable and eco-friendly alternatives, such as menstrual cups and period underwear. Companies like Modibodi and TOM Organic have capitalized on the growing consumer demand for reusable and organic products, positioning themselves as key players in the market. This shift reflects a broader trend towards sustainability and health-conscious choices among Australian consumers. The market is characterized by a high degree of competition, with companies continually innovating to meet evolving consumer preferences. Product differentiation, particularly in terms of sustainability and performance, plays a crucial role in gaining consumer loyalty. Additionally, the increasing popularity of online retail channels has provided both established and new entrants with opportunities to reach a broader audience, further intensifying market competition.
Report Coverage:
The research report offers an in-depth analysis based on Type, Nature, Age-Group and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for eco-friendly and reusable products will continue to rise, driven by increased environmental awareness.
- Online retail channels will become more significant, expanding product availability and convenience for consumers.
- Period underwear and menstrual cups will gain greater market share as sustainable alternatives to traditional products.
- Government initiatives to reduce period poverty will increase access to feminine hygiene products across diverse demographics.
- Product innovation will remain a key focus, with continued development of organic, hypoallergenic, and biodegradable options.
- Consumers will seek more personalized and health-conscious products, including options for sensitive skin and organic materials.
- The influence of social media and influencers will further shape consumer preferences, especially among younger generations.
- Rural and remote areas will see improved access to feminine hygiene products through targeted distribution programs.
- Growing disposable incomes will support the demand for premium and specialized products.
- The overall market will see steady growth, driven by both consumer demand for sustainability and enhanced product diversity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Australia Feminine Hygiene Products Market?
What factors are driving the growth of the Australia Feminine Hygiene Products market?
What are the key segments within the Australia Feminine Hygiene Products market?
Who are the major players in the Australia Feminine Hygiene Products Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Feminine Hygiene Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Australia Feminine Hygiene Products Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 174.29 million → 2032: USD 334.23 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Feminine Hygiene Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Feminine Hygiene Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Feminine Hygiene Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Australia Feminine Hygiene Products Market Drivers
- 3.3 Australia Feminine Hygiene Products Market Restraints & Challenges
- 3.4 Australia Feminine Hygiene Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Feminine Hygiene Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Feminine Hygiene Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Feminine Hygiene Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Feminine Hygiene Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Australia Feminine Hygiene Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Australia Feminine Hygiene Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Feminine Hygiene Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Australia Feminine Hygiene Products Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Australia Feminine Hygiene Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Feminine Hygiene Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Australia Feminine Hygiene Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Australia Feminine Hygiene Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Australia Feminine Hygiene Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Australia Feminine Hygiene Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Australia Feminine Hygiene Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Australia Feminine Hygiene Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Australia Feminine Hygiene Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Australia Feminine Hygiene Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Australia Feminine Hygiene Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
