
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Appearance Chemical Market Size 2024 | USD 31189.6 Million |
| Automotive Appearance Chemical Market, CAGR | 4.55% |
| Automotive Appearance Chemical Market Size 2032 | USD 44524.9 Million |
Market Overview:
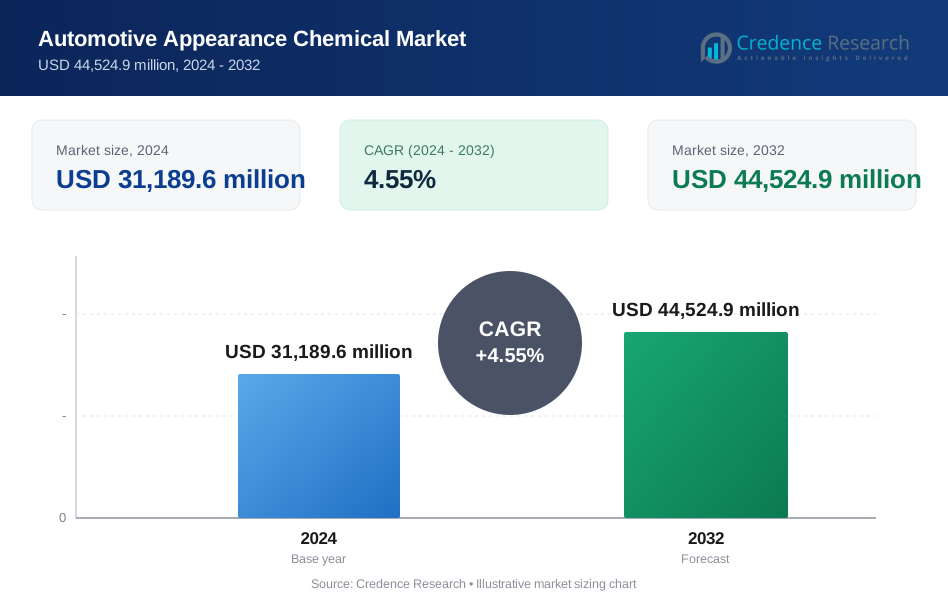
The Global Automotive Appearance Chemical Market is projected to grow from USD 31189.6 million in 2024 to an estimated USD 44524.9 million by 2032, with a compound annual growth rate (CAGR) of 4.55% from 2024 to 2032.
Growing consumer preference for high-performance cleaning and protective solutions is a key market driver. The increasing penetration of ceramic coatings, nanotechnology-based protectants, and water-based cleaners highlights the shift toward advanced and sustainable solutions. Additionally, expanding automotive aftermarkets, rising sales of luxury vehicles, and a surge in do-it-yourself (DIY) car care trends are fueling demand. Stringent environmental regulations also push manufacturers to develop biodegradable and low-VOC (volatile organic compound) products, fostering innovation in the sector. The rising focus on long-term vehicle protection and resale value preservation has increased consumer willingness to invest in premium automotive appearance chemicals. Moreover, growing awareness of paint protection films (PPF) and self-healing coatings is further strengthening the market’s expansion. Increasing collaborations between automotive chemical manufacturers and detailing service providers are also contributing to the growth of advanced appearance solutions.
Regionally, North America and Europe dominate the market due to high vehicle ownership rates and strong consumer preference for premium automotive care products. The Asia-Pacific region, particularly China and India, is expected to witness the fastest growth due to rising urbanization, increasing disposable income, and expanding automotive production. The Middle East and Latin America are also emerging markets, supported by a growing automotive sector and higher demand for protective coatings against extreme weather conditions. China’s strong automotive manufacturing base and increasing focus on luxury vehicle maintenance are driving the adoption of advanced appearance chemicals in the region. Similarly, the rising number of car detailing centers and professional vehicle care services in urban areas across India is boosting demand for high-performance cleaning solutions. Additionally, government incentives for electric vehicle (EV) adoption in various regions have spurred interest in eco-friendly and durable car care products to maintain these vehicles’ aesthetics and efficiency.
Market Insights:
- The global automotive appearance chemical market is expected to grow from USD 31.2 billion in 2024 to USD 44.5 billion by 2032, with a CAGR of 4.55%.
- Increasing consumer demand for high-performance cleaning and protective solutions is driving market expansion, with a shift towards ceramic coatings and nanotechnology-based protectants.
- The rise in DIY car care trends and expanding automotive aftermarkets are contributing to the growing demand for easy-to-use appearance chemicals.
- Stringent environmental regulations are pushing manufacturers to develop biodegradable, low-VOC products, fostering eco-friendly innovations in the industry.
- Consumer focus on long-term vehicle protection and resale value preservation is encouraging investment in premium automotive appearance chemicals.
- North America and Europe dominate the market due to high vehicle ownership and strong preference for premium car care products.
- The Asia-Pacific region, particularly China and India, is experiencing the fastest market growth driven by urbanization, increasing disposable incomes, and rising vehicle production.
Market Drivers:
Rising Consumer Preference for Vehicle Aesthetics and Maintenance
The increasing emphasis on vehicle aesthetics and regular maintenance is a significant driver for the Global Automotive Appearance Chemical Market. Consumers are increasingly investing in high-quality cleaning, polishing, and protective solutions to enhance the longevity and appearance of their vehicles. For instance, according to 3M Company, their Ceramic Coating product line has seen year-over-year increase in sales, with their latest formulation providing up to 5 years of protection against environmental factors. The rise in disposable income, particularly in emerging economies, has led to a growing trend of frequent vehicle detailing and maintenance. Additionally, car owners are becoming more conscious of exterior and interior protection, boosting demand for advanced chemical formulations that provide long-lasting shine and durability.
Technological Advancements in Automotive Care Solutions
Innovations in ceramic coatings, nanotechnology-based protectants, and water-based cleaning agents have transformed the automotive appearance chemical industry. Manufacturers are focusing on developing high-performance products that offer superior protection against environmental factors such as UV rays, dirt, and corrosion. For instance, chemical Guys introduced their HydroSlick Ceramic Coating HyperWax, which utilizes SiO2 gel suspension technology to create a protective layer that lasts up to 1 year. The shift toward bio-based and low-VOC (volatile organic compound) chemicals aligns with stringent environmental regulations and growing consumer demand for sustainable solutions. These advancements not only enhance the effectiveness of appearance chemicals but also provide eco-friendly alternatives that comply with regulatory standards in various regions.
Expansion of the Automotive Aftermarket and DIY Trends
The global automotive aftermarket is expanding due to rising vehicle ownership and an increasing preference for cost-effective maintenance solutions. Car owners are increasingly opting for do-it-yourself (DIY) car care products, fueling demand for easy-to-use appearance chemicals such as spray coatings, quick wax solutions, and interior cleaners. For instance, Meguiar’s and Turtle Wax have introduced DIY-friendly spray waxes and ceramic coatings that allow consumers to maintain their vehicle’s shine without professional assistance. The rise of e-commerce platforms has further facilitated market growth by making premium automotive care products accessible to a broader consumer base. Additionally, professional car detailing services are witnessing increased demand, particularly in urban areas, where vehicle owners seek high-quality detailing services for long-term vehicle protection.
Growing Vehicle Sales and Premium Segment Expansion
The rising production and sales of passenger and luxury vehicles contribute to the expanding demand for automotive appearance chemicals. The premium vehicle segment, in particular, relies on advanced coatings and detailing solutions to maintain aesthetics and enhance resale value. For example, luxury car brands like BMW and Mercedes-Benz now offer factory-applied ceramic coatings to enhance exterior protection and minimize paint degradation. The increasing adoption of electric vehicles (EVs) has also influenced market growth, as EV manufacturers emphasize sustainable and high-performance protective coatings. Additionally, the expansion of the commercial vehicle sector, particularly in logistics and ride-hailing services, has driven the need for regular vehicle maintenance, further boosting demand for effective automotive appearance chemicals.
Market Trends:
Growing Demand for Sustainable and Eco-Friendly Solutions
The shift toward sustainable and eco-friendly automotive appearance chemicals is a key trend in the market. Consumers and regulatory authorities are increasingly pushing for low-VOC, biodegradable, and water-based formulations to minimize environmental impact. Manufacturers are responding by developing plant-based surfactants, non-toxic waxes, and solvent-free cleaners that offer the same level of performance as traditional chemicals. For example, Chemical Guys' ECO Smart Waterless Car Wash is a VOC-compliant, biodegradable solution that conserves water while delivering high-performance cleaning. The introduction of recyclable packaging and concentrated formulas that require less water usage is further driving sustainability efforts. Additionally, stringent government policies on chemical emissions and hazardous waste disposal are accelerating the adoption of green alternatives in professional car detailing and DIY applications.
Rising Popularity of Advanced Ceramic Coatings and Graphene-Based Protectants
The market is witnessing a surge in demand for advanced ceramic coatings and graphene-based protectants, which offer superior durability and long-lasting protection. Unlike conventional waxes and sealants, these coatings provide hydrophobic properties, UV resistance, and scratch protection, ensuring extended vehicle aesthetics. For instance, Gtechniq’s Crystal Serum Ultra ceramic coating offers up to nine years of paint protection, making it a preferred choice among professional detailers. The increasing availability of consumer-grade ceramic coatings has enabled more vehicle owners to apply protective coatings without professional assistance, boosting the DIY segment. Graphene-based coatings, known for their enhanced chemical resistance and anti-static properties, are gaining traction among luxury and performance vehicle owners. As a result, detailing professionals and manufacturers are investing in research and development to enhance the longevity and self-cleaning capabilities of these advanced formulations.
Expansion of Online Retail and E-Commerce Platforms
The growing dominance of e-commerce platforms has transformed the distribution landscape for automotive appearance chemicals. Consumers now have direct access to a wide range of premium car care products from global brands, eliminating the reliance on traditional retail channels. For instance, Amazon and Walmart’s auto care sections offer direct-to-consumer access to brands like Meguiar’s, Chemical Guys, and Armor All, allowing customers to compare products and read reviews before purchasing. The convenience of online shopping, coupled with detailed product descriptions, customer reviews, and video demonstrations, has enhanced consumer confidence in purchasing high-end automotive care solutions. Subscription-based models and bundled product offerings are also gaining traction, allowing brands to build customer loyalty and ensure repeat purchases. Additionally, the integration of augmented reality (AR) and artificial intelligence (AI)-driven recommendations is enhancing the digital shopping experience, enabling customers to select the most suitable appearance chemicals for their vehicles.
Increasing Adoption of Smart and Self-Healing Coatings
The market is experiencing growing interest in smart coatings and self-healing technologies, which offer enhanced protection and longevity. These innovative coatings contain microcapsules filled with active agents that automatically repair minor scratches and imperfections when exposed to heat or UV light. Luxury automakers and detailing professionals are incorporating these advanced solutions into their services to provide long-term vehicle protection with minimal maintenance requirements. For example, Feynlab offers self-healing ceramic coatings that activate at high temperatures, restoring paint surfaces after minor abrasions. Additionally, the rise of connected vehicles and automated car maintenance solutions has led to the development of sensor-compatible coatings that maintain vehicle aesthetics without interfering with autonomous driving technologies. As automotive technology advances, the integration of intelligent coatings with nanotechnology-based enhancements is expected to redefine the automotive appearance chemical market.
Market Challenges Analysis:
Stringent Environmental Regulations and Compliance Requirements
The Global Automotive Appearance Chemical Market faces significant challenges due to increasingly stringent environmental regulations governing the production and use of chemical-based car care products. Governments and regulatory bodies across regions are imposing strict VOC (volatile organic compound) limits and hazardous chemical restrictions, compelling manufacturers to reformulate their products. While the shift toward eco-friendly and biodegradable alternatives is gaining momentum, compliance with evolving regulatory frameworks increases production costs and limits the availability of certain high-performance formulations.
High Cost of Advanced and Sustainable Solutions
The growing demand for ceramic coatings, graphene-based protectants, and self-healing coatings has introduced premium-priced solutions to the market. These advanced formulations offer superior durability and protection but come at a higher cost, restricting their accessibility to budget-conscious consumers. Additionally, the development and adoption of bio-based and waterborne appearance chemicals require substantial investment in research and manufacturing processes. This cost factor may hinder widespread adoption, particularly in price-sensitive markets where consumers prioritize affordability over long-term benefits.
Limited Consumer Awareness and Adoption in Emerging Markets
Despite the increasing global demand for automotive appearance chemicals, consumer awareness and adoption rates remain relatively low in emerging markets. Many vehicle owners in developing regions prioritize basic maintenance over specialized car care products, limiting market expansion. Additionally, the lack of professional detailing services and limited distribution networks for premium automotive appearance chemicals further slows market penetration. As a result, manufacturers must focus on educational marketing strategies and expand their presence in high-growth regions to drive adoption.
Impact of Fluctuating Raw Material Prices
The volatility in raw material prices, particularly petroleum-based solvents, surfactants, and specialty chemicals, poses a challenge for manufacturers. Supply chain disruptions, geopolitical uncertainties, and fluctuations in crude oil prices directly impact production costs and profit margins. Additionally, sourcing sustainable raw materials at competitive prices remains a hurdle, making it difficult for manufacturers to balance cost efficiency with product innovation. These pricing challenges may lead to increased retail costs, affecting consumer purchasing behavior in price-sensitive segments.
Market Opportunities:
The Global Automotive Appearance Chemical Market presents significant growth opportunities driven by the increasing consumer demand for high-performance and sustainable car care solutions. The rising adoption of electric vehicles (EVs) and luxury automobiles has created a strong market for advanced protective coatings, ceramic treatments, and graphene-based sealants that enhance vehicle longevity and aesthetics. Additionally, the growing trend of vehicle customization and professional detailing services is expanding the demand for premium automotive appearance chemicals. As consumers become more conscious of environmental sustainability, manufacturers have the opportunity to develop and commercialize eco-friendly, water-based, and biodegradable formulations, catering to regulatory requirements while appealing to environmentally conscious buyers.
The expansion of digital sales channels and e-commerce platforms provides another lucrative avenue for market growth. With the increasing shift toward direct-to-consumer sales models, automotive care brands can enhance customer engagement through online retail, subscription-based product offerings, and personalized AI-driven recommendations. Emerging markets in Asia-Pacific, Latin America, and the Middle East present untapped potential due to rising disposable incomes, growing urbanization, and increasing vehicle ownership. Additionally, the integration of nanotechnology and smart coatings in automotive appearance chemicals offers opportunities for innovation, allowing manufacturers to introduce self-healing, weather-resistant, and UV-protective coatings. Companies that invest in technological advancements and strategic partnerships with automotive OEMs and detailing service providers will gain a competitive edge in this expanding market.
Market Segmentation Analysis:
By Product Type
The global automotive appearance chemical market is primarily segmented by product type, including polishes, windshield washer fluids, soaps, coatings, and car wax. Polishes hold a significant share due to their role in maintaining vehicle aesthetics and protecting paint surfaces. Windshield washer fluids are essential for maintaining visibility, especially in adverse weather conditions. Soaps and car wax also dominate as essential maintenance products, contributing to vehicle cleanliness and shine. Coatings are gaining traction, driven by innovations in protective layers for vehicle exteriors, enhancing durability and gloss.
By Vehicle Type
The market is further divided by vehicle type, encompassing passenger cars, light commercial vehicles (LCV), and heavy commercial vehicles (HCV). Passenger cars account for the largest share, owing to the rising demand for vehicle maintenance and aesthetics among consumers. LCVs follow closely, with increased demand from fleet owners seeking affordable and durable appearance products. HCVs, although a smaller segment, are expanding due to the need for heavy-duty chemicals to maintain the exterior of large vehicles.
By Sales Channel
The market is also segmented by sales channel into aftermarket and original equipment manufacturers (OEMs). The aftermarket segment is the largest, driven by the growing trend of vehicle customization and maintenance. OEMs play a significant role as well, particularly in the initial sale of appearance chemicals, often bundled with vehicles for maintenance purposes. Both segments continue to expand as automotive manufacturers and consumers prioritize vehicle upkeep and aesthetics.
Segmentation:
By Product Type
- Polishes
- Windshield Washer Fluids
- Soaps
- Coatings
- Car Wax
By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles (LCV)
- Heavy Commercial Vehicles (HCV)
By Sales Channel
- Aftermarket
- Original Equipment Manufacturers (OEMs)
Regional Analysis:
North America: Strong Demand for Premium Automotive Care Products
North America holds a significant share of the Global Automotive Appearance Chemical Market, accounting for approximately 30% of total revenue. The region’s high vehicle ownership rates, strong consumer preference for premium car care products, and widespread availability of professional detailing services contribute to market expansion. The United States dominates the regional market due to the increasing popularity of ceramic coatings, graphene-based protectants, and advanced paint protection films. Additionally, the rising trend of do-it-yourself (DIY) car maintenance has fueled demand for easy-to-use and high-performance automotive appearance chemicals. Stringent environmental regulations on VOC emissions have also driven the adoption of water-based and biodegradable formulations, prompting manufacturers to innovate sustainable solutions.
Europe: Regulatory Influence Driving Eco-Friendly Innovations
Europe holds approximately 25% of the market share, driven by strict environmental and safety regulations that mandate the use of low-VOC, solvent-free, and biodegradable automotive appearance chemicals. Countries such as Germany, the UK, and France are key contributors due to their strong automotive industry, high consumer spending on vehicle maintenance, and the growing popularity of luxury and electric vehicles (EVs). The demand for nanotechnology-based and smart coatings is also rising as automakers and detailing professionals seek advanced solutions to enhance vehicle longevity. Additionally, the region’s well-established e-commerce sector has made premium automotive care products more accessible, further supporting market growth.
Asia-Pacific: Fastest-Growing Region with Expanding Automotive Sector
Asia-Pacific is the fastest-growing market, currently holding 28% of the global market share, and is projected to witness significant growth in the coming years. China, India, Japan, and South Korea are the major contributors, driven by rapid urbanization, increasing disposable incomes, and rising vehicle ownership. The expansion of the automotive manufacturing sector in China and India has spurred demand for protective coatings, detailing products, and eco-friendly cleaning solutions. Additionally, the growing number of car detailing service providers and increased consumer awareness regarding vehicle aesthetics and maintenance are further boosting the market. The region’s rising e-commerce penetration has made a wide range of automotive appearance chemicals accessible to consumers, strengthening market growth.
Latin America and Middle East & Africa: Emerging Markets with Growth Potential
Latin America and the Middle East & Africa (MEA) collectively account for 17% of the market share, with increasing opportunities for expansion. In Latin America, Brazil and Mexico are witnessing a surge in demand for affordable and high-quality automotive care products, driven by rising vehicle ownership and the expansion of the car detailing industry. The Middle East, particularly Saudi Arabia and the UAE, is experiencing increasing demand for heat-resistant and dust-repellent coatings, given the region’s extreme climatic conditions. Additionally, the growing preference for luxury and high-performance vehicles in these regions presents an opportunity for premium automotive appearance chemicals.
Key Player Analysis:
- PPG Industries
- 3M Company
- BASF SE
- Energizer Holdings Inc.
- Kao Corporation
- Jax Wax Inc.
- Malco Products Inc.
- Koch-Chemie GmbH
- Koster Keunen Inc.
- The Darent Wax Company Ltd.
- Northern Labs Inc.
- CRC Industries
- Turtle Wax Inc.
- DuPont de Nemours Inc.
Competitive Analysis:
The Global Automotive Appearance Chemical Market is highly competitive, with key players focusing on product innovation, sustainability, and strategic partnerships to maintain their market position. Leading companies such as 3M, Turtle Wax, Meguiar’s, Chemical Guys, SONAX, and Soft99 dominate the industry by offering high-performance protective coatings, polishes, and eco-friendly cleaning solutions. These brands leverage strong distribution networks, digital marketing strategies, and collaborations with automotive OEMs and detailing service providers to expand their market reach. For instance, 3M has expanded its car care product line with Scotchgard™ Paint Protection Film, offering superior protection against scratches and environmental damage. Competition is further intensified by new entrants and regional players introducing cost-effective and specialized solutions tailored to emerging markets. The increasing demand for ceramic and graphene-based coatings, biodegradable formulations, and smart coatings has prompted companies to invest in research and development. Additionally, the rise of e-commerce and direct-to-consumer sales channels has enabled smaller brands to gain traction, challenging established players in the premium and DIY automotive care segments.
Recent Developments:
- In October 2024, PPG Industries completed the sale of its architectural coatings business in the U.S. and Canada to American Industrial Partners (AIP) for $550 million. The transaction, which closed on December 2, 2024, involved a business that generated approximately $2 billion in revenue in 2023. The newly independent company, renamed The Pittsburgh Paints Company, will continue to serve professionals and DIY customers across the United States and Canada.
Market Concentration & Characteristics:
The Global Automotive Appearance Chemical Market exhibits a moderate to high market concentration, with a mix of established multinational corporations and regional players competing for market share. Leading brands such as 3M, Turtle Wax, Meguiar’s, and SONAX dominate the premium segment, leveraging their strong brand reputation, advanced formulations, and extensive distribution networks. Meanwhile, regional manufacturers and emerging brands focus on cost-effective and eco-friendly solutions to cater to price-sensitive markets. The market is characterized by continuous innovation, increasing consumer demand for sustainable products, and a growing preference for high-performance protective coatings. The shift toward water-based, biodegradable, and VOC-compliant formulations reflects regulatory influences and environmental concerns. Additionally, e-commerce and direct-to-consumer channels are reshaping market dynamics, allowing smaller players to gain traction. The industry also benefits from the rising popularity of DIY car care solutions and professional detailing services, further driving market expansion.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type By Vehicle Type and By Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Sustained market growth is expected, driven by increasing vehicle ownership, rising disposable income, and expanding automotive aftermarkets globally.
- Eco-friendly and biodegradable formulations will gain prominence as regulatory pressures on VOC emissions and hazardous chemicals increase.
- Advancements in nanotechnology and smart coatings will enhance product performance, offering self-healing, anti-static, and hydrophobic properties.
- Expansion of e-commerce and direct-to-consumer sales will provide greater accessibility to premium automotive appearance chemicals worldwide.
- Increased demand for ceramic and graphene-based coatings will reshape the protective coatings segment, appealing to both DIY consumers and professional detailing services.
- Growth in electric vehicle (EV) adoption will drive innovation in specialized coatings designed for enhanced protection and sustainability.
- Rising urbanization and vehicle customization trends in emerging markets will create new opportunities for automotive care brands.
- Strategic partnerships with OEMs and detailing service providers will strengthen market presence and enable product differentiation.
- Fluctuations in raw material prices and supply chain constraints may impact pricing strategies and product availability.
- AI-driven recommendations and digital marketing strategies will transform consumer engagement, boosting brand loyalty and sales.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Consumer Preference for Vehicle Aesthetics and Maintenance
Consumers are increasingly investing in high-quality cleaning, polishing, and protective solutions to enhance the longevity and appearance of their vehicles, driven by higher disposable incomes and a growing focus on vehicle resale value.
Technological Advancements in Automotive Care Solutions
Innovations such as ceramic coatings, nanotechnology-based protectants, and water-based cleaning agents are transforming the market by offering superior protection and eco-friendly alternatives that comply with stringent environmental regulations.
Expansion of Automotive Aftermarket and DIY Trends
The growing popularity of do-it-yourself car care and the expansion of the automotive aftermarket are fueling demand for easy-to-use appearance chemicals, supported by the rise of e-commerce platforms that make premium products more accessible.
Stringent Environmental Regulations
Increasingly strict regulations on VOC emissions and hazardous chemicals are pushing manufacturers to develop biodegradable and low-VOC products, fostering innovation and driving the adoption of sustainable automotive appearance chemicals.
Growth in Premium and Electric Vehicle Segments
Rising sales of luxury and electric vehicles are boosting demand for advanced protective coatings and high-performance appearance chemicals, as these segments prioritize long-term aesthetics, durability, and eco-friendly solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Automotive Appearance Chemical Market?
What factors are driving the growth of the Global Automotive Appearance Chemical Market?
What are the key segments within the Global Automotive Appearance Chemical Market?
What are some challenges faced by the Global Automotive Appearance Chemical Market?
Which region holds the largest share in the Global Automotive Appearance Chemical Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Polishes
- 1.2.2 Windshield Washer Fluids
- 1.2.3 Soaps
- 1.2.4 Coatings
- 1.2.5 Car Wax
- 1.3 By Vehicle Type
- 1.3.1 Passenger Cars
- 1.3.2 Light Commercial Vehicles (LCV)
- 1.3.3 Heavy Commercial Vehicles (HCV)
- 1.4 By Sales Channel
- 1.4.1 Aftermarket
- 1.4.2 Original Equipment Manufacturers (OEMs)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 31,189.6 million → 2032: USD 44,524.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Appearance Chemical Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Appearance Chemical Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Appearance Chemical Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Appearance Chemical Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Appearance Chemical Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Appearance Chemical Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Appearance Chemical Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Appearance Chemical Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 31,189.6 million → 2032: USD 44,524.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Appearance Chemical Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Polishes
- 12.3.7.2 Windshield Washer Fluids
- 12.3.7.3 Soaps
- 12.3.7.4 Coatings
- 12.3.7.5 Car Wax
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passenger Cars
- 12.4.7.2 Light Commercial Vehicles (LCV)
- 12.4.7.3 Heavy Commercial Vehicles (HCV)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Aftermarket
- 12.5.7.2 Original Equipment Manufacturers (OEMs)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Appearance Chemical Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Appearance Chemical Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Appearance Chemical Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 3M Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 PPG Industries
- 17.4 BASF SE
- 17.5 Turtle Wax Inc.
- 17.6 Kao Corporation
- 17.7 Energizer Holdings Inc.
- 17.8 Malco Products Inc.
- 17.9 Koch-Chemie GmbH
- 17.10 DuPont de Nemours Inc.
- 17.11 CRC Industries
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

