
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Interior Leather Market Size 2024 | USD 23069 Million |
| Automotive Interior Leather Market, CAGR | 4.8% |
| Automotive Interior Leather Market Size 2032 | USD 33567.5 Million |
Market Overview:
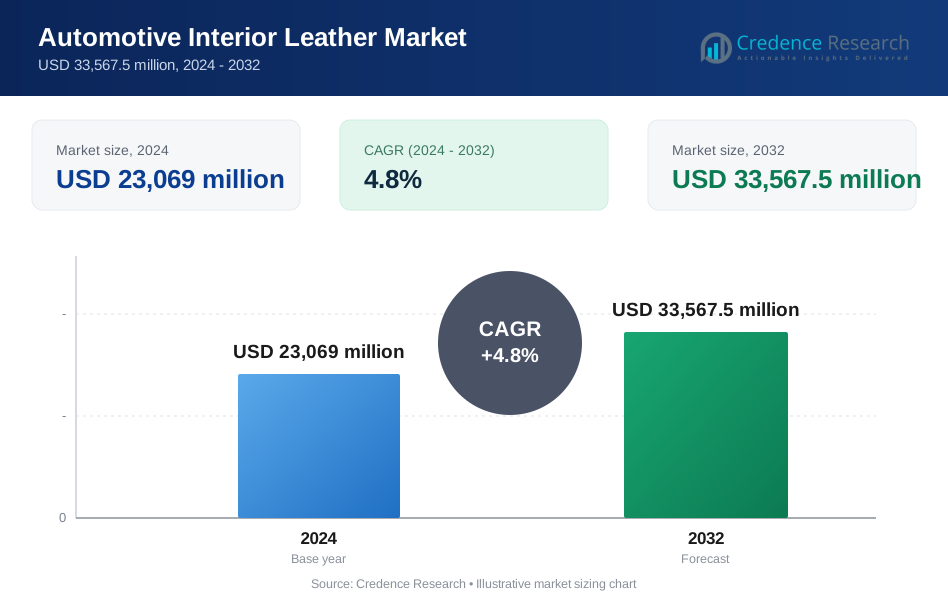
The Automotive Interior Leather Market is projected to grow from USD 23069 million in 2024 to an estimated USD 33567.5 million by 2032, with a compound annual growth rate (CAGR) of 4.8% from 2024 to 2032.
The key drivers of the automotive interior leather market include the rising consumer preference for luxurious and aesthetically appealing vehicle interiors, which has heightened the demand for high-quality leather materials. As automotive manufacturers focus on enhancing the overall driving experience, premium leather seats, dashboard covers, and upholstery are increasingly sought after. Advances in leather processing technologies, such as improved durability, eco-friendly treatments, and better quality finishes, also contribute to market growth. Additionally, the expansion of the automotive industry in emerging markets and increased disposable incomes are fueling demand for luxury and premium vehicles, which often feature high-end leather interiors. The integration of advanced technologies in leather production, such as sustainable and synthetic alternatives, also aligns with evolving consumer preferences for environmentally friendly and ethically sourced materials.
Geographically, the automotive interior leather market is led by North America and Europe, which together hold a significant share of the global market. North America, driven by high consumer demand for luxury vehicles and advanced interior features, remains a major market. In Europe, the strong presence of premium automotive brands and stringent regulations on vehicle interiors contribute to market growth. The Asia-Pacific region is experiencing rapid growth due to increasing automotive production, rising disposable incomes, and a growing preference for luxury vehicles in countries like China and India. The region's expanding middle class and evolving automotive industry are driving demand for high-quality leather interiors. Latin America and the Middle East & Africa are emerging markets with potential growth opportunities, driven by rising vehicle ownership and improving economic conditions. Each region exhibits unique growth patterns influenced by local automotive industry dynamics and consumer preferences.
Market Drivers:
Consumer Demand for Luxury and Premium Interiors:
A significant driver of the automotive interior leather market is the growing consumer demand for luxury and premium vehicle interiors. As disposable incomes rise globally, consumers are increasingly seeking high-quality and aesthetically pleasing vehicle interiors, which often feature premium leather materials. This trend is particularly evident in the luxury and high-end vehicle segments, where leather is a key element of the interior design, contributing to a sense of opulence and comfort. For instance, the seats & center stack segment dominated the market in 2022 with the largest revenue share. Leather in vehicle interior components such as the seat and center stack has grown increasingly common owing to its attributes such as durability, fewer vibrations, reduced interior noise levels, and aesthetic qualities. Automakers are responding to these preferences by incorporating top-grade leather into their vehicles to enhance the overall driving experience and meet the expectations of discerning consumers. This increasing demand for luxurious interiors is a major factor driving the growth of the automotive interior leather market. Moreover, the rise in consumers has called for an elevation to eco-friendlier options. The market is responding with ethically sourced leather and chrome-free tanning processes that reduce the environmental impact. This would cater to a growing segment of environmentally concerned luxury car buyers. In addition, the automotive industry is growing in emerging economies due to changing consumer disposable income and lifestyles of people, which are expected to offer great opportunities for market players during the forecast period. The companies belonging to the automotive interior leather market, therefore, could be expected to leverage this emerging trend by relying on product innovation, sustainability endeavors, and strategic collaborations to possibly enhance their competitiveness within this market.
Expansion of the Automotive Industry:
The expansion of the global automotive industry significantly influences the automotive interior leather market. As vehicle production increases, driven by rising vehicle ownership and demand in emerging markets, there is a corresponding need for high-quality interior materials, including leather. This growth is particularly pronounced in regions like Asia-Pacific, where economic development and increasing disposable incomes are driving higher vehicle sales. For instance, the passenger car segment dominated the automotive interior leather market. This is attributed to the rising demand for individual vehicles in emerging countries and the growing need for safe and comfortable travel. Additionally, the proliferation of automotive manufacturing facilities and the expansion of automotive supply chains further contribute to the demand for interior leather. Initiatives to enhance the supply chain are expected to benefit the market. The overall growth of the automotive industry, therefore, acts as a key driver for the increased use of leather in vehicle interiors. For example, the rise in the adoption of leather for automotive interiors is expected to propel the market growth. The increased consumer preference for car safety and comfort amenities is catered for by cutting-edge technologies such as advanced driver-assistance systems (ADAS).
Shift Towards Electric and Hybrid Vehicles:
The shift towards electric and hybrid vehicles is also a significant driver of the automotive interior leather market. These vehicles often emphasize advanced technology and premium features, which include high-quality interior materials. As electric and hybrid vehicles become more popular, there is a growing demand for innovative and sustainable leather solutions that complement the unique design and functionality of these vehicles. This shift is prompting manufacturers to explore new leather applications and materials that meet the specific needs of electric and hybrid vehicles, driving further growth in the automotive interior leather market. The increasing integration of leather in the interiors of next-generation vehicles underscores the market's adaptability to evolving automotive trends.
Technological Innovations in Leather Processing:
Technological innovations in leather processing are another crucial driver for the automotive interior leather market. Advances in tanning and finishing technologies have led to the development of leather with improved durability, better texture, and enhanced appearance. These innovations have made it possible to produce leather that meets the rigorous standards required for automotive applications, including resistance to wear and tear, staining, and fading. Enhanced processing techniques also enable the creation of leather with eco-friendly treatments, aligning with the industry's shift towards more sustainable practices. The continuous evolution of leather processing technologies supports the market by providing higher-quality products that cater to the growing demands of automotive manufacturers and consumers.
Market Trends:
Sustainability and Eco-Friendly Materials:
One of the prominent trends in the automotive interior leather market is the growing emphasis on sustainability and eco-friendly materials. Consumers and manufacturers alike are increasingly prioritizing environmentally responsible practices and products. This shift has led to the development and adoption of alternative materials, such as synthetic leathers and eco-tanned leathers, which aim to reduce environmental impact while meeting aesthetic and functional requirements. For instance, the rise in consumers has called for an elevation to eco-friendlier options. The market is responding with ethically sourced leather and chrome-free tanning processes that reduce the environmental impact. This would cater to a growing segment of environmentally concerned luxury car buyers. The automotive industry is responding to these demands by integrating sustainable practices into the production process, including the use of vegetable-tanned leathers and recycled materials. This trend reflects a broader movement towards greener manufacturing practices and aligns with evolving consumer preferences for products that are both high-quality and environmentally conscious.
Integration of Advanced Technologies:
The integration of advanced technologies into leather processing is transforming the automotive interior leather market. Innovations such as digital printing, advanced tanning processes, and high-tech coatings are enhancing the functionality and aesthetic appeal of automotive leather. These technologies not only improve the durability and performance of leather, but also allow for more complex and customized designs. For instance, digital printing enables the creation of intricate patterns and textures that were previously difficult to achieve. This technological advancement supports the growing demand for personalized and high-quality interiors, driving the development of new and improved leather products for automotive applications. Moreover, leather manufacturers are enthusiastically embracing advanced technologies like 3D printing and bioprinting to create custom textures and patterns. These technologies fundamentally change the design and functionality of leather products. They also utilize laser cutting for similar innovative aims.
Shift Towards Smart and Connected Interiors:
The shift towards smart and connected interiors is also influencing the automotive interior leather market. As vehicles become more integrated with digital technologies, there is a demand for leather products that complement advanced infotainment systems and interactive features. For instance, leather interiors may incorporate smart features such as integrated heating and cooling systems, massage functions, memory foam padding, and adjustable lumbar support to enhance comfort and ergonomics for vehicle occupants. The integration of smart technologies with leather upholstery is driven by the growing consumer expectation for high-tech and connected vehicle experiences. A recent survey by McKinsey found that 62% of consumers consider in-vehicle technology to be an important factor when purchasing a new car. Moreover, leather manufacturers enthusiastically embrace advanced technologies like 3D printing and bioprinting to create custom textures and patterns. These technologies fundamentally change the design and functionality of leather products. This trend includes the incorporation of embedded sensors and controls within leather surfaces, enhancing the functionality of vehicle interiors. Manufacturers are exploring innovative ways to integrate smart technologies with leather upholstery, responding to the growing consumer expectation for high-tech and connected vehicle experiences. This shift is driving innovation in the design and application of automotive leather, aligning with the broader trend of technological advancement in the automotive industry.
Growing Emphasis on Health and Safety:
An emerging trend in the automotive interior leather market is the growing emphasis on health and safety. Consumers are increasingly aware of the potential health impacts of interior materials, leading to a demand for leather products that are free from harmful chemicals and allergens. Manufacturers are responding by focusing on producing leather with hypoallergenic properties and using non-toxic treatments. This trend aligns with broader health and safety concerns, pushing the industry towards higher standards for interior materials that promote a healthier driving environment.
Market Restraints and Challenges:
High Costs of Premium Leather Materials:
One of the primary restraints in the automotive interior leather market is the high cost of premium leather materials. High-quality leather, which is often sought after for luxury vehicle interiors, comes with significant production and procurement costs. These costs can impact the overall price of vehicles, making them less accessible to budget-conscious consumers. Additionally, fluctuations in the prices of raw materials can further affect the cost stability and profitability for manufacturers, posing a challenge in maintaining competitive pricing while ensuring product quality.
Environmental and Ethical Concerns:
Environmental and ethical concerns associated with traditional leather production are significant challenges. The leather tanning process can have substantial environmental impacts, including pollution and high water usage. Growing consumer awareness and regulatory pressure are pushing for more sustainable and eco-friendly practices. This shift has led to increased demand for synthetic and alternative materials, which can present challenges for traditional leather suppliers in adapting to new market expectations and technologies.
Competition from Synthetic Alternatives:
The rise of synthetic leather alternatives presents a substantial challenge to the traditional automotive interior leather market. Synthetic leathers, such as polyurethane (PU) and vinyl, offer lower costs and can be produced with less environmental impact compared to natural leather. These alternatives are increasingly popular due to their affordability, ease of maintenance, and growing acceptance among consumers who prioritize sustainability. As a result, traditional leather manufacturers must innovate and differentiate their products to remain competitive.
Supply Chain Disruptions:
Supply chain disruptions pose a significant challenge to the automotive interior leather market. The industry is vulnerable to interruptions in the supply of raw materials due to geopolitical tensions, trade restrictions, and logistical issues. These disruptions can lead to delays, increased costs, and difficulties in meeting production schedules. Ensuring a stable and reliable supply chain is crucial for maintaining market stability and meeting the demands of automotive manufacturers and consumers.
Market Segmentation Analysis:
By Material Type
The automotive interior leather market is segmented by material type into genuine leather, synthetic leather, and semi-aniline leather. Genuine leather remains the preferred choice for luxury and high-end vehicles due to its superior quality, durability, and premium feel. Synthetic leather, which includes polyurethane (PU) and vinyl, is increasingly popular due to its cost-effectiveness, ease of maintenance, and environmentally friendly options. Semi-aniline leather, which offers a balance between natural and processed leather, is favored for its enhanced durability while maintaining a high-quality appearance. Each material type caters to different market segments, with genuine leather dominating the luxury segment and synthetic leather gaining traction in more affordable vehicle categories.
By Vehicle Type
Segmenting by vehicle type, the automotive interior leather market includes passenger cars, SUVs, and commercial vehicles. Passenger cars hold the largest market share, driven by consumer preference for high-quality and aesthetically pleasing interiors. The SUV segment is experiencing growth due to rising demand for luxury and premium features in these vehicles. Commercial vehicles, including trucks and buses, are also incorporating leather interiors to enhance comfort and durability, although this segment represents a smaller portion of the market.
By Car Class
The market is further segmented by car class into luxury, mid-range, and economy cars. Luxury cars use high-grade leather to provide a premium driving experience, making this segment the largest consumer of high-quality leather. Mid-range cars often feature a mix of genuine and synthetic leather, balancing cost and quality. Economy cars predominantly use synthetic leather or lower-grade genuine leather to keep costs low while still providing a functional and attractive interior.
By Sales Channel
The automotive interior leather market is divided by sales channel into OEM (original equipment manufacturer) and aftermarket segments. OEMs account for a significant portion of the market as vehicle manufacturers integrate leather into their production processes. The aftermarket segment, which includes automotive upholstery and customization services, is growing due to increased consumer interest in vehicle personalization and upgrades. This segment provides additional opportunities for leather suppliers to cater to individual preferences and specialized applications.
Segmentation:
By Material Type
- Genuine leather
- Synthetic leather
- Semi-aniline leather
By Vehicle Type
- Passenger cars
- SUVs,
- Commercial vehicles
By Car Class
- Luxury
- Mid-range
- Economy cars
By Sales Channel
- OEM (original equipment manufacturer)
- Aftermarket segments
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
The automotive interior leather market exhibits varying growth patterns across different regions, each influenced by unique economic, consumer, and automotive industry dynamics.
North America North America holds a significant share of the global automotive interior leather market, accounting for approximately 35%. The region's dominance is driven by high consumer demand for luxury and premium vehicles, which often feature high-quality leather interiors. The strong presence of major automotive manufacturers and the focus on advanced interior features contribute to market growth. Additionally, stringent regulations on vehicle interiors and safety standards further drive demand for premium leather products. The U.S. and Canada, with their developed automotive industries and high disposable incomes, continue to lead in both production and consumption of automotive leather.
Europe Europe is another key region, representing around 30% of the global market. The region benefits from a robust automotive sector and a significant presence of premium and luxury vehicle manufacturers, including brands like BMW, Mercedes-Benz, and Audi. Europe's stringent environmental regulations and high standards for vehicle interiors drive the demand for high-quality and sustainable leather materials. Countries such as Germany, France, and the United Kingdom are major contributors, supported by their strong automotive heritage and consumer preference for premium interiors. The emphasis on eco-friendly and ethically sourced materials is also a notable trend in this region.
Asia-Pacific The Asia-Pacific region is experiencing rapid growth and currently holds about 25% of the market share. This growth is fueled by increasing automotive production and rising disposable incomes in countries like China and India. The expanding middle class and growing preference for luxury and high-end vehicles in these countries drive demand for premium interior materials. Additionally, the region's automotive industry is evolving with advancements in production technologies and the increasing adoption of electric vehicles, which further stimulates demand for innovative leather solutions. The Asia-Pacific market is poised for significant growth as the automotive sector continues to expand and evolve.
Latin America and Middle East & Africa Latin America and the Middle East & Africa collectively account for approximately 10% of the global automotive interior leather market. In Latin America, market growth is driven by rising vehicle ownership and improving economic conditions, particularly in countries like Brazil and Mexico. The Middle East & Africa are witnessing growth due to increasing investments in automotive infrastructure and a rising preference for luxury vehicles in the region. Both areas present emerging opportunities as automotive markets expand and consumer preferences evolve.
Key Player Analysis:
- Alfatex Italia
- Alphaline auto
- Bader GmbH & Co. KG
- BOXMARK Leather GmbH & Co
- Classic soft trim
- CTL leather
- K Leather Corporation,
- Eagle Ottawa LLC,
- Elmo Sweden AB,
- GST Autoleather Inc
- Katzkin Leather Inc
- Kuraray plastics
- Lear Corporation
- Midori Auto Leather,
- Nan Ya Plastics Corporation,
- Pasubio, San Fang Chemical Industry Co., Ltd,
- Scottish leather group
- Seiren Co Ltd
- Tata International Ltd.
- Wollsdorf leder schmidt & Co
Competitive Analysis:
The automotive interior leather market is highly competitive, with several leading players driving industry dynamics. Major companies such as Lear Corporation and Adient dominate the market by leveraging their technological advancements and extensive global networks. These leaders focus on enhancing product quality and incorporating innovative materials, including sustainable and synthetic options, to meet evolving consumer preferences and regulatory requirements. Competitive strategies also involve partnerships and collaborations to expand market reach and develop new technologies. Emerging players are carving out niches by offering specialized products and cost-effective solutions. Additionally, the market is influenced by trends such as increasing demand for luxury interiors and advancements in leather processing technologies. Overall, competition is driven by the need for continuous innovation, high-quality standards, and responsiveness to consumer and environmental demands, making the market both dynamic and challenging.
Recent Developments:
- In July 2024, Lear Corporation, a global leader in automotive technology specializing in Seating and E-systems, finalized its acquisition of WIP Industrial Automation. Based in Spain, WIP is renowned for its development, integration, and deployment of advanced technologies tailored to production automation.
- In August 2023, Katzkin Leather, a top provider of premium automotive leather solutions, announced it had acquired the assets of Roadwire Leather's business. This strategic acquisition enhances Katzkin's capacity to serve a broad customer base, including original equipment manufacturers (OEMs), dealerships, and numerous restylers, benefiting millions of consumers using Katzkin-equipped vehicles.
- In September 2023, Scottish Leather Group, a key supplier for luxury brands such as Aston Martin and Jaguar Land Rover, as well as British Airways, launched its groundbreaking $17.9 billion 'super tannery' in Bridge of Weir, Scotland. This state-of-the-art facility aims to produce leather with a net-zero carbon footprint, catering to diverse industries including automotive, aviation, and luxury goods.
Market Concentration & Characteristics:
The automotive interior leather market exhibits moderate to high concentration, with a few major players dominating the industry. Key players include companies such as Lear Corporation and Adient which leverage their extensive experience and technological expertise to capture significant market share. The market is characterized by high competition among these major suppliers, who focus on innovation, quality, and customer relationships to maintain their positions. Additionally, the market features a growing presence of specialized suppliers providing niche products, such as eco-friendly and synthetic leather options. The automotive interior leather market is also influenced by stringent regulatory standards and evolving consumer preferences, which drive the demand for high-quality and sustainable materials. As a result, manufacturers continually adapt their offerings to meet safety, performance, and environmental requirements, ensuring the market remains dynamic and competitive.
Report Coverage:
The research report offers an in-depth analysis based on by material type, by vehicle type, by car class and by sales channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The automotive interior leather market is expected to expand significantly, driven by increasing consumer demand for luxury and high-quality vehicle interiors.
- Technological advancements in leather processing will enhance product durability, texture, and environmental sustainability.
- The shift towards eco-friendly and sustainable materials will accelerate, with growing adoption of plant-based and recycled leather alternatives.
- Integration of advanced features in vehicles, such as smart and connected interiors, will drive demand for innovative leather applications.
- The rise in electric and hybrid vehicles will lead to increased use of high-performance, lightweight leather materials.
- The luxury vehicle segment will continue to be a major driver, with premium leather maintaining a strong market presence.
- Emerging markets, particularly in Asia-Pacific, will contribute to market growth due to rising disposable incomes and automotive production.
- Increasing regulatory pressures and consumer preference for non-toxic, hypoallergenic materials will influence market dynamics.
- The aftermarket segment will grow as consumers seek personalized and upgraded vehicle interiors.
- Competitive pressures will drive manufacturers to innovate and offer differentiated leather products to capture market share.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the automotive interior leather market?
What drives the automotive interior leather market?
Which regions are leading the market?
What are the challenges facing the automotive interior leather market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Interior Leather Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Interior Leather Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 23,069 million → 2032: USD 33,567.5 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Interior Leather Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Interior Leather Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Interior Leather Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Interior Leather Market Drivers
- 3.3 Automotive Interior Leather Market Restraints & Challenges
- 3.4 Automotive Interior Leather Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Interior Leather Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Interior Leather Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Interior Leather category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Interior Leather Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Interior Leather Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Interior Leather market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Interior Leather Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Interior Leather Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Interior Leather Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Interior Leather (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Interior Leather Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Interior Leather Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Interior Leather Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Interior Leather Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Interior Leather Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Interior Leather Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Interior Leather Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Interior Leather Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Interior Leather Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
