
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Sunroof Market Size 2023 | USD 12500 million |
| Automotive Sunroof Market, CAGR | 12.4% |
| Automotive Sunroof Market Size 2032 | USD 31844.94 million |
Market Overview:
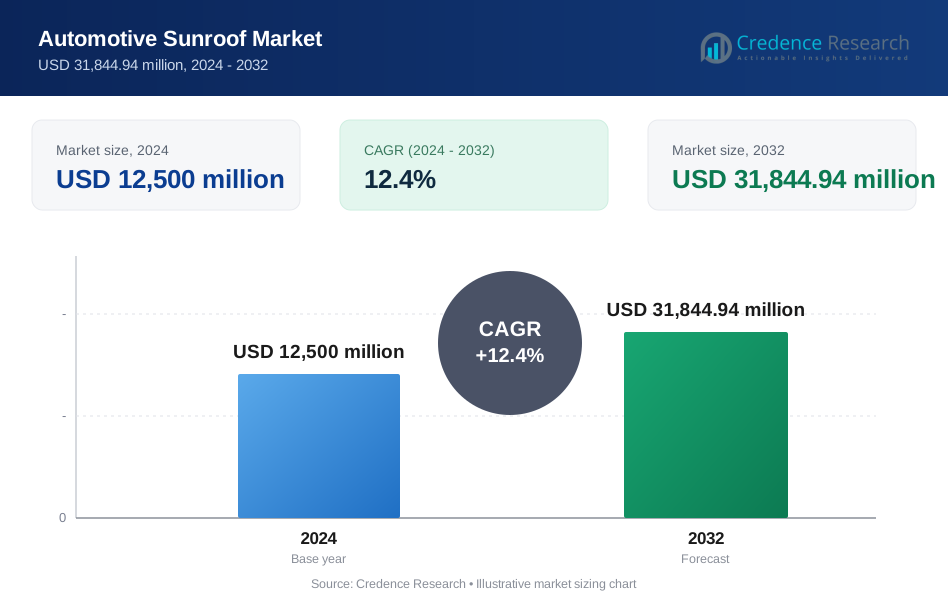
The Automotive Sunroof Market is projected to grow from USD 12500 million in 2024 to an estimated USD 31844.94 million by 2032, with a compound annual growth rate (CAGR) of 12.4% from 2024 to 2032.
The demand for automotive sunroofs is driven by several key factors. Firstly, there is a noticeable consumer shift toward vehicles with advanced features, as sunroofs are increasingly associated with luxury and a higher-end driving experience. Moreover, the growth in the automotive industry, coupled with higher disposable incomes in developing economies, has fostered a greater willingness to invest in cars with additional comfort and design features. Technological advancements, such as the development of solar sunroofs for EVs and panoramic sunroofs with UV protection, also support this trend. Additionally, government initiatives encouraging EV adoption have indirectly boosted sunroof adoption, particularly in EV models with enhanced sunroof capabilities for energy efficiency.
Regionally, the automotive sunroof market is predominantly led by Asia-Pacific, which holds a significant market share due to the strong automotive manufacturing base in countries like China, Japan, and South Korea. This region benefits from a high demand for premium vehicles and a large base of cost-effective manufacturing operations. North America follows closely, driven by a steady rise in EV sales and consumer preference for vehicles with enhanced features. Europe, with its strong emphasis on innovation and sustainable automotive solutions, also remains a key player, especially in the luxury vehicle segment. The Middle East and Africa are emerging markets where sunroof adoption is growing due to increased vehicle imports and a rising middle-class population.
Market Drivers:
Rising Consumer Demand for Enhanced Vehicle Aesthetics and Comfort:
One of the primary drivers of growth in the automotive sunroof market is the rising consumer preference for vehicles with enhanced aesthetics and added comfort features. Sunroofs are increasingly associated with luxury and sophistication, and they elevate the driving experience by providing an open and spacious feel. For instance, Hyundai reported that models equipped with sunroofs saw a significant increase in sales, particularly in the Indian market. As consumers are willing to invest in vehicles that offer more than just basic functionality, automakers are incorporating sunroofs to attract this segment of buyers. Additionally, with the growing trend of long-distance travel and road trips, the demand for features that enhance the in-car experience, like panoramic and adjustable sunroofs, has surged. As a result, sunroof installations are moving beyond the luxury segment and becoming more common in mid-range and even entry-level vehicles.
Technological Advancements in Glass and Sunroof Design:
The automotive sunroof market is significantly driven by advancements in glass technology and sunroof design, which have expanded the applications and functionalities of sunroofs. Modern sunroof designs include panoramic, tilting, sliding, and even solar sunroofs, which not only provide aesthetic appeal but also serve functional purposes. For instance, solar sunroofs are becoming popular in electric vehicles (EVs) as they help harness solar energy, thereby enhancing vehicle efficiency and range. Additionally, innovations in tempered glass and laminated glass have improved the durability and safety of sunroofs, even in harsh weather conditions. These advancements are encouraging automakers to incorporate sunroofs more widely, as they no longer pose the structural or safety limitations of earlier designs.
Growing Electric Vehicle Adoption Boosts Sunroof Demand:
The global shift toward electric vehicles is another significant driver for the automotive sunroof market. Governments worldwide are implementing regulations and incentives to promote EV adoption, which has resulted in increased production and sales of EVs across major markets. Electric vehicle manufacturers are continually seeking ways to improve the energy efficiency of their models, and solar sunroofs offer a valuable solution. By using solar panels embedded in the sunroof, EVs can generate supplemental energy, reducing reliance on charging infrastructure. Additionally, EVs are marketed as technologically advanced and environmentally friendly, and sunroofs contribute to this image, making them a desirable feature. This factor has led many EV manufacturers to offer sunroof options as standard or optional features, further propelling market growth.
Higher Disposable Incomes and Vehicle Ownership in Emerging Markets:
Emerging economies, particularly in Asia-Pacific, are witnessing an increase in disposable incomes and vehicle ownership, which has created a fertile ground for the automotive sunroof market. Countries like China, India, and South Korea have large populations of young, middle-class consumers who are increasingly inclined toward premium features in vehicles. With greater spending power, these consumers are opting for models with advanced features like sunroofs, driving demand in these regions. Additionally, many of these economies serve as major hubs for automotive production and export, facilitating cost-effective sunroof installation across various vehicle segments. This growth in emerging markets underscores a shift in consumer preferences toward vehicles that combine functionality with luxury, thereby sustaining the demand for automotive sunroofs globally.
Market Trends:
Increased Adoption of Panoramic Sunroofs Across Vehicle Segments:
The automotive sunroof market is witnessing a notable trend toward panoramic sunroofs, which have become a popular choice across various vehicle segments. Initially limited to luxury vehicles, panoramic sunroofs are now being integrated into mid-range and even compact cars as automakers respond to growing consumer demand for enhanced in-car experiences. Panoramic sunroofs, which extend over the entire roof of the vehicle, provide a more immersive driving experience and allow greater natural light into the cabin, creating an open, spacious feel. For instance, the Hyundai Tucson offers a Voice Enabled Smart Panoramic Sunroof as a feature, demonstrating the integration of this technology in popular SUV models. This trend is particularly strong among younger consumers who prioritize aesthetics and advanced features, making panoramic sunroofs a significant selling point for automakers.
Advances in Solar-Powered Sunroof Technology for Electric Vehicles (EVs):
A growing emphasis on sustainability and energy efficiency in the automotive industry has spurred interest in solar-powered sunroof technology, especially for electric vehicles (EVs). Solar sunroofs, which incorporate photovoltaic cells to convert sunlight into electricity, are increasingly being explored as a means of extending EV range. This technology not only supports the energy needs of the vehicle but also aligns with the eco-friendly image of EVs. Leading automakers and technology firms are investing in the development of efficient, lightweight solar panels that can seamlessly integrate into vehicle roofs. For instance, in February 2023, Indian startup Vayve Mobility announced that it would launch a solar-powered electric car Eva in 2024. The electric vehicle contains 150-watt solar panels on the sunroof that can give it 10-12 km of range every day - or 3,000 km a year. As a result, solar-powered sunroofs are expected to become a prominent feature in EV models, further driving demand in the automotive sunroof market.
Rise in Aftermarket Sunroof Installations Driven by Customization Trends:
The demand for aftermarket sunroof installations is also on the rise, as consumers seek to personalize their vehicles with features that enhance aesthetics and comfort. This trend is particularly prevalent in regions with a strong car customization culture, such as North America and parts of Asia. With a wide range of aftermarket options now available, including panoramic and tinted sunroofs, consumers can easily modify their vehicles to include a sunroof even if it was not part of the original design. Additionally, the aftermarket sector offers cost-effective options, allowing consumers to access sunroof features without purchasing a new vehicle. This trend is contributing to the growth of the automotive sunroof market, especially in the aftermarket segment.
Integration of Smart Sunroof Features for Enhanced User Experience:
Automakers are increasingly integrating smart features into sunroofs to enhance user experience and align with the trend toward connected vehicles. Modern sunroofs now come equipped with advanced functionalities such as voice or touch controls, automatic tinting, and rain-sensing technology, which closes the sunroof automatically in case of rainfall. These smart features are particularly appealing in the premium and luxury segments, where consumers seek vehicles with high-tech amenities. The integration of such features not only enhances the functionality of sunroofs but also aligns with the broader trend of smart and connected cars. As these technologies become more affordable, smart sunroof features are expected to spread to mid-range vehicles, thereby boosting market demand.
Market Restraints and Challenges:
High Costs and Limited Affordability for Entry-Level Vehicles:
One of the major challenges in the automotive sunroof market is the high cost associated with sunroof installation, which limits its affordability for entry-level and budget-conscious consumers. Sunroofs, particularly advanced types like panoramic and solar-powered variants, require specialized materials and complex engineering, driving up production costs. This makes it difficult for automakers to incorporate sunroofs in low-cost vehicle models without significantly impacting profit margins or raising the vehicle’s overall price. Consequently, sunroof adoption remains more prevalent in premium and mid-range vehicles, creating a potential barrier to market growth among price-sensitive consumer segments.
Safety and Structural Integrity Concerns:
Concerns about the safety and structural integrity of vehicles with sunroofs pose another challenge for the market. The addition of a sunroof can impact a vehicle’s structural strength, which is particularly important in the event of a rollover or severe impact. Additionally, poorly installed or lower-quality sunroofs can lead to issues such as leaks, wind noise, and glass breakage. These risks have led some consumers to be cautious about opting for sunroofs, especially in areas with extreme weather conditions. Automakers and sunroof manufacturers must address these safety concerns by investing in high-quality materials and innovative designs that enhance structural durability to mitigate this restraint.
Weather Dependence and Limited Utility in Certain Climates:
The utility of sunroofs is limited in regions with extreme climates, where harsh weather conditions reduce their appeal. In areas with high temperatures, sunroofs may increase cabin heat, causing discomfort and necessitating greater air conditioning use. Conversely, in regions with frequent heavy rain or snowfall, sunroofs may remain closed most of the time, diminishing their practical value. This weather dependence creates variability in demand, which can hinder market growth, especially in regions where climate reduces the appeal of sunroof installations.
Market Segmentation Analysis:
The automotive sunroof market can be segmented by vehicle class, propulsion type, material type, product type, and operation type, with each segment reflecting unique trends and consumer preferences.
By Vehicle Class, luxury vehicles hold the largest share due to higher consumer willingness to pay for premium features, while medium-priced vehicles are also adopting sunroofs as they become more accessible and in demand among mid-range buyers. Economical vehicles have lower adoption rates due to the cost-sensitive nature of this segment, though aftermarket options are gradually making sunroofs accessible here.
By Propulsion Type, internal combustion engine (ICE) vehicles currently dominate the market, as they still make up the majority of vehicle sales globally. However, the electric vehicle (EV) segment is growing rapidly, driven by the demand for solar-powered sunroofs that can enhance EV efficiency and sustainability.
By Material Type, glass sunroofs are preferred for their aesthetic appeal, durability, and ability to provide panoramic views, while fabric sunroofs are used in smaller or entry-level models due to lower cost and simpler design.
By Product Type, panoramic sunroofs are gaining popularity across all classes, thanks to their spacious feel, while in-built sunroofs remain common in compact and mid-size vehicles. Other types, like tilt-and-slide, pop-up, and top-mount sunroofs, cater to specific consumer preferences for ventilation and style.
By Operation Type, electric sunroofs lead the market due to the convenience and seamless experience they provide, while manual options are typically seen in lower-cost or economical vehicle models.
Segmentation:
By Vehicle Class
- Economical
- Medium Priced
- Luxury
By Propulsion Type
- ICE
- Electric
By Material Type
- Glass
- Fabric
By Product Type
- Panoramic Sunroofs
- In-Built Sunroof
- Others (Tilt & Slide, Pop Up, and Top Mount)
By Operation Type
- Electric
- Manual
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The automotive sunroof market shows significant regional variations, with demand driven by distinct economic factors, consumer preferences, and climatic conditions across key markets. Asia-Pacific, North America, Europe, and the Middle East & Africa are the primary regions contributing to the global market share, each with its unique trends and growth drivers.
Asia-Pacific holds the largest share of the automotive sunroof market, accounting for over 35% of the global market. The region’s dominance can be attributed to its robust automotive manufacturing base and the rising disposable incomes in emerging economies like China and India. With a strong presence of both domestic and international automakers, Asia-Pacific benefits from economies of scale that make sunroofs accessible across various vehicle classes. Additionally, there is a growing consumer preference for premium vehicles with advanced features, making sunroofs a popular choice among middle- and high-income consumers. As electric vehicles gain traction, particularly in China, demand for solar-powered sunroofs is expected to drive further market expansion in the region.
North America accounts for approximately 25% of the global automotive sunroof market, driven by a well-established automotive sector and consumer interest in vehicle customization and comfort features. The U.S. and Canada are major contributors, with a high demand for larger vehicles like SUVs and crossovers, which often include panoramic or in-built sunroofs. Additionally, the popularity of electric vehicles in North America supports growth in the sunroof market, particularly as leading EV manufacturers introduce models with sunroof options. The region also benefits from a vibrant aftermarket segment, where consumers often add sunroofs as an upgrade to personalize their vehicles.
Europe holds around 20% of the market share, with strong demand for automotive sunroofs driven by a preference for premium and luxury vehicles, particularly in countries like Germany, France, and the UK. European consumers place a high value on design and technology, and automakers in the region respond by offering advanced sunroof features, such as panoramic and solar sunroofs, especially in high-end models. The strong focus on sustainability and the growing penetration of electric vehicles across Europe are expected to drive demand for solar-powered sunroofs. Moreover, regulations promoting energy-efficient technologies have encouraged automakers to integrate sunroofs that enhance energy savings.
The Middle East & Africa and Latin America together account for the remaining 20% of the market share. In the Middle East, sunroofs are popular due to the high demand for luxury vehicles, though harsh climate conditions limit their practical use. Nevertheless, wealthy consumers in countries like the UAE and Saudi Arabia see sunroofs as a desirable feature, often included in luxury and high-end models. In Latin America, growth is slower but gradually rising due to the increasing vehicle sales in Brazil, Argentina, and Mexico, where middle-class consumers show interest in premium features like sunroofs as their disposable incomes grow.
Key Player Analysis:
- AISIN CORPORATION
- CIE Automotive
- DONGHEE
- Inalfa Roof Systems Group B.V.
- Inteva Products
- Johnan Manufacturing Inc.
- Magna International Inc.
- Webasto Group
- Wuxi Ming Fang AutoMobile Parts
- Yachiyo Industry Co. Ltd
Competitive Analysis:
The automotive sunroof market is characterized by intense competition among key players, including Webasto Group, Inalfa Roof Systems, CIE Automotive, and Inteva Products, each vying for a strong market position through innovation and strategic partnerships. Webasto Group and Inalfa Roof Systems hold a significant market share due to their extensive product portfolios and global manufacturing networks, which allow them to cater to diverse vehicle segments from luxury to economical. Companies are heavily investing in research and development to introduce advanced sunroof technologies, such as solar-powered and panoramic designs, catering to the growing electric vehicle market. Partnerships with automotive OEMs to deliver integrated, high-quality solutions provide a competitive advantage, as does their ability to offer cost-effective products in emerging markets. The focus on durability, energy efficiency, and consumer safety continues to drive competition, as companies aim to address key challenges in sunroof adoption.
Recent Developments:
- In June 2024, Hyundai, headquartered in Seoul, launched the Inster EV, an electric version of its Casper ICE vehicle, equipped with a single-pane sunroof.
- In February 2023, India-based Vayve Mobility announced plans to launch Eva, a solar-powered electric car featuring 150-watt solar panels integrated into its sunroof, providing a daily range of 10 to 12 km, or an annual range of around 3,000 km.
- In May 2023, Gabrial India signed an agreement with Inalfa Roof Systems to manufacture sunroofs for SUVs and sedans. The company committed USD 20.7 million to establish a greenfield facility in Chennai, Tamil Nadu, set to become operational in early 2024, with an initial capacity of 200,000 sunroofs annually.
- Also, in May 2023, Webasto Group inaugurated a second sunroof production plant in India. The Chennai facility, with a capacity of 250,000 units per year, spans 9,500 square meters and will produce panoramic roofs for customers across Southern India.
- In August 2022, Gentex invested USD 300 million to expand its Zeeland, Michigan operations, supported by the Michigan Strategic Fund. This expansion includes a new high-tech facility and increased glass processing, auto-dimming mirrors, displays, and electronics capacity, adding 500 jobs to its Michigan workforce.
- In July 2022, Inteva Products announced plans to establish a second engineering technical center in Mexico to better support regional automotive manufacturers and expand its existing technical and manufacturing footprint.
Market Concentration & Characteristics:
The automotive sunroof market exhibits a moderate level of concentration, with a few key players holding a significant share due to strong partnerships with major automotive OEMs and a focus on innovation. Companies such as Webasto Group, Inalfa Roof Systems, and Inteva Products dominate the market by leveraging their extensive manufacturing capacities and advanced sunroof technologies, including panoramic and solar-powered options. The market is characterized by high demand for premium features across both traditional and electric vehicles, driving innovation in sunroof design and functionality. Advancements in smart technologies, such as rain-sensing and automatic tinting sunroofs, also highlight the sector’s shift toward consumer convenience and safety. While larger firms maintain their lead through technology and scale, regional players in emerging markets like India and China are expanding their presence, creating a dynamic market landscape that balances both global dominance and regional growth.
Report Coverage:
The research report offers an in-depth analysis based on By Vehicle Class. By Propulsion Type. By Material Type, By Product Type and By Operation Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The automotive sunroof market is projected to grow significantly, driven by rising consumer demand for premium vehicle features.
- Advancements in solar-powered sunroofs are expected to gain traction, particularly with the growth of electric vehicles (EVs).
- Panoramic sunroofs will continue to dominate, appealing to consumers across all vehicle segments for their aesthetic and spacious feel.
- Emerging markets, particularly in Asia-Pacific, will see accelerated adoption due to rising incomes and consumer preference for advanced vehicle features.
- Increased focus on lightweight, durable materials will improve sunroof efficiency and safety, meeting both regulatory standards and consumer expectations.
- Integration of smart technologies, such as voice control and automatic tinting, will enhance user experience and align with the trend of connected vehicles.
- Environmental concerns will encourage automakers to develop energy-efficient sunroofs that reduce reliance on air conditioning.
- Rising demand in the aftermarket segment will allow existing car owners to upgrade their vehicles with sunroof options.
- Manufacturers are likely to expand production capabilities, particularly in regions like India, to meet growing demand and reduce costs.
- Strategic collaborations between sunroof manufacturers and automakers will drive innovation and expand product offerings in the coming years.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Consumer Preference for Enhanced Vehicle Features
Consumers increasingly associate sunroofs with luxury, comfort, and a premium driving experience, prompting automakers to offer sunroofs across more vehicle segments, including mid-range and entry-level models.
Technological Advancements in Sunroof Design
Innovations such as panoramic, solar-powered, and smart sunroofs with features like automatic tinting and rain sensors have expanded the appeal and functionality of sunroofs, making them more attractive to both OEMs and consumers.
Growth of Electric Vehicles and Solar Sunroof Integration
The rising adoption of electric vehicles has driven demand for solar sunroofs, which can supplement vehicle energy needs and enhance the eco-friendly image of EVs, encouraging manufacturers to integrate sunroofs as standard or optional features.
Rising Disposable Incomes in Emerging Markets
Increasing disposable incomes and vehicle ownership in emerging economies, especially in Asia-Pacific, are enabling more consumers to opt for vehicles with advanced features like sunroofs, fueling market expansion in these regions.
Aftermarket Customization Trends
A growing culture of vehicle personalization, particularly in North America and Asia, is boosting the aftermarket sunroof segment, allowing owners of existing vehicles to upgrade with sunroof installations and further driving overall market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the automotive sunroof market?
What are the main drivers of demand for automotive sunroofs?
Which region has the largest market share in the automotive sunroof market?
What are the primary challenges facing the automotive sunroof market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Panoramic Sunroofs
- 1.2.2 In-Built Sunroof
- 1.2.3 Others (Tilt & Slide, Pop Up, Top Mount)
- 1.3 By Vehicle Class
- 1.3.1 Economical
- 1.3.2 Medium Priced
- 1.3.3 Luxury
- 1.4 By Operation Type
- 1.4.1 Electric
- 1.4.2 Manual
- 1.5 By Propulsion Type
- 1.5.1 ICE
- 1.5.2 Electric
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,500 million → 2032: USD 31,844.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Sunroof Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Sunroof Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Sunroof Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Sunroof Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Sunroof Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Sunroof Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Sunroof Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Sunroof Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,500 million → 2032: USD 31,844.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Sunroof Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Panoramic Sunroofs
- 12.3.7.2 In-Built Sunroof
- 12.3.7.3 Others (Tilt & Slide, Pop Up, Top Mount)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Class - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Economical
- 12.4.7.2 Medium Priced
- 12.4.7.3 Luxury
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Operation Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electric
- 12.5.7.2 Manual
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Propulsion Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 ICE
- 12.6.7.2 Electric
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Sunroof Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Sunroof Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Sunroof Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Webasto Group
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Inalfa Roof Systems Group B.V.
- 17.4 Inteva Products
- 17.5 CIE Automotive
- 17.6 AISIN CORPORATION
- 17.7 Magna International Inc.
- 17.8 DONGHEE
- 17.9 Yachiyo Industry Co. Ltd
- 17.10 Wuxi Ming Fang AutoMobile Parts
- 17.11 Johnan Manufacturing Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

