
Market Overview:
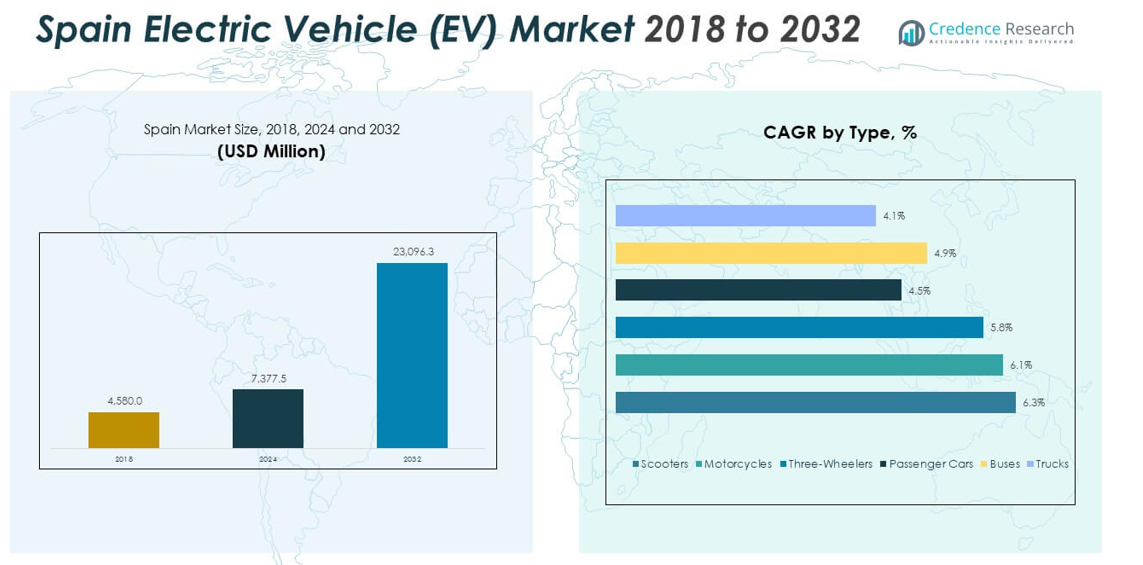
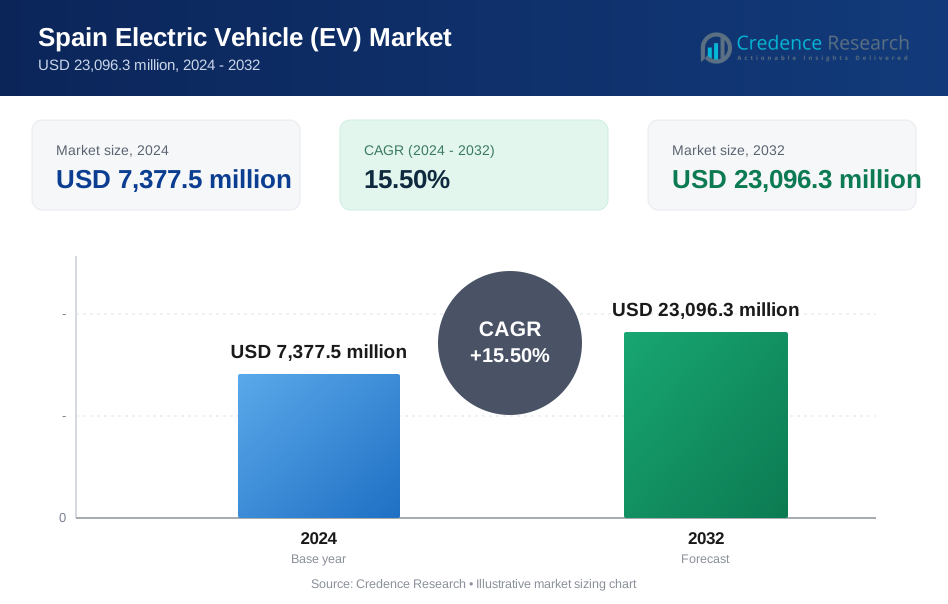
The Spain Electric Vehicle (EV) Market size was valued at USD 4,580.0 million in 2018 to USD 7,377.5 million in 2024 and is anticipated to reach USD 23,096.3 million by 2032, at a CAGR of 15.50% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Spain Electric Vehicle (EV) Market Size 2024 | USD 7,377.5 million |
| Spain Electric Vehicle (EV) Market, CAGR | 15.50% |
| Spain Electric Vehicle (EV) Market Size 2032 | USD 23,096.3 million |
Spain sees rapid EV adoption as buyers seek cleaner transport options and lower running costs. Government incentives lift demand for battery-powered models across urban and suburban zones. Carmakers expand local supply chains to meet new targets and promote fresh models. Charging networks grow across highways and major cities, which encourages longer trips. Fleet owners adopt electric vans and cars to meet emission rules and improve brand image. Strong focus on sustainability helps raise awareness and supports long-term uptake.
Spain leads EV momentum in Southern Europe due to fast charger rollout, strong tourism traffic, and active mobility policies across major cities like Madrid and Barcelona. Neighboring France and Portugal emerge as supporting markets that strengthen cross-border charging access and regional EV travel. Northern European nations remain the mature leaders, driven by early-stage investments, dense infrastructure, and advanced consumer adoption. Rising interest in Central and Eastern Europe shows the next wave of expansion as new incentives and green transport goals gain pace.
Market Insights:
- The Spain Electric Vehicle (EV) Market grew from USD 4,580.0 million in 2018 to USD 7,377.5 million in 2024 and is forecast to reach USD 23,096.3 million by 2032 at a 50% CAGR, driven by cleaner mobility demand and expanding charging networks.
- Central Spain leads with about 42% share, supported by dense charging access and strict low-emission policies; Catalonia holds nearly 33%, driven by tourism and urban adoption; Southern & Northern regions account for 25%, strengthened by cross-regional charging corridors.
- The fastest-growing region is Andalusia, holding part of the 25% share, due to rising tourism-based EV rentals, new highway charging clusters, and growing sustainability initiatives across major cities.
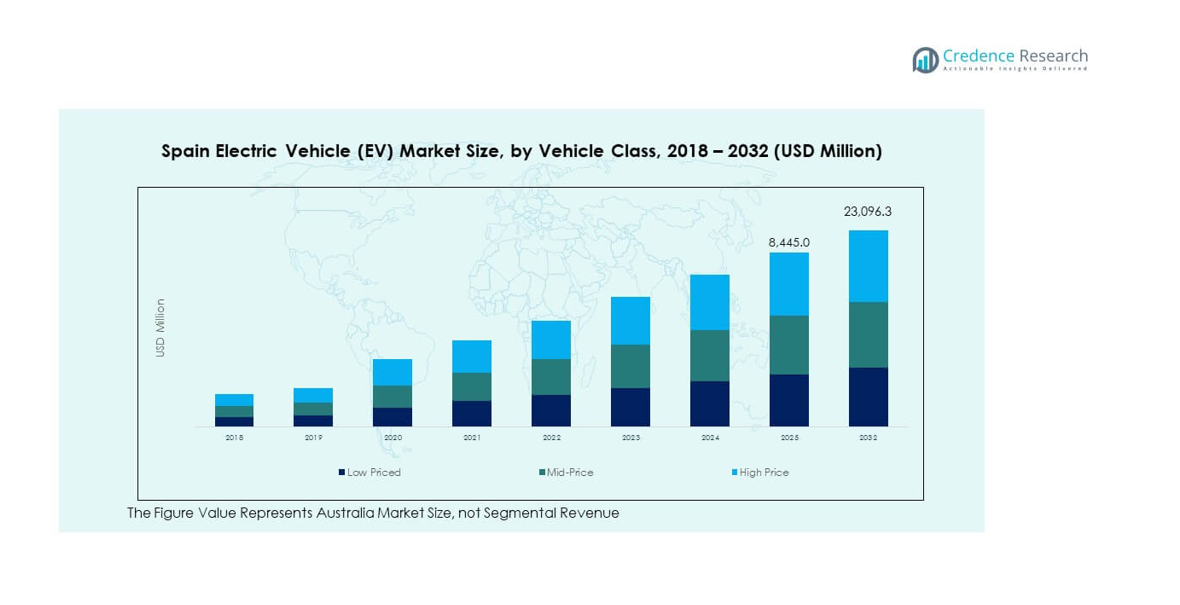
- In the vehicle-class mix for 2024, mid-price EVs account for roughly 38% of the Spain Electric Vehicle (EV) Market, supported by strong model availability and mainstream household demand.
- High-price EVs contribute an estimated 32%, lifted by premium brands and faster adoption in Madrid and Barcelona, while low-priced EVs represent about 30%, serving cost-sensitive buyers and small urban commuters.
Market Drivers:
Strong Regulatory Push Through National and Regional Mobility Policies
The Spain Electric Vehicle (EV) Market gains steady traction through firm policy pressure that drives cleaner mobility. National rules support purchase grants that reduce upfront costs for buyers. Regional cities promote low-emission zones that restrict older cars and lift EV appeal. Charging pathways expand in high-traffic corridors, which supports wider travel. Carmakers launch new models with better range to meet compliance targets. Fleet operators shift to EV vans to meet strict emission rules. Awareness campaigns highlight long-term savings for urban drivers. This push helps the market build consistent growth.
- For instance, under the national MOVES III programme the government offers grants up to €7,000 for new BEVs priced under €45,000, or €4,500 without scrapping older vehicles.
Rising Interest in Zero-Emission Transport Across Households and Businesses
Spanish households adopt electric cars to cut fuel costs and reduce pollution. Buyers prefer EVs for smooth driving and lower maintenance needs. Urban families switch to compact EV models for daily trips. Businesses deploy EV units to strengthen sustainability goals and meet client expectations. Charging access grows in offices and retail areas, which boosts user comfort. The Spain Electric Vehicle (EV) Market gains support from rising EV leasing plans. Local brands expand service centers to reduce downtime for users. Strong national focus on cleaner air lifts long-term EV demand.
- For instance, new registrations of EVs in Spain jumped 45.1% in the first quarter of 2025 compared to the previous year, totalling 44,903 units.
Expansion of Charging Networks Across Cities, Highways, and Tourist Zones
Charging expansion plays a major role in Spain’s EV rise. New public chargers appear in malls, service stations, and local centers. Highways add fast chargers that support long-distance travel. Tourist regions deploy chargers to serve rental fleets and hotel guests. Municipal projects place stations near parking hubs to lift ease of use. Private firms install smart chargers that support load management. The Spain Electric Vehicle (EV) Market benefits from wider coverage that reduces range fear. This network expansion lifts trust among new buyers and supports faster uptake.
Growing EV Manufacturing, Local Assembly, and Supply Chain Strengthening
Spain sees active steps toward EV manufacturing and local assembly. Factories adopt new lines to produce electric models with higher efficiency. Local suppliers invest in battery-pack units and drive system parts. Logistics hubs support faster transport of EV components across regions. Workforce training supports fresh roles in electric mobility. The Spain Electric Vehicle (EV) Market gains strength through rising local production. Partnerships between global brands and Spanish plants lift technology exchange. This industrial build-out helps Spain improve long-term EV scale.
Market Trends:
Shift Toward Advanced Battery Packs With Higher Density and Faster Charging
The market moves toward battery packs that support longer range and quicker charging. Producers introduce new chemistries with better durability. Buyers choose cars that allow shorter charging stops during long trips. Urban fleets rely on stable battery performance for day-to-day routes. Energy firms deploy fast chargers that match next-gen battery needs. The Spain Electric Vehicle (EV) Market gains confidence through improved charging speeds. New platforms support safer thermal control for heavy use. These advances help grow trust among early and mainstream buyers.
- For instance, Europe-wide data show that 60–80 kWh battery packs captured about 39.25% of the EV battery-pack market in 2024, highlighting a strong shift toward mid-capacity packs.
Rise of Smart Mobility Services Linked With Electric Fleets and Connected Tools
Smart mobility services expand across Spanish cities. Ride-hailing operators add EV models to lower emissions. Car-sharing firms deploy compact EVs for short-distance use. Connected tools support remote diagnostics for faster service. Fleets track battery status to avoid downtime during peak hours. The Spain Electric Vehicle (EV) Market sees interest in telematics that guide efficient routing. Municipal bodies use connected EV fleets for public tasks. This shift strengthens cleaner urban transport options.
- For instance, fleet operators using EVs benefit from connected tools and remote diagnostics to monitor battery status and schedule maintenance, reducing downtime. Fleets track range and charging patterns to avoid overloading infrastructure during peak hours.
Growth of Renewable Integration With EV Charging Hubs and Energy Storage Uses
Renewable integration becomes a core trend across Spain. Solar and wind sites link to EV hubs for green charging. Storage units help stabilize supply during peak demand. Cities plan microgrids that support public chargers with clean energy. Energy firms test bidirectional systems for home and grid use. The Spain Electric Vehicle (EV) Market gains from interest in sustainable charging ecosystems. Hotels and malls adopt rooftop solar to power EV stations. This trend supports national energy goals.
Expansion of Software-Driven EV Features With OTA Updates and Predictive Functions
Software plays a larger role in EV adoption. Automakers deploy frequent over-the-air updates for new features. Predictive tools help drivers plan routes with nearby chargers. Virtual dashboards improve energy tracking and trip planning. Apps guide users to less crowded charging points. The Spain Electric Vehicle (EV) Market benefits from smart features that lift user comfort. Remote control functions help monitor charge levels. This software layer strengthens customer satisfaction.
Market Challenges Analysis:
Slow Charging Availability in Rural Areas and High Demand Pressure in Urban Zones
Charging gaps create friction for many regions. Rural zones face limited stations that reduce travel confidence. Urban zones see high demand that strains fast-charging availability. Power grid limits slow new installations across dense cities. Many buyers delay EV plans due to range fear. Fleet operators struggle during peak hours with long wait times. The Spain Electric Vehicle (EV) Market must address grid readiness issues. These constraints slow near-term progress.
High Upfront Costs, Limited Model Options, and Price Sensitivity Among Buyers
Upfront EV pricing remains a key barrier. Many households delay purchases due to budget limits. Affordable EV models stay limited in several segments. Used EV supply remains small, which reduces low-cost choices. Battery replacement fear still impacts buyer trust. Firms face cost pressure when expanding fleet sizes. The Spain Electric Vehicle (EV) Market must balance pricing with quality gains. Broader affordability will support wider adoption.
Market Opportunities:
Expansion of Fast-Charging Corridors, Tourism-Focused Infrastructure, and Smart Grid Links
Spain holds strong potential in developing tourism-based charging hubs. Hotels and resorts plan EV-ready parking to serve rising travellers. Highway corridors offer scope for fast-charging clusters. Energy firms test smart grid links that improve power balance. Rental fleets invest in EV units for tourist routes. The Spain Electric Vehicle (EV) Market can gain from targeted infrastructure growth. These moves open new revenue streams for operators. Broader access helps attract new EV users.
Growth of Local EV Production, Battery Assembly, and Green Manufacturing Incentives
Industrial zones offer strong potential for EV-related production. Plants can expand assembly lines for new electric models. Battery-pack units open new roles for local suppliers. Workforce upskilling programs support advanced manufacturing. Government incentives promote cleaner production methods. The Spain Electric Vehicle (EV) Market can benefit from strong industrial expansion. New partnerships help attract global investment. These advantages strengthen Spain’s EV position.
Market Segmentation Analysis:
By Type
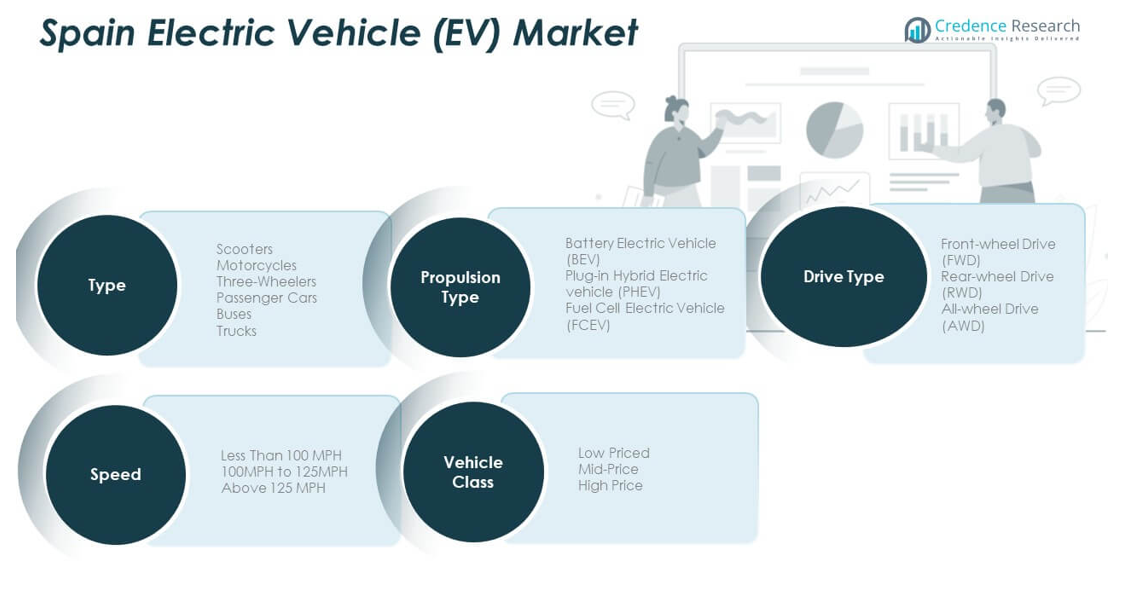
The Spain Electric Vehicle (EV) Market expands across scooters, motorcycles, three-wheelers, passenger cars, and buses. Passenger cars hold strong preference due to wide model availability and rising family use. Scooters gain traction in dense cities where short trips dominate. Motorcycles attract younger commuters who seek quick urban mobility. Three-wheelers remain limited but serve last-mile tasks in select areas. Buses gain demand through public transport upgrades and fleet electrification. This mix shows diverse adoption across personal and commercial needs.
- For instance, compact electric scooters and motorcycles gain traction in dense city areas, offering quick and cost-effective last-mile travel. Passenger cars remain dominant because of broad model availability and family usage.
By Propulsion Type
Battery Electric Vehicles lead due to wider charging access and strong efficiency gains. Plug-in Hybrid Electric Vehicles attract users who want flexibility during long trips. Fuel Cell Electric Vehicles stay niche because infrastructure growth remains slow. BEVs gain strong momentum through new model launches. PHEVs support users in remote regions where charger density stays low. FCEVs may scale when hydrogen corridors expand nationwide. This structure supports balanced buyer choice.
By Drive Type
Front-wheel drive platforms dominate due to lower cost and strong suitability for city travel. Rear-wheel drive models appeal to buyers who want better handling and higher torque. All-wheel drive gains interest among premium users who seek stability and performance. It benefits from rising EV SUV sales. This variety supports wide market coverage.
By Speed and Vehicle Class
Lower-speed EVs attract budget buyers and short-distance riders. Mid-range speed models suit regular commuters. High-speed EVs appeal to performance-focused users. Low-priced EVs support entry-level adoption. Mid-price units meet the needs of mainstream families. High-price EVs gain traction through luxury brands and advanced features.
Segmentation:
By Type
- Scooters
- Motorcycles
- Three-Wheelers
- Passenger Cars
- Buses
By Propulsion Type
- Battery Electric Vehicle (BEV)
- Plug-in Hybrid Electric Vehicle (PHEV)
- Fuel Cell Electric Vehicle (FCEV)
By Drive Type
- Front-wheel Drive (FWD)
- Rear-wheel Drive (RWD)
- All-wheel Drive (AWD)
By Speed
- Less Than 100 MPH
- 100 MPH to 125 MPH
- Above 125 MPH
By Vehicle Class
- Low Priced
- Mid-Price
- High Price
Regional Analysis:
Central Spain (Madrid and Surrounding Provinces)
The Spain Electric Vehicle (EV) Market shows its strongest momentum in Central Spain, led by Madrid, which holds an estimated 42% market share. Madrid gains this lead through dense charging coverage, strict low-emission zones, and high public transport electrification. Buyers in this region adopt EVs at a faster rate due to high income levels and strong urban mobility policies. Fleet operators upgrade vehicles to meet clean-air mandates placed across the metropolitan area. Charging operators expand fast-charging hubs to support commuter traffic. This region sets the national benchmark for EV penetration, and it supports growth for early adopters across Spain.
Catalonia and Eastern Spain (Barcelona, Valencia, and Coastal Regions)
Catalonia secures an estimated 33% market share, driven by Barcelona’s strong focus on sustainable transport and active EV infrastructure expansion. The region benefits from heavy tourism, which raises demand for electric rental fleets and hotel-based charging stations. Coastal cities deploy chargers along highways and parking hubs to support long-distance travel. Industrial areas near Barcelona and Valencia integrate EVs into logistics routes to cut fuel costs. The Spain Electric Vehicle (EV) Market gains steady contribution from this region through strong municipal backing. It also records consistent adoption among families who seek cleaner personal mobility.
Southern and Northern Spain (Andalusia, Basque Country, Galicia, and Others)
Southern and Northern Spain together hold an estimated 25% market share, with rising growth potential due to expanding charging corridors. Andalusia sees higher EV awareness as new chargers appear across major highways and regional capitals. Northern regions like the Basque Country support EV use through strong industrial investment and green policies. Adoption grows at a moderate pace because rural areas still face slower charger rollout. Tourism zones in the south help drive rental EV demand during peak seasons. This region strengthens long-term expansion as infrastructure gaps close and new incentives reach smaller cities.
Key Player Analysis:
Competitive Analysis:
The Spain Electric Vehicle (EV) Market features strong competition among global and domestic automakers that aim to secure early advantage in a fast-growing landscape. Leading brands strengthen portfolios with compact, mid-size, and premium models to meet diverse buyer needs. Charging operators compete through wider fast-charging access across major corridors. Fleet electrification drives higher demand for reliable suppliers with strong service networks. New entrants push innovation in battery range and smart features to gain attention. It benefits from rising investment in assembly units and supply chains. Competitive pressure drives continuous upgrades in performance, safety, and software.
Recent Developments:
- In May 2025, SEAT S.A. announced critical production milestones at its Martorell facility in Barcelona. The company began pre-series assembly of battery systems at its newly constructed Euro 300 million battery plant spanning 64,000 square meters, with capacity to deliver up to 300,000 battery systems annually once fully operational. Simultaneously, pre-series production of body parts commenced for the CUPRA Raval and Volkswagen ID.2 using advanced PXL press technology, positioning both models for full-scale production launch in 2026.
- In February 2025, Kia held its 2025 EV Day in Tarragona, Spain, marking a pivotal moment for the Korean automotive group's European electrification strategy. The company unveiled the Kia EV4, its first dedicated electric sedan and hatchback, featuring two battery options: a standard 58.3kWh offering 430km WLTP range and a long-range 81.4kWh variant delivering range. The company also premiered the Concept EV2, previewing a future B-segment all-electric SUV, and the PV5, Kia's first dedicated Platform Beyond Vehicle (PBV) model.
Report Coverage:
The research report offers an in-depth analysis based on Type, Propulsion Type, Drive Type, Speed, and Vehicle Class. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption will strengthen national mobility goals across cities and highways.
- Charging expansion will support wider access for personal and commercial fleets.
- Local assembly growth will improve supply stability and reduce import reliance.
- New EV models will enhance range and performance, driving mainstream demand.
- Smart software integration will raise interest in connected driving experiences.
- Fleet electrification will accelerate through corporate sustainability targets.
- Renewable-powered charging hubs will support the shift toward cleaner transport.
- Incentive alignment across regions will help reduce market entry barriers.
- Strong OEM competition will lift innovation across all EV categories.
- Broader consumer awareness will support long-term adoption across Spain
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Spain EV Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Spain EV Market projected to grow between 2024 and 2032?
Which Spain EV Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Spain EV Market?
Who are the leading companies in the Spain EV Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Spain Electric Vehicle (EV) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Spain Electric Vehicle (EV) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,377.5 million → 2032: USD 23,096.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Spain Electric Vehicle (EV) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Spain Electric Vehicle (EV) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Spain Electric Vehicle (EV) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Spain Electric Vehicle (EV) Market Drivers
- 3.3 Spain Electric Vehicle (EV) Market Restraints & Challenges
- 3.4 Spain Electric Vehicle (EV) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Spain Electric Vehicle (EV) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Spain Electric Vehicle (EV) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Spain Electric Vehicle (EV) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Spain Electric Vehicle (EV) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Spain Electric Vehicle (EV) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Spain Electric Vehicle (EV) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Spain Electric Vehicle (EV) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Spain Electric Vehicle (EV) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Spain Electric Vehicle (EV) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Spain Electric Vehicle (EV) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Spain Electric Vehicle (EV) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Spain Electric Vehicle (EV) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Spain Electric Vehicle (EV) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Spain Electric Vehicle (EV) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Spain Electric Vehicle (EV) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Spain Electric Vehicle (EV) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Spain Electric Vehicle (EV) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Spain Electric Vehicle (EV) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Spain Electric Vehicle (EV) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
