
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Wheels Aftermarket Market Size 2024 | USD 4,450 million |
| Automotive Wheels Aftermarket Market, CAGR | 5.8% |
| Automotive Wheels Aftermarket Market Size 2032 | USD 6,970 million |
Market Overview
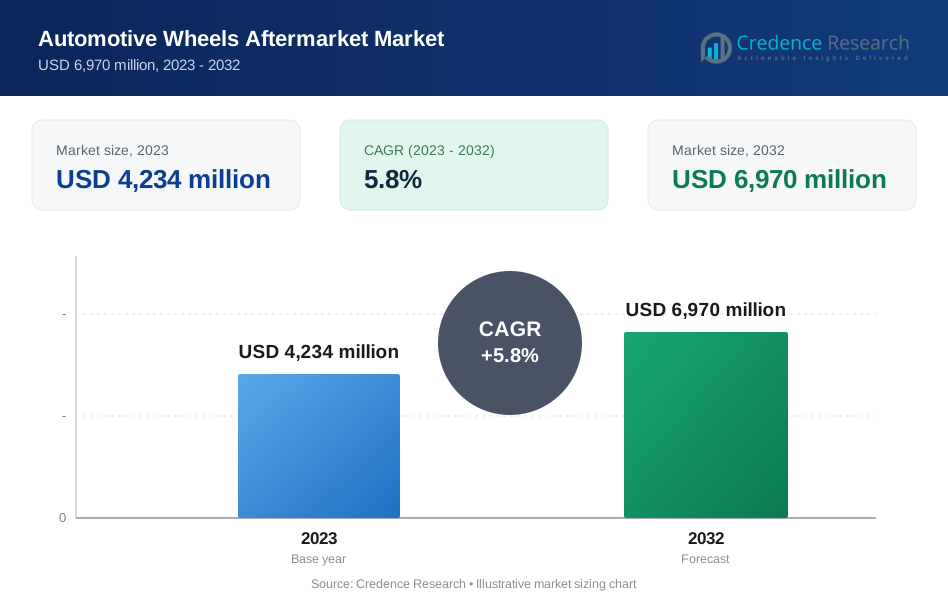
The global Automotive Wheels Aftermarket Market is projected to grow from USD 4,450 million in 2024 to an estimated USD 6,970 million by 2032, with a compound annual growth rate (CAGR) of 5.8% from 2025 to 2032.
Market growth is fueled by rising disposable incomes, greater awareness of vehicle personalization, and the growing popularity of alloy and lightweight wheels that offer improved fuel efficiency and handling. Additionally, the increasing demand for electric vehicles (EVs) and high-performance cars is contributing to the adoption of technologically advanced wheels. The growing presence of e-commerce platforms and mobile apps has made aftermarket wheels more accessible to a wider consumer base, further boosting market demand.
Geographically, North America and Europe dominate the automotive wheels aftermarket due to a strong car customization culture and a high rate of vehicle ownership. However, the Asia-Pacific region is expected to register the fastest growth, supported by expanding urbanization, rising automotive sales, and a growing inclination toward performance and aesthetics among younger consumers. Key players shaping the global market landscape include Enkei Corporation, Ronal Group, Borbet GmbH, Maxion Wheels, and American Eagle Wheel Corporation, all of which are actively investing in product innovation, lightweight materials, and digital retail strategies to strengthen their market presence.
Market Insights
- The global Automotive Wheels Aftermarket Market is projected to grow from USD 4,450 million in 2024 to USD 6,970 million by 2032, at a CAGR of 5.8%.
- Rising interest in vehicle aesthetics, performance upgrades, and personal styling is significantly boosting aftermarket wheel sales.
- Increased use of alloy and aluminum wheels for improved fuel efficiency and handling is supporting market growth.
- The expanding electric vehicle and sports car segments are creating new demand for technologically advanced and lightweight wheels.
- The premium pricing of advanced aftermarket wheels restricts adoption in price-sensitive markets.
- Asia-Pacific is expected to witness the fastest growth due to rising vehicle sales, urbanization, and a young, customization-driven consumer base.
- North America and Europe maintain leading market shares, supported by high vehicle ownership and a strong car customization culture.
Market Drivers
Rising Demand for Aesthetic and Performance Upgrades Fuels Aftermarket Wheel Sales
The global Automotive Wheels Aftermarket Market benefits significantly from increasing consumer interest in vehicle aesthetics and customization. Buyers prioritize wheels not only for utility but also for enhancing the visual appeal of their vehicles. Alloy wheels, chrome finishes, and custom designs have gained popularity among both car enthusiasts and mainstream users. It has pushed automakers and aftermarket suppliers to expand their offerings to cater to diverse tastes. Consumers also perceive upgraded wheels as a symbol of personal style, encouraging repeat purchases and brand loyalty. This trend has strengthened the aftermarket's value proposition and fueled consistent demand.
- For instance, Neo Wheels, a leading aftermarket wheel manufacturer, has seen rising demand for premium alloy wheels, driven by consumer preferences for lightweight and high-performance designs.
Growing Vehicle Parc and Consumer Spending Support Market Expansion
The expanding global vehicle parc contributes to sustained aftermarket wheel demand. Millions of vehicles that exceed manufacturer warranty periods enter the aftermarket ecosystem each year. It opens opportunities for wheel replacements and performance upgrades. Rising disposable incomes, especially in developing economies, have enabled consumers to invest more in vehicle personalization. The willingness to spend on premium products supports higher-margin aftermarket offerings. Increasing awareness of vehicle maintenance also drives proactive wheel replacements beyond wear-and-tear needs.
- For instance, the Society of Indian Automobile Manufacturers (SIAM) reported that passenger vehicle sales in India increased from 3,069,523 to 3,890,114 units between 2021-22 and 2022-23, reflecting growing consumer spending on automobiles.
Rise in Electric Vehicle Adoption Spurs Product Innovation
The shift toward electric vehicles (EVs) has introduced new dynamics into the global Automotive Wheels Aftermarket Market. EVs often require lightweight and aerodynamically efficient wheels to optimize battery performance and driving range. It encourages manufacturers to innovate with advanced materials such as forged aluminum and carbon fiber. The growing presence of EVs in both developed and emerging markets creates fresh demand for EV-specific aftermarket wheel solutions. Manufacturers who address these niche requirements position themselves to capitalize on a rapidly evolving segment.
Digital Retail Channels Enhance Market Accessibility and Consumer Reach
E-commerce and digital retail platforms have transformed how consumers engage with the automotive wheels aftermarket. Online platforms allow customers to compare products, read reviews, and make informed decisions. It has reduced reliance on traditional auto shops and enabled global brands to reach buyers in remote or underserved areas. Faster delivery, detailed product visualization, and virtual fitment tools have improved user experience. Brands that invest in omnichannel strategies strengthen their market presence and improve consumer loyalty. The convenience of digital channels continues to accelerate market penetration.
Market Trends
Shift Toward Lightweight and High-Performance Materials Gains Traction
Manufacturers in the global Automotive Wheels Aftermarket Market are increasingly adopting lightweight materials such as aluminum alloys, forged aluminum, and carbon fiber. These materials help improve fuel efficiency, reduce unsprung weight, and enhance vehicle handling. Consumers prefer performance wheels that combine durability with aesthetic appeal. It drives investments in advanced manufacturing techniques and precision engineering. The demand for wheels that support both performance and sustainability continues to grow. OEM-grade quality in aftermarket products is becoming a new benchmark for consumer expectations.
- For instance, the automotive industry utilized over 3.2 million tons of aluminum alloys for wheel production in 2024, with forged aluminum wheels accounting for 1.1 million tons
Rising Popularity of Customization and Visual Upgrades
Consumers are actively seeking wheels that reflect personal style and vehicle branding. The global Automotive Wheels Aftermarket Market is responding with a broad range of finishes, colors, and spoke designs. Custom-painted wheels, matte coatings, and unique textures are gaining popularity across vehicle segments. It has pushed manufacturers to expand product portfolios and offer more personalized configurations. Wheel customization is no longer limited to luxury or sports cars. Mass-market vehicles now account for a growing share of aftermarket upgrades driven by design preferences.
- For instance, a survey conducted by a leading automotive research firm found that over 65% of vehicle owners opted for aftermarket wheel customization in 2024, with matte black and dual-tone finishes being the most preferred choices.
Increased Use of Digital Tools and Online Platforms for Sales and Fitment
The rise of e-commerce has transformed consumer interaction with the aftermarket wheel segment. Brands now offer digital configurators and virtual fitment tools that allow users to preview wheel designs on their specific vehicle models. It simplifies the purchase decision and builds confidence in product selection. The global Automotive Wheels Aftermarket Market is leveraging online sales to expand reach across regions. Mobile apps and responsive websites enable customers to browse, compare, and order with minimal friction. Online communities and influencer content further drive awareness and brand engagement.
Growing Focus on Sustainability and Recyclable Wheel Solutions
Environmental considerations are shaping product innovation and material sourcing in the aftermarket wheel sector. Manufacturers are adopting sustainable practices, such as recycling aluminum and reducing emissions during production. It reflects the industry’s alignment with broader environmental goals. The global Automotive Wheels Aftermarket Market is witnessing rising interest in wheels that meet both aesthetic and environmental standards. Product labeling, eco-certifications, and lifecycle transparency are gaining importance. Consumers increasingly evaluate sustainability alongside performance and design when selecting aftermarket wheels.
Market Challenges
High Cost of Premium Wheels Limits Mass Market Penetration
The global Automotive Wheels Aftermarket Market faces pricing challenges that hinder broader adoption, especially in cost-sensitive regions. Premium alloy, forged, or carbon fiber wheels often come with high production costs, which reflect in retail pricing. Many consumers prioritize essential vehicle maintenance over aesthetic or performance upgrades. It reduces the addressable market for high-end aftermarket wheels. Competitive pressure also makes it difficult for smaller manufacturers to maintain margins while offering innovative designs. Pricing disparities between OEM replacements and aftermarket alternatives further complicate purchase decisions for budget-conscious buyers.
- For instance, the Automotive Wheels Aftermarket Market saw approximately 6.56 billion units of aftermarket wheels sold globally in 2023, with projections indicating over 8.2 billion units by 2030
Lack of Standardization and Quality Concerns Affect Consumer Confidence
The aftermarket wheel sector includes a wide range of manufacturers, not all of whom adhere to uniform quality and safety standards. The global Automotive Wheels Aftermarket Market struggles with the presence of substandard or counterfeit products that can compromise vehicle performance. It creates uncertainty among consumers and limits brand trust. Inadequate testing or regulatory oversight in certain regions can lead to product failures, damaging market reputation. Retailers and distributors must educate buyers about certified options to mitigate this issue. Ensuring consistent product quality remains a key challenge for market growth.
Market Opportunities
Rising Demand for Electric and Autonomous Vehicles Creates New Aftermarket Segments
The growth of electric and autonomous vehicles presents significant opportunities for the global Automotive Wheels Aftermarket Market. These vehicles require specialized wheels that support lightweight construction, noise reduction, and advanced braking systems. It opens space for manufacturers to develop products tailored to the unique technical demands of EVs and self-driving cars. Custom wheel designs that enhance aerodynamics and energy efficiency are gaining attention. OEMs and aftermarket players can collaborate to offer EV-compatible wheel upgrades. This shift allows the aftermarket to expand into new categories with high growth potential.
Expansion of E-Commerce and Direct-to-Consumer Channels Broadens Reach
Digital platforms enable manufacturers to bypass traditional retail constraints and engage customers directly. The global Automotive Wheels Aftermarket Market benefits from increasing online traffic, where buyers research, compare, and purchase wheels with ease. It reduces dependency on brick-and-mortar stores and expands geographic reach, especially in emerging economies. E-commerce also supports personalized marketing, inventory optimization, and streamlined logistics. Virtual fitment tools and mobile apps enhance the buying experience and drive conversion rates. Direct engagement through digital channels improves brand loyalty and accelerates global market expansion.
Market Segmentation Analysis
By Vehicle Type
Passenger vehicles dominate the global Automotive Wheels Aftermarket Market due to the growing preference for vehicle personalization and aesthetic enhancement among individual consumers. This segment benefits from higher replacement cycles and increased consumer willingness to invest in upgrades. Commercial vehicles follow, with demand driven by wheel replacements related to heavy usage, load-bearing requirements, and fleet maintenance. It offers stable growth potential, especially in logistics, construction, and transportation industries where operational efficiency and safety are critical.
By Material
Alloy wheels lead the market due to their lightweight properties, corrosion resistance, and ability to enhance vehicle performance and style. Aluminum is also gaining traction for its balance of strength, weight, and affordability, making it popular among both premium and mid-range vehicle owners. Steel wheels, though less attractive visually, remain preferred for their durability and cost-effectiveness in heavy-duty and commercial applications. The "Others" category, which includes advanced composites and hybrid materials, is expanding slowly as manufacturers experiment with innovative options.
By Rim Size
Wheels in the 13–19 inches range account for the largest market share due to their widespread application across sedans, hatchbacks, and compact SUVs. The 19–21 inches segment is growing rapidly, supported by rising SUV sales and the demand for sportier aesthetics. The 21 inches & above category, while niche, attracts high-performance and luxury vehicle owners seeking premium customization options. It reflects the market's gradual move toward bold, aggressive wheel designs.
By Coating Type
Powdered coating holds a strong position due to its durability, resistance to scratches and corrosion, and eco-friendly application process. It extends the lifespan of wheels and maintains finish quality under varied conditions. Liquid coating, though versatile in color and finish, sees reduced adoption due to its environmental concerns and lower resistance to wear. It remains relevant in custom applications requiring unique textures or hues.
By Distribution Channel
Retailers play a vital role in driving wheel sales through direct customer interaction, enabling tailored service and fitment support. This channel appeals to individual buyers who seek expert guidance and visual confirmation before purchasing. Wholesale and distributors (W\&D) contribute significantly by supplying bulk orders to garages, fleet operators, and independent retailers. It supports market scalability and enhances product accessibility across diverse regions.
Segments
Based on Vehicle Type
- Passenger Vehicles
- Commercial Vehicles
Based on Material
- Alloy
- Steel
- Aluminum
- Others
Based on Rim Size
- 13 - 19 Inches
- 19 - 21 Inches
- 21 Inches & Above
Based on Coating Type
- Liquid Coating
- Powdered Coating
Based on Distribution Channel
- Retailers
- Wholesale & Distributors (W\&D)
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Automotive Wheels Aftermarket Market
North America holds a significant share of the Automotive Wheels Aftermarket Market, accounting for 28% of the global revenue in 2024. Strong consumer preference for vehicle customization, especially in the U.S., supports demand for aftermarket wheels. The market is well-established, with high vehicle ownership rates and a mature automotive service ecosystem. It benefits from a strong network of retailers and e-commerce platforms offering a wide range of wheel options. Off-road and performance wheel upgrades are popular, particularly among truck and SUV owners. Rising electric vehicle sales are also creating new opportunities for specialized wheel products.
Europe Automotive Wheels Aftermarket Market
Europe represents 25% of the global Automotive Wheels Aftermarket Market and demonstrates consistent growth due to strong automotive heritage and innovation. Countries like Germany, the UK, and France drive aftermarket demand with their large vehicle base and high adoption of alloy and performance wheels. The region prioritizes sustainability, influencing the development of eco-friendly coatings and recyclable materials. It shows a strong preference for premium wheels with advanced design aesthetics. Regulatory standards for quality and safety are strict, pushing manufacturers to maintain high product integrity. Local brands and OEM partnerships strengthen Europe’s competitive edge in the aftermarket segment.
Asia-Pacific Automotive Wheels Aftermarket Market
Asia-Pacific commands the largest share of the global Automotive Wheels Aftermarket Market, standing at 32% in 2024. Rapid urbanization, rising disposable incomes, and expanding vehicle ownership fuel demand across China, India, Japan, and Southeast Asia. Consumers increasingly seek wheel upgrades for visual appeal and ride enhancement. It benefits from a robust manufacturing base and cost-effective production capabilities. Online channels and mobile platforms play a growing role in influencing purchase behavior. Regional growth is supported by expanding EV adoption and a younger demographic inclined toward customization.
Latin America Automotive Wheels Aftermarket Market
Latin America holds 7% of the global market and is showing steady expansion, driven by increasing automotive sales and vehicle aging. Brazil and Mexico are key contributors, where consumers seek affordable wheel replacements and styling enhancements. Economic fluctuations impact discretionary spending but aftermarket wheels remain accessible through competitive pricing. It relies on import channels and regional distributors to meet demand. Interest in performance and off-road wheel designs is growing among younger buyers. Local workshops and garages play a key role in driving market engagement.
Middle East & Africa Automotive Wheels Aftermarket Market
The Middle East & Africa region accounts for 5% of the Automotive Wheels Aftermarket Market, with demand concentrated in the Gulf countries and South Africa. Luxury and high-performance vehicles drive interest in premium aftermarket wheels. Harsh driving conditions and high temperatures create frequent replacement needs, especially for off-road applications. It is influenced by affluent consumers seeking bespoke vehicle modifications. The market remains underdeveloped in parts of Africa, but rising urbanization is opening new channels. Expansion of retail infrastructure supports future growth.
Key players
- RONAL GROUP
- BORBET
- Enkei International, Inc.
- MAXION Wheels
- AEZ Leichtmetallräder GmbH
- BBS Autotechnik GmbH
- Beyern Wheels
- Z. S.p.A.
- CMWheels
- Forgiato
Competitive Analysis
The Automotive Wheels Aftermarket Market features strong competition with both global manufacturers and niche brands offering a diverse range of products. Leading companies such as RONAL GROUP, BORBET, and Enkei International, Inc. focus on lightweight materials, aerodynamic designs, and OEM-quality standards to retain market leadership. It is marked by aggressive product innovation, design customization, and partnerships with performance car makers. Players like Forgiato and BBS Autotechnik GmbH cater to high-end consumers seeking luxury and racing wheels. Online retail expansion and digital configurators have intensified competition by increasing brand visibility. Market players continuously invest in R\&D to develop wheels that balance durability, aesthetics, and performance. Competitive pricing, quality assurance, and global distribution remain key factors influencing brand preference and customer loyalty.
Recent Developments
- In February 2025, RONAL GROUP introduced the RF1 Forged wheel, their first forged aftermarket wheel. Made from high-strength 6061 alloy, it features a seven Y-spoke design optimized for weight reduction and stiffness using advanced milling technology.
- In April 2025, Maxion Wheels announced their participation in Transport Logistic 2025 in Munich, Germany. The company will showcase its latest commercial vehicle wheel offerings, including their newly introduced forged aluminum truck wheels. This event will be held from June 2-5, 2025, in Hall A6, Booth 410 according to the Maxion Wheels news release.
- In 2025, BBS Autotechnik GmbH acquired by KW Automotive, with plans to restart production focusing on the aftermarket business under the BBS brand. ---
Market Concentration and Characteristics
The Automotive Wheels Aftermarket Market is moderately fragmented, with a mix of established global manufacturers and regional players competing on design, material quality, and pricing. It exhibits strong brand differentiation, where factors like aesthetic appeal, performance, and customization options influence buying behavior. High product visibility and consumer engagement through digital platforms drive competitive dynamics. It features short innovation cycles driven by material advancements and changing consumer preferences. Entry barriers remain moderate due to manufacturing complexity, certification requirements, and the need for established distribution networks. Product quality, brand reputation, and compatibility with vehicle types are key determinants of market success.
Report Coverage
The research report offers an in-depth analysis based on Vehicle Type, Material, Rim Size, Coating Type, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The increasing penetration of electric vehicles will drive demand for lightweight and aerodynamic wheels optimized for battery efficiency and performance.
- Consumer inclination toward personalized vehicles will sustain strong interest in custom-designed wheels with unique finishes and spoke patterns.
- Innovation in materials such as carbon fiber, forged aluminum, and hybrid composites will enhance durability and fuel efficiency, expanding premium product segments.
- E-commerce platforms and virtual fitment tools will boost online wheel sales, offering wider product access and convenience for global consumers
- Rising disposable incomes, urbanization, and vehicle ownership in Asia-Pacific, Latin America, and Africa will create substantial aftermarket opportunities.
- Smart wheels with embedded sensors for monitoring temperature, pressure, and performance may gain traction in high-end aftermarket offerings.
- Eco-conscious manufacturing practices and recyclable wheel materials will influence purchasing behavior and regulatory compliance across regions.
- The expanding use of SUVs, trucks, and off-road vehicles will support steady demand for rugged and heavy-duty aftermarket wheels.
- Collaborations between OEMs and aftermarket brands will enhance credibility and distribution, particularly in performance and EV segments.
- Automation, precision engineering, and AI-driven design will reshape wheel development, offering greater customization and efficiency in production.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Vehicle Personalization and Aesthetic Upgrades
Consumers are increasingly seeking to personalize their vehicles, driving demand for aftermarket wheels that offer unique designs, finishes, and enhanced visual appeal. This trend is especially strong among younger buyers and in regions with a robust car customization culture.
Rising Adoption of Lightweight and High-Performance Materials
The shift toward alloy, aluminum, and advanced composite wheels is fueled by their benefits in fuel efficiency, handling, and performance. As electric and high-performance vehicles proliferate, demand for technologically advanced, lightweight wheels continues to rise.
Expansion of E-Commerce and Digital Retail Channels
Online platforms and mobile apps have made aftermarket wheels more accessible, allowing consumers to easily compare, customize, and purchase products. Digital tools such as virtual fitment and configurators are enhancing the buying experience and expanding market reach.
Increasing Vehicle Parc and Replacement Needs
As the global vehicle parc grows and more vehicles age out of warranty, the need for replacement and upgraded wheels rises. Higher disposable incomes, especially in emerging markets, support increased spending on aftermarket enhancements.
Growth in Electric Vehicle and SUV Segments
The expanding adoption of electric vehicles and SUVs is creating new requirements for specialized wheels that are lightweight, aerodynamic, and durable, opening up fresh opportunities for aftermarket suppliers focused on innovation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the global Automotive Wheels Aftermarket Market in 2023, and what is the forecast for 2032 with CAGR?
What factors are driving the growth of the automotive wheels aftermarket market?
Which regions are leading the global automotive wheels aftermarket?
How are electric vehicles influencing the automotive wheels aftermarket?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Alloy
- 1.2.2 Steel
- 1.2.3 Aluminum
- 1.2.4 Others
- 1.3 By Rim Size
- 1.3.1 13 - 19 Inches
- 1.3.2 19 - 21 Inches
- 1.3.3 21 Inches & Above
- 1.4 By Vehicle Type
- 1.4.1 Passenger Vehicles
- 1.4.2 Commercial Vehicles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 4,234 million → 2032: USD 6,970 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Wheels Aftermarket Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Wheels Aftermarket Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Wheels Aftermarket Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Wheels Aftermarket Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Wheels Aftermarket Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Wheels Aftermarket Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Wheels Aftermarket Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Wheels Aftermarket Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 4,234 million → 2032: USD 6,970 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Wheels Aftermarket Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Alloy
- 12.3.7.2 Steel
- 12.3.7.3 Aluminum
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Rim Size - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 13 - 19 Inches
- 12.4.7.2 19 - 21 Inches
- 12.4.7.3 21 Inches & Above
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Vehicles
- 12.5.7.2 Commercial Vehicles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Wheels Aftermarket Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Wheels Aftermarket Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Wheels Aftermarket Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 RONAL GROUP
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 BORBET
- 17.4 Enkei International, Inc.
- 17.5 MAXION Wheels
- 17.6 AEZ Leichtmetallräder GmbH
- 17.7 BBS Autotechnik GmbH
- 17.8 Beyern Wheels
- 17.9 Forgiato
- 17.10 Z. S.p.A.
- 17.11 CMWheels
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

