
Market Overview
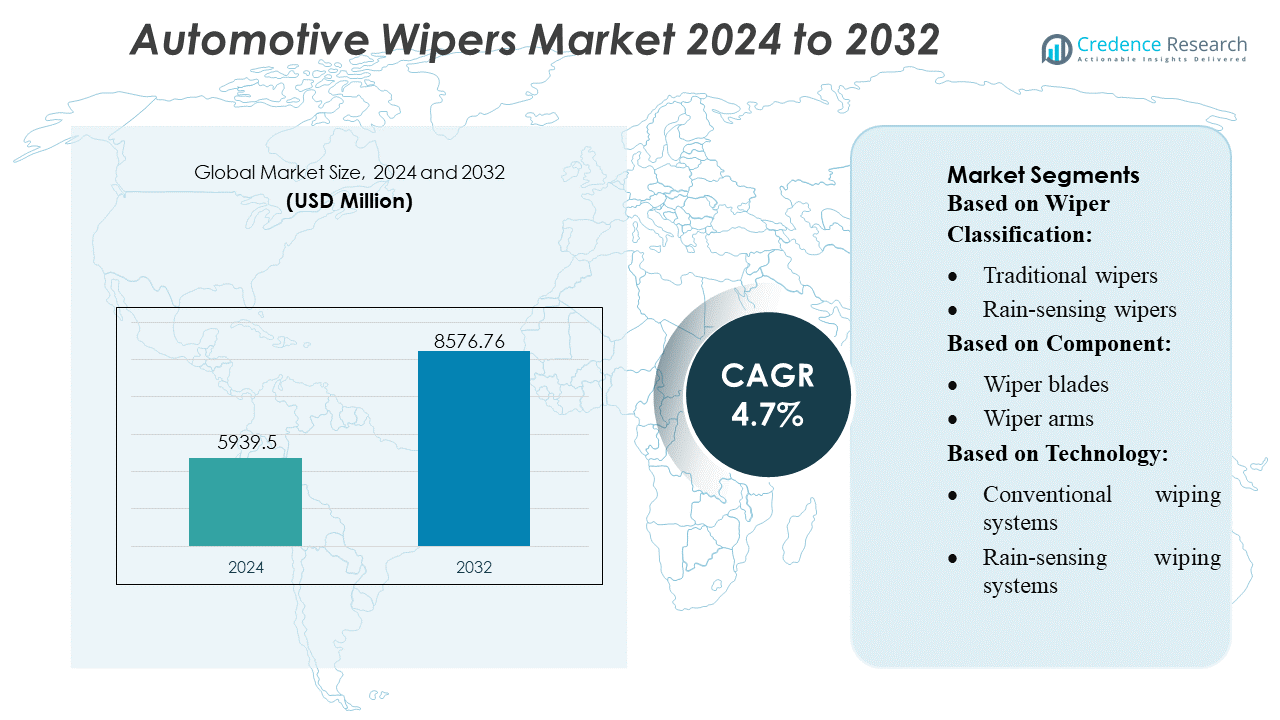
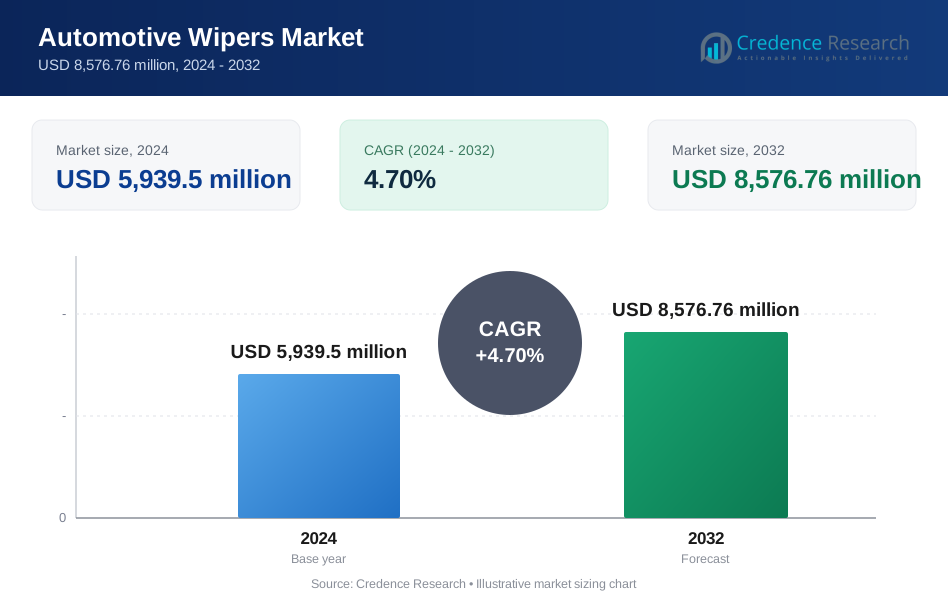
Automotive Wipers Market size was valued USD 5939.5 million in 2024 and is anticipated to reach USD 8576.76 million by 2032, at a CAGR of 4.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Wipers Market Size 2024 | USD 5939.5 Million |
| Automotive Wipers Market, CAGR | 4.7% |
| Automotive Wipers Market Size 2032 | USD 8576.76 Million |
The automotive wipers market is shaped by globally established OEM suppliers and specialized component manufacturers that compete through advancements in blade materials, motor efficiency, and sensor-enabled wiping technologies. Leading companies strengthen their portfolios with aerodynamic beam blades, all-weather durability, and ADAS-compatible systems that support evolving vehicle safety requirements. Strategic priorities include regional production expansion, aftermarket penetration, and integration of energy-efficient components suitable for electric vehicles. Asia-Pacific remains the dominant regional market with an exact 42% share, driven by high vehicle production, expanding mobility demand, and rapid adoption of advanced visibility solutions across both passenger and commercial vehicle segments.
Market Insights
- The market reached USD 5,939.5 million in 2024 and is projected to attain USD 8,576.76 million by 2032, expanding at a 4.7% CAGR.
- Advancements in aerodynamic beam blades, efficient wiper motors, and ADAS-integrated rain-sensing systems drive demand, while OEMs and component specialists compete through durability, noise reduction, and EV-optimized wiping solutions.
- Rain-sensing wipers hold the dominant technology share at approximately 48–50%, supported by rising installation in mid-range passenger vehicles and visibility-safety regulations.
- Asia-Pacific leads with an exact 42% regional share, driven by high-volume automotive manufacturing, rapid urban mobility growth, and strong aftermarket replacement cycles; Europe follows with elevated adoption of premium ADAS-ready wiper assemblies.
- Supply-chain constraints in rubber compounds and rising raw material costs restrain margins, while competitors expand regional production and aftermarket offerings to enhance resilience and maintain performance consistency across varied climatic conditions.
Market Segmentation Analysis:
By Wiper Classification
Traditional wipers dominate the automotive wipers market with an estimated 58–60% share, driven by their lower cost, straightforward installation, and wide compatibility across passenger and commercial vehicles. Their proven reliability in varied climates and ease of replacement strengthen their continued preference among OEMs and aftermarket suppliers. Rain-sensing wipers gain adoption in mid- to high-end vehicles as automakers integrate ADAS features, while rear wipers remain standard in hatchbacks and SUVs to enhance rear visibility. Headlight wipers serve a niche role in premium models requiring enhanced illumination performance.
- For instance, TI offers automotive-qualified motor driver ICs such as DRV8245HQPWPRQ1 which can deliver up to 32 A output current, operate over a wide supply range (4.5–35 V, up to 40 V absolute max), and function across a temperature range of –40 °C to +125 °C.
By Component
Wiper blades hold the largest share, accounting for around 52–54% of the market, supported by frequent replacement cycles, material advancements, and growing consumer focus on driving visibility. Their demand increases with the adoption of beam and hybrid blade designs that improve wipe quality and durability. Wiper arms and motors maintain consistent OEM-driven demand, while washer pumps and nozzles benefit from vehicle production growth. Rain sensors expand rapidly as manufacturers incorporate smart visibility features into connected and semi-autonomous vehicle platforms.
- For instance, Infineon’s high-precision Hall-effect sensor ICs, such as the TLE493D-W2B6, offer linear magnetic sensing with resolution down to 65 µT and operate over temperatures from –40 °C to +125 °C.
By Technology
Conventional wiping systems remain the dominant technology with an estimated 62–64% share, sustained by their affordability, mechanical simplicity, and established presence across mass-market vehicles. Their reliability and ease of service reinforce broad OEM utilization, especially in entry-level and mid-range models. Rain-sensing wiping systems continue to scale with increasing penetration of ADAS and comfort features in new vehicles. Heated wiper blades gain traction in cold-climate regions as they enhance defrosting efficiency and prevent ice accumulation, aligning with safety and winter-performance requirements.
Key Growth Drivers
- Rising Vehicle Production and Expanding Global Car Parc
The automotive wipers market grows steadily as global vehicle production increases and the active car parc expands, particularly across emerging economies. Automakers integrate more durable, high-performance wiper systems to meet safety standards and consumer expectations for improved visibility in diverse climates. Growth in SUVs and crossovers further strengthens demand, as these models require larger blade assemblies with stronger motors. The expanding fleet of passenger and commercial vehicles continuously fuels aftermarket sales, reinforcing long-term revenue stability for component manufacturers and integrated OEM suppliers.
- For instance, Infineon’s silicon MOSFETs provide low on-resistance (R_DS(on) around 9.9 mΩ) and continuous current handling of up to 33 A at 25 °C, operating over a wide supply range, enabling high-efficiency motor drives in applications where energy management is critical.
- Advancements in Sensor-Based and Automated Wiper Technologies
Technological innovation accelerates market expansion as manufacturers adopt rain-sensing systems, adaptive speed control, and AI-supported visibility enhancement solutions. Modern vehicles increasingly feature optical and infrared rain sensors, enabling automated wiping functions that improve driver convenience and safety. Integration with advanced driver-assistance systems (ADAS) also supports growth, as wiper systems must synchronize with cameras, lidar, and radar to maintain clear sensor fields. OEMs prioritize intelligent wiper modules with microprocessor-based control, strengthening premium segment adoption and creating new opportunities for component-level electronics suppliers.
- For instance, Analog Devices’ ADT7420 high-precision digital temperature sensor IC offers ±0.25 °C accuracy from –40 °C to +125 °C, making it suitable for heated wiper blade systems that prevent icing in cold climates.
- Increasing Adoption of All-Weather and High-Durability Materials
Demand rises for advanced wiper blades engineered with silicone rubber, graphite-coated edges, and aerodynamic beam structures that deliver superior performance in extreme weather. These materials extend product lifespan, reduce noise, and ensure consistent wiping efficiency, appealing to both OEM and aftermarket customers. Regions with heavy rainfall or snowfall increasingly prefer winter-optimized blades and heated wiper solutions. Manufacturers invest in precision molding, corrosion-resistant wiper arms, and enhanced motor torque to meet durability expectations, strengthening market growth through product upgrades and long-term replacement cycles.
Key Trends & Opportunities
- Expansion of Smart, Connected, and ADAS-Compatible Wiper Systems
A major trend involves the shift toward smart wiper systems that integrate with vehicle connectivity platforms and ADAS features. Automakers explore self-adjusting wiping patterns, diagnostic alerts, and systems that communicate blade wear status to the driver or service centers. Camera-assisted vision modules require consistently clean windshields, opening opportunities for automated defogging, hydrophobic coatings, and intelligent wiper synchronization. As autonomous vehicles scale, the need for ultra-reliable visibility maintenance systems becomes a key innovation frontier for suppliers.
- For instance, STMicroelectronics provides VND5T100 and VND5T035AK high-side smart power switches, which feature a current limitation (typical) of 22 A and 42 A, respectively. They operate over voltage ranges of 8–36 V and include integrated overcurrent and thermal protection.
- Growth in Aftermarket Personalization and Premium Blade Upgrades
Rising consumer preference for premium beam blades, hybrid structures, and all-season variants creates strong aftermarket opportunities. Retailers report growing adoption of silicone-based blades known for extended durability and quieter operation. Drivers increasingly replace traditional rubber blades with aerodynamic, high-performance designs that enhance wiping stability at higher speeds. E-commerce accelerates product visibility, enabling brands to promote fitment-specific kits and subscription-based replacement services. This trend benefits companies offering differentiated designs, corrosion-proof arm materials, and easy-installation mechanisms.
- For instance, NXP’s H‑bridge driver IC MC33887 is designed for controlling automotive DC motors, making it a technically appropriate building block for systems such as windshield‑wiper motors.
- Rising Focus on Energy-Efficient and Low-Noise Wiper Systems
Manufacturers increasingly design low-noise, low-power wiper motors using improved magnetic circuits, compact gear assemblies, and friction-optimized components. Electric vehicles drive this opportunity, as their silent cabins require acoustic-optimized systems and energy-efficient wiper operation to preserve driving range. Lightweight wiper arms and motors also support sustainability targets by reducing vehicle mass. Suppliers invest in simulations, CFD-informed blade profiles, and vibration-dampened housings to reduce operational noise and wind lift, aligning with OEM requirements for enhanced cabin comfort.
Key Challenges
- High Price Sensitivity and Intense Competition in the Aftermarket
The aftermarket segment faces intense price competition, particularly in developing regions where consumers often prioritize low-cost replacements over premium-quality products. This dynamic pressures manufacturers to balance performance enhancements with cost optimization. Unorganized sector players producing low-cost blades further challenge branded suppliers, limiting margins and slowing adoption of advanced materials. OEMs also negotiate aggressively on component pricing, compelling suppliers to streamline operations while sustaining innovation. These competitive dynamics create persistent profitability constraints for blade and motor manufacturers.
- Durability Issues in Extreme Weather and Limitations in Material Performance
Despite advancements, wiper systems continue to face performance degradation in harsh climates characterized by extreme heat, freezing temperatures, and heavy precipitation. Rubber materials may harden, crack, or lose elasticity, reducing wiping effectiveness and requiring frequent replacements. Ice accumulation can strain motors and damage blade frames, while UV exposure shortens blade life in hot regions. These limitations push manufacturers to invest in advanced polymers, coatings, and reinforced structures, yet material cost inflation and technical constraints hinder rapid scalability of highly durable solutions.
Regional Analysis
North America
North America accounts for around 28% of the automotive wipers market, supported by a large vehicle parc, high adoption of SUVs and pickup trucks, and frequent wiper-related replacements due to diverse weather conditions. The region benefits from strong OEM integration of rain-sensing and heated wiper technologies, particularly in premium and electric vehicle segments. Aftermarket demand remains robust as consumers prefer high-durability silicone and beam blades for enhanced performance in snow and heavy rainfall. Regulatory emphasis on road safety, along with continuous model launches by major automakers, reinforces stable product demand across the United States and Canada.
Europe
Europe secures nearly 25% of the global market, driven by stringent vehicle safety norms, widespread installation of advanced driver-assistance systems, and strong demand for premium wiper technologies. Countries in Northern and Central Europe experience extended winter seasons, boosting adoption of heated wiper blades and high-torque motors. OEMs in Germany, France, and the UK increasingly prioritize energy-efficient, low-noise wiper systems aligned with electric mobility trends. The region also shows strong aftermarket demand as drivers frequently replace blades due to snow, ice accumulation, and road salt exposure, reinforcing steady revenue growth for component suppliers.
Asia-Pacific
Asia-Pacific leads the market with an estimated 42% share, supported by high vehicle production volumes in China, Japan, India, and South Korea. Rapid urbanization, expanding middle-class ownership, and strong OEM manufacturing ecosystems accelerate large-scale demand for cost-efficient wiper systems. Rising adoption of compact SUVs and premium vehicles strengthens interest in rain-sensing and aerodynamic beam blades. Aftermarket growth is fueled by climatic variance-from heavy monsoons in Southeast Asia to snowfall in Japan-driving frequent replacements. Investments in local component manufacturing, combined with rising EV adoption, position the region as the most influential market for future wiper innovations.
Latin America
Latin America holds roughly 3% of the global market, with growth influenced by expanding automotive assembly in Brazil, Mexico, and Argentina. The region experiences steady aftermarket sales due to tropical climates, seasonal rainfall, and rising import availability of mid-range wiper blades. Economic fluctuations, however, constrain premium wiper adoption and keep replacement cycles price-sensitive. Demand strengthens as OEMs increase production of small and mid-sized vehicles tailored for urban use. Gradual introduction of rain-sensing systems in high-end models and growing e-commerce distribution for aftermarket parts create opportunities, although overall penetration remains lower than in developed regions.
Middle East & Africa
The Middle East & Africa region represents nearly 2% of the automotive wipers market, shaped by modest vehicle production, growing urban mobility, and expanding aftermarket distribution networks. Hot climates dominate much of the region, which accelerates rubber degradation and drives repeated blade replacements. South Africa and GCC nations contribute most to OEM-level demand, particularly for SUVs and commercial fleets. Although advanced wiper technologies show limited penetration, premium imports gradually gain traction among luxury vehicle owners. Economic diversification, infrastructure development, and expanding passenger car sales support incremental market growth across key regional clusters.
Market Segmentations:
By Wiper Classification:
- Traditional wipers
- Rain-sensing wipers
By Component:
- Wiper blades
- Wiper arms
By Technology:
- Conventional wiping systems
- Rain-sensing wiping systems
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Automotive Wipers Market include DENSO Corporation, DOGA Group, HELLA GmbH & Co. KGaA, Magneti Marelli S.p.A., Mitsuba Corporation, PEWAG Schneeketten GmbH, Robert Bosch GmbH, Tenneco Inc., TRICO Products Corporation, and Valeo SA. The automotive wipers market features a balanced mix of global Tier-1 suppliers, specialized component manufacturers, and rapidly expanding aftermarket brands competing on technology, durability, and cost efficiency. Companies focus on advancing beam blade aerodynamics, enhancing motor torque performance, and integrating intelligent rain-sensing modules to support the growing adoption of ADAS-equipped vehicles. The competitive environment increasingly rewards suppliers capable of delivering lightweight, energy-efficient, and low-noise systems aligned with electric vehicle requirements. Manufacturers also strengthen market positioning through regional production expansion, material innovation, and digitalized quality control. Meanwhile, aftermarket brands emphasize value-driven replacement cycles, corrosion-resistant designs, and wider e-commerce penetration to capture recurring demand.
Key Player Analysis
- Mitsuba Corporation
- TRICO Products Corporation
- DOGA Group
- Tenneco Inc.
- Valeo SA
- HELLA GmbH & Co. KGaA
- Robert Bosch GmbH
- PEWAG Schneeketten GmbH
- Magneti Marelli S.p.A.
- DENSO Corporation
Recent Developments
- In June 2025, Petra Automotive launched PetraBlades Premium Beam Wiper Blades targeting superior performance, durability in tough weather, and enhanced visibility, aligning with trends for advanced automotive products in the growing market, as confirmed by industry reports and Petra Automotive's social media.
- In May 2025, Tata Motors has launched the All-New Altroz in India at a starting price of around, positioning it as a premium hatchback with a bold design, luxurious interiors, and advanced features. The vehicle now includes segment-first features such as flush door handles, Infinity LED tail lamps, Luminate LED headlamps with DRLs, and a 3D front grille.
- In April 2025, KIMBLADE innovated KIMBLADE X, the latest features with a multi-joint rectangular blade that eliminates reverse noise. Inspired by vehicle suspension systems, it stays evenly balanced and maintains steady contact with the windshield, resulting in a quieter, longer-lasting, higher-performing wipe.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will shift toward intelligent, sensor-integrated wiper systems that enhance visibility and support advanced driver-assistance features.
- Manufacturers will increase adoption of durable silicone and composite materials to extend blade life and improve performance in extreme climates.
- Electric vehicle expansion will drive demand for low-noise, energy-efficient wiper motors and aerodynamic blade designs.
- OEMs will integrate automated wiping functions that self-adjust based on rainfall intensity, windshield clarity, and driving conditions.
- The aftermarket will grow as consumers prefer premium beam blades and easy-installation replacement solutions.
- Digital monitoring technologies will gain traction, enabling predictive maintenance and blade-wear alerts.
- Automakers will use lightweight wiper components to support vehicle efficiency and emissions-reduction targets.
- Heated wiper systems will see wider adoption in cold regions due to improved winter performance.
- Suppliers will expand regional manufacturing capabilities to meet localized OEM sourcing requirements.
- Collaboration between wiper manufacturers and ADAS sensor developers will accelerate development of next-generation visibility systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Vehicle Production and Expanding Global Car Parc
Steady growth in global vehicle production and the expanding number of vehicles on the road, especially in emerging economies, directly increase demand for automotive wipers both as OEM installations and aftermarket replacements.
Advancements in Sensor-Based and Automated Wiper Technologies
The integration of rain-sensing, adaptive speed control, and ADAS-compatible wiper systems is driving market growth as automakers and consumers seek enhanced safety, convenience, and compatibility with advanced driver-assistance features.
Increasing Adoption of All-Weather and High-Durability Materials
Demand for wiper blades made from advanced materials like silicone rubber and graphite-coated edges is rising, as these offer superior durability, noise reduction, and performance in extreme weather, appealing to both OEM and aftermarket customers.
Growth in Aftermarket Personalization and Premium Blade Upgrades
Consumers are increasingly opting for premium beam blades, hybrid structures, and all-season variants, fueling aftermarket sales and encouraging manufacturers to innovate with easy-installation and high-performance replacement solutions.
Rising Focus on Energy-Efficient and Low-Noise Wiper Systems
The shift toward electric vehicles and consumer preference for quieter cabins is pushing manufacturers to develop low-noise, energy-efficient wiper motors and lightweight components, supporting both sustainability and enhanced driving comfort.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Automotive Wipers Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Automotive Wipers Market projected to grow between 2024 and 2032?
Which Automotive Wipers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Automotive Wipers Market?
Who are the leading companies in the Automotive Wipers Market?
Which region commanded the largest share of the Automotive Wipers Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Wiper blades
- 1.2.2 Wiper arms
- 1.2.3 Wiper motors
- 1.2.4 Washer pumps and nozzles
- 1.2.5 Rain sensors
- 1.3 By Technology
- 1.3.1 Conventional wiping systems
- 1.3.2 Rain-sensing wiping systems
- 1.3.3 Heated wiper blades
- 1.4 By Wiper Classification
- 1.4.1 Traditional wipers
- 1.4.2 Rain-sensing wipers
- 1.4.3 Rear wipers
- 1.4.4 Headlight wipers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,939.5 million → 2032: USD 8,576.76 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Wipers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Wipers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Wipers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Wipers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Wipers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Wipers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Wipers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Wipers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,939.5 million → 2032: USD 8,576.76 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Wipers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Wiper blades
- 12.3.7.2 Wiper arms
- 12.3.7.3 Wiper motors
- 12.3.7.4 Washer pumps and nozzles
- 12.3.7.5 Rain sensors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional wiping systems
- 12.4.7.2 Rain-sensing wiping systems
- 12.4.7.3 Heated wiper blades
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Wiper Classification - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Traditional wipers
- 12.5.7.2 Rain-sensing wipers
- 12.5.7.3 Rear wipers
- 12.5.7.4 Headlight wipers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Wipers Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Wipers Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Wipers Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 DENSO Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Valeo SA
- 17.4 Robert Bosch GmbH
- 17.5 TRICO Products Corporation
- 17.6 Mitsuba Corporation
- 17.7 HELLA GmbH & Co. KGaA
- 17.8 DOGA Group
- 17.9 Tenneco Inc.
- 17.10 PEWAG Schneeketten GmbH
- 17.11 Magneti Marelli S.p.A.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

