
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Autonomous Cars Market Size 2024 | USD 1,700,050 million |
| Autonomous Cars Market , CAGR | 8.2% |
| Autonomous Cars Market Size 2032 | USD 3,193,595 million |
Market Overview
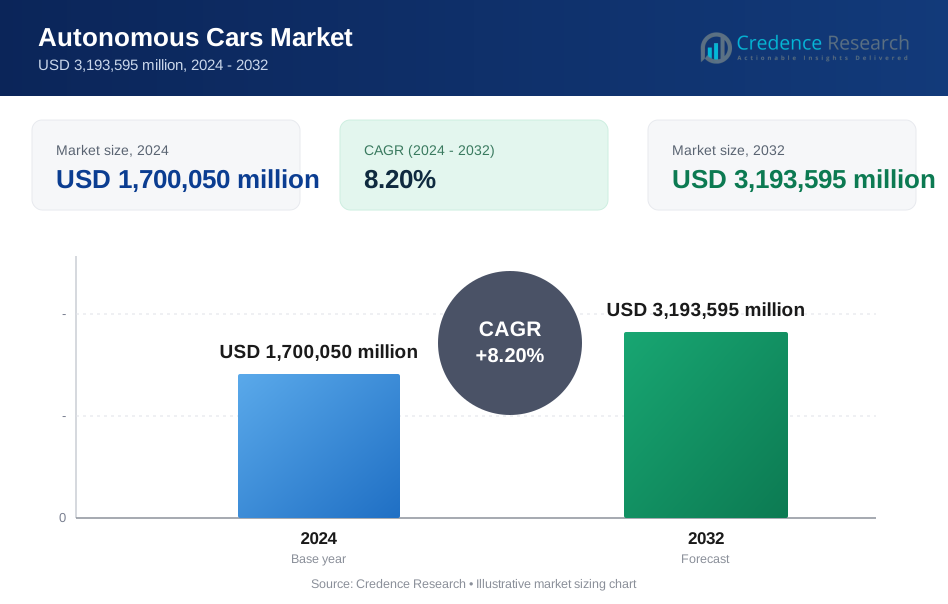
Autonomous Cars Market size was valued at USD 1,700,050 million in 2024 and is anticipated to reach USD 3,193,595 million by 2032, at a CAGR of 8.2% during the forecast period.
The Autonomous Cars Market is primarily driven by advancements in artificial intelligence, sensor technologies, and high-speed connectivity, enabling significant improvements in vehicle safety and driving efficiency. Growing consumer demand for enhanced road safety, reduced traffic congestion, and improved mobility for elderly and disabled individuals further accelerates market growth. Supportive government regulations and increasing investments from automotive manufacturers and technology companies are fostering rapid research and development in autonomous vehicle systems. Additionally, rising urbanization and the proliferation of smart city initiatives are creating favorable conditions for the adoption of self-driving vehicles. Market trends indicate a shift towards shared mobility services, such as robo-taxis and autonomous shuttles, alongside ongoing collaborations between automotive OEMs and tech firms to develop fully integrated autonomous driving solutions. The industry is also witnessing increased focus on cybersecurity, data privacy, and advanced driver-assistance systems (ADAS), shaping the next generation of autonomous mobility.
The geographical analysis of the Autonomous Cars Market highlights significant activity across North America, Europe, and Asia-Pacific, where advanced technology ecosystems, supportive regulations, and substantial investments drive rapid progress in autonomous vehicle development. North America, particularly the United States, leads in large-scale testing and early commercialization, while Europe’s focus on sustainability and harmonized safety standards fosters steady adoption across major automotive hubs. Asia-Pacific, led by China, Japan, and South Korea, showcases swift innovation and integration of smart city initiatives, making it a key region for new mobility solutions. Among the prominent key players shaping this market are Waymo, known for its pioneering autonomous driving technology; BMW, which leverages its engineering excellence and strategic collaborations; and Baidu, a leader in artificial intelligence and autonomous vehicle research. These companies, along with others like Tesla and Toyota Motor, are accelerating the advancement and adoption of self-driving vehicles worldwide.
Market Insights
- The Autonomous Cars Market was valued at USD 1,700,050 million in 2024 and is projected to reach USD 3,193,595 million by 2032, with a CAGR of 8.2% during the forecast period.
- Rapid advancements in artificial intelligence, sensor technologies, and high-speed connectivity are fueling the development and deployment of autonomous vehicles globally.
- Market growth is driven by increasing demand for enhanced road safety, reduced traffic congestion, and improved mobility options for elderly and disabled individuals.
- Industry trends highlight the rise of shared mobility services such as robo-taxis and autonomous shuttles, as well as a strong focus on integrating cybersecurity and advanced driver-assistance systems.
- Competitive analysis reveals major players including Waymo, BMW, Baidu, Tesla, and Toyota Motor, each investing heavily in research, partnerships, and pilot projects to gain market leadership.
- The market faces restraints due to complex regulatory landscapes, lack of standardized global safety norms, and infrastructure gaps, which slow down large-scale adoption and commercialization.
- Regionally, North America leads with robust technology adoption and regulatory support, Europe follows with a strong focus on sustainability and safety, and Asia-Pacific emerges as a growth hub driven by urbanization and smart city initiatives.
Market Drivers
Technological Advancements Propel Market Growth
Continuous improvements in artificial intelligence, machine learning algorithms, and sensor technologies have accelerated the development of autonomous driving capabilities. Enhanced radar, LiDAR, and camera systems now enable vehicles to detect, interpret, and respond to dynamic road environments with greater accuracy. These innovations have raised the reliability and safety standards of autonomous vehicles, making them more viable for commercial deployment. The integration of real-time data analytics and edge computing supports faster decision-making processes within the vehicle. It is also enabling advanced features such as adaptive cruise control, lane-keeping assistance, and automated emergency braking. The Autonomous Cars Market benefits significantly from these breakthroughs, which underpin the industry’s progress toward higher levels of driving automation.
- For instance, India’s autonomous vehicle market is expected to grow significantly due to the increasing adoption of AI, IoT, and machine learning in automotive applications.
Supportive Regulations and Government Initiatives
Governments across major markets are implementing supportive policies and regulatory frameworks to facilitate the adoption of autonomous vehicles. Regulatory agencies are introducing guidelines and safety standards to ensure responsible deployment and operation of self-driving technologies. Public investments in smart infrastructure, such as connected roadways and traffic management systems, create an ecosystem conducive to autonomous vehicle integration. Tax incentives, pilot programs, and grants encourage manufacturers and technology providers to advance their autonomous vehicle offerings. It is witnessing increased collaboration between public and private sectors to develop harmonized standards and address regulatory challenges. These efforts help accelerate commercialization and build consumer trust in autonomous mobility solutions.
- For instance, the European Union and the United States have launched initiatives to develop smart traffic systems that support autonomous vehicle integration.
Changing Consumer Preferences and Urban Mobility Needs
Evolving consumer expectations for convenience, safety, and efficiency are fueling demand for autonomous vehicles. Urbanization trends and the expansion of smart cities are driving a shift toward innovative mobility solutions that can reduce congestion and improve traffic flow. The Autonomous Cars Market responds to the growing appeal of shared mobility services, including ride-hailing and robo-taxi platforms, which offer cost-effective and flexible transportation options. It also addresses the mobility needs of elderly and disabled populations, enhancing accessibility and independence. Consumers show increasing interest in vehicles equipped with advanced driver-assistance features, reinforcing the transition to higher levels of automation. These preferences play a critical role in shaping industry investment and product development strategies.
Strategic Industry Investments and Collaborations
Major automotive manufacturers, technology firms, and startups are investing heavily in autonomous vehicle research and development. Strategic partnerships and joint ventures facilitate knowledge sharing and expedite the deployment of fully integrated self-driving solutions. The market is experiencing significant capital inflows that support large-scale pilot projects and the commercialization of next-generation mobility services. It benefits from cross-industry collaboration, including software development, sensor manufacturing, and telecommunications. Industry players focus on building robust testing protocols, improving system reliability, and addressing challenges related to cybersecurity and data privacy. These collective efforts are positioning the Autonomous Cars Market for sustained long-term growth.
Market Trends
Integration of Artificial Intelligence and Advanced Sensing
The integration of artificial intelligence and advanced sensing technologies is shaping the trajectory of the Autonomous Cars Market. Developers are incorporating sophisticated AI algorithms that improve real-time decision-making and predictive analysis for vehicle navigation. Sensor fusion, which combines inputs from radar, LiDAR, ultrasonic sensors, and cameras, allows vehicles to interpret complex traffic environments with greater accuracy. These advancements enable autonomous vehicles to better identify obstacles, pedestrians, and traffic signals under diverse weather and lighting conditions. It supports continuous learning and adaptation, contributing to safer and more reliable driving experiences. The industry is leveraging these technological improvements to reach higher levels of vehicle autonomy.
- For instance, AI integration in passenger cars is projected to significantly enhance autonomous vehicle capabilities, with radar, LiDAR, and camera systems improving real-time decision-making.
Expansion of Shared Mobility and Autonomous Fleet Services
Shared mobility and autonomous fleet services are emerging as prominent trends within the Autonomous Cars Market. Companies are deploying self-driving vehicles for ride-hailing, robo-taxi, and shuttle services, particularly in urban centers and smart city initiatives. These services address growing demand for efficient, flexible, and cost-effective transportation solutions, especially in densely populated regions. It enables fleet operators to optimize routing, minimize idle time, and reduce operational costs through autonomous technology. The rise of subscription-based mobility models and partnerships between automakers and technology providers is transforming traditional vehicle ownership patterns. These developments are creating new business models and revenue streams for market participants.
- For instance, the expansion of self-driving fleet services is expected to transform urban mobility, with ride-hailing and robo-taxi platforms gaining traction.
Focus on Safety, Cybersecurity, and Data Privacy
Safety, cybersecurity, and data privacy remain top priorities in the evolution of autonomous vehicles. Industry players are implementing robust safety validation protocols to minimize the risk of accidents and system failures. Autonomous Cars Market participants are investing in advanced cybersecurity measures to protect vehicles from hacking and malicious attacks. It also ensures compliance with global data privacy regulations, safeguarding personal and operational data generated by autonomous systems. Ongoing improvements in functional safety and the introduction of fail-safe architectures contribute to building consumer trust in autonomous mobility. These trends support a more resilient and secure deployment of self-driving technologies.
Collaborative Ecosystem and Regulatory Developments
A collaborative ecosystem involving automakers, technology companies, regulators, and infrastructure providers is advancing the Autonomous Cars Market. Strategic partnerships are fostering accelerated research, knowledge exchange, and innovation across the industry. The market is adapting to evolving regulatory requirements and global standards for autonomous driving. It benefits from pilot projects and real-world testing programs that generate valuable insights for future product development. Enhanced collaboration is addressing interoperability challenges and shaping harmonized policies to support widespread adoption. These coordinated efforts are positioning the market for sustainable and scalable growth.
Market Challenges Analysis
Complex Regulatory Landscape and Standardization Hurdles
The Autonomous Cars Market faces a complex regulatory landscape that varies significantly across regions, making large-scale deployment and commercialization difficult. Regulatory authorities in different countries have established distinct safety, liability, and data protection standards for autonomous vehicles, often resulting in fragmented compliance requirements. The lack of unified global standards complicates cross-border testing, sales, and fleet management for manufacturers and technology providers. It requires substantial investments in legal, compliance, and engineering resources to address the diverse set of regulations and certifications. Policymakers and industry stakeholders must work together to harmonize frameworks and accelerate the safe integration of autonomous vehicles. These regulatory challenges remain a significant barrier to the mass adoption of self-driving technologies.
- For instance, India's autonomous vehicle regulations remain in early development compared to global leaders like the U.S. and EU, creating uncertainty for manufacturers and policymakers.
Technological Limitations and Infrastructure Gaps
Despite significant advancements, the Autonomous Cars Market continues to encounter technological limitations and infrastructure gaps that impact vehicle performance and reliability. Current autonomous systems can struggle in complex, unpredictable environments or adverse weather conditions, affecting safety and user confidence. It depends on robust digital infrastructure, such as high-definition mapping, 5G connectivity, and sensor-equipped roadways, which are not uniformly available in all regions. High development and deployment costs, coupled with ongoing maintenance requirements, present additional challenges for industry participants. Manufacturers and service providers must address these limitations to ensure consistent, safe, and efficient autonomous driving experiences. Overcoming these obstacles is critical for the sustained growth and acceptance of the market.
Market Opportunities
Expansion into Emerging Markets and New Use Cases
The Autonomous Cars Market holds significant potential for growth through expansion into emerging markets and the development of new mobility use cases. Rapid urbanization and rising demand for advanced transportation solutions in regions such as Asia-Pacific and Latin America create fertile ground for autonomous vehicle deployment. It can address unique mobility challenges in these areas, including traffic congestion, limited public transport, and rising urban populations. Companies have the opportunity to introduce tailored solutions such as autonomous public transit, last-mile delivery, and shared mobility services. Strategic partnerships with local governments and infrastructure providers will further support successful market entry. These opportunities position the industry for robust geographic and segmental expansion.
Advancements in Connected and Sustainable Mobility
The Autonomous Cars Market can capitalize on advancements in connected and sustainable mobility technologies to deliver greater value to consumers and stakeholders. Integration with smart city infrastructure, electric vehicle platforms, and advanced data analytics creates synergies that enhance both operational efficiency and user experience. It can leverage vehicle-to-everything (V2X) communication to improve traffic management, safety, and environmental sustainability. Ongoing innovation in renewable energy and energy-efficient propulsion systems aligns with global efforts to reduce carbon emissions. Companies investing in these technologies can unlock new revenue streams while contributing to broader sustainability objectives. These advancements support a future-ready, resilient market landscape.
Market Segmentation Analysis:
By Autonomy:
The Autonomous Cars Market is segmented by autonomy levels, reflecting the progressive development and adoption of self-driving technologies. Level 1 and Level 2 vehicles dominate current market share, featuring advanced driver-assistance systems such as adaptive cruise control and lane-keeping assistance. These segments appeal to early adopters and mainstream consumers seeking enhanced safety and convenience without full autonomy. Level 3 vehicles, which enable conditional automation, are gaining traction as regulatory approvals and technical capabilities evolve, offering hands-off driving in certain scenarios. Level 4 autonomy represents the forefront of the market, with vehicles capable of fully autonomous operation within specific environments or geofenced areas. It is witnessing growing investments and pilot programs in Level 4 technology, especially for shared and urban mobility applications. Market participants are focusing on advancing both hardware and software to accelerate the transition toward higher levels of autonomy.
By Fuel: Segmentation by fuel type highlights the industry’s transition towards sustainable mobility. Internal combustion engine (ICE) vehicles currently hold a significant share, driven by widespread infrastructure and established consumer preferences. However, electric vehicles (EVs) are rapidly gaining ground as advancements in battery technology, charging infrastructure, and environmental policies support their adoption. Hybrid vehicles bridge the gap between traditional and electric powertrains, offering flexibility and efficiency. The Autonomous Cars Market is aligning with global sustainability trends, encouraging the integration of autonomous systems with electric and hybrid platforms. It is fostering innovation in both propulsion and autonomy, reinforcing the shift toward cleaner, more efficient transportation solutions.
By End Use: Segmentation by end use distinguishes between personal and shared mobility applications. Personal use remains the largest segment, driven by individual ownership and demand for advanced safety and comfort features in private vehicles. Shared mobility, including ride-hailing, robo-taxis, and autonomous shuttles, is emerging as a significant growth area, particularly in urban centers and smart cities. The Autonomous Cars Market is responding to the shift in consumer attitudes toward flexible, on-demand transportation models. It enables new business opportunities for service providers and supports urban sustainability goals. Companies are developing tailored solutions for both segments, ensuring broad market coverage and adaptability to evolving mobility needs.
Segments:
Based on Autonomy:
- Level 1
- Level 2
- Level 3
- Level 4
Based on Fuel:
- ICE
- Electric
- Hybrid
Based on End Use:
- Personal
- Shared Mobility
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Autonomous Cars Market, accounting for approximately 36% of global revenue in 2024. The region’s leadership position stems from its robust technology ecosystem, strong presence of leading automotive and technology firms, and supportive regulatory frameworks. The United States leads innovation with major investments in research and development, extensive real-world testing programs, and strategic collaborations between automakers and tech giants. Regulatory agencies in the U.S. and Canada have introduced pilot projects, safety guidelines, and incentives that accelerate autonomous vehicle deployment. Urban centers such as San Francisco, Phoenix, and Toronto serve as testbeds for self-driving cars and shared autonomous fleets, setting benchmarks for operational safety and public acceptance. North America’s advanced infrastructure and consumer openness to technological adoption further bolster market expansion. Companies are leveraging these advantages to advance commercial applications, positioning the region as a global hub for autonomous driving innovation and commercialization.
Europe Europe represents around 28% of the global Autonomous Cars Market, driven by strong policy support, leading automotive manufacturers, and an increasing focus on sustainability. Germany, France, the United Kingdom, and Sweden are at the forefront, supported by long-standing automotive traditions and investment in smart mobility solutions. The European Union’s proactive regulatory stance, including harmonized safety standards and cross-border pilot projects, encourages both local and international companies to develop and deploy autonomous vehicles. Key automotive hubs such as Munich, Stuttgart, and Paris are witnessing ongoing collaborations between car manufacturers, technology companies, and public agencies. Europe’s commitment to reducing carbon emissions accelerates the integration of electric and hybrid autonomous vehicles across urban and rural landscapes. The region’s highly developed public transport networks and consumer demand for advanced driver-assistance features contribute to steady adoption. It is also prioritizing cybersecurity and data privacy, reinforcing trust in autonomous mobility.
Asia-Pacific Asia-Pacific commands about 23% of the Autonomous Cars Market, characterized by rapid urbanization, significant consumer demand, and strong government backing. China, Japan, and South Korea are the primary drivers, investing heavily in next-generation vehicle technology and infrastructure. China is emerging as a leader, with government policies, large-scale pilot programs, and investments from both domestic and international players propelling market growth. Japan’s automotive giants are collaborating with tech companies to accelerate the commercialization of autonomous vehicles, while South Korea is expanding its focus on connected and smart mobility solutions. Asia-Pacific’s dense urban centers create ideal environments for shared mobility and autonomous fleet services. Governments across the region are developing smart city initiatives and digital infrastructure, supporting broad-based adoption. The region’s youthful, tech-savvy population further accelerates market momentum.
Rest of the World (Latin America, Middle East & Africa) The Rest of the World, comprising Latin America, the Middle East, and Africa, accounts for approximately 13% of the global Autonomous Cars Market. While these regions are in earlier stages of adoption, they present significant long-term opportunities due to growing urbanization and rising interest in advanced transportation solutions. Latin America is witnessing pilot projects and early investments in autonomous shuttles and fleet services, primarily in large metropolitan areas. The Middle East, led by the United Arab Emirates and Saudi Arabia, is focusing on futuristic smart city developments, including autonomous public transit. Africa is in the nascent phase, with progress dependent on digital infrastructure development and regulatory evolution. It is anticipated that continued investments and international partnerships will unlock future growth across these emerging markets. Companies seeking expansion are monitoring these regions closely, aiming to capitalize on early mover advantages and evolving consumer preferences.
Key Player Analysis
- BMW
- Baidu
- Ford Motor
- General Motors
- Hyundai Motor
- Mercedes-Benz
- Tesla
- Toyota Motor
- Volkswagen
- Waymo
Competitive Analysis
The Autonomous Cars Market features a highly competitive landscape, led by prominent companies such as Waymo, BMW, Baidu, Tesla, Toyota Motor, Ford Motor, General Motors, Hyundai Motor, Mercedes-Benz, Volkswagen, and Waymo. These industry leaders drive market innovation through significant investments in research and development, large-scale pilot programs, and strategic partnerships with technology firms and mobility service providers. Waymo stands out for its advanced autonomous driving technology and extensive real-world testing, setting industry benchmarks for safety and operational reliability. Tesla leverages its strong electric vehicle presence and proprietary software to rapidly introduce advanced driver-assistance features and partial automation to consumers. Baidu’s Apollo project accelerates the integration of artificial intelligence and open-source platforms, strengthening its influence in the Chinese and global markets. BMW, Mercedes-Benz, and Volkswagen focus on integrating autonomous systems with luxury and mainstream vehicles, emphasizing both performance and safety. General Motors and Ford Motor invest in commercial fleet solutions and collaborate with tech startups to expand their autonomous mobility offerings. Hyundai Motor and Toyota Motor pursue innovation in shared mobility and smart city integration. Collectively, these players shape the competitive dynamics of the market, continuously advancing the development and deployment of autonomous vehicle solutions
Recent Developments
- In October 2024, Tesla unveiled the autonomous car Cybercab, a self-driving robotaxi priced below USD30,000, expected to enter production by 2026 or 2027. At the "We, Robot" event, Tesla showcased autonomous Model 3 and Model Y vehicles moving towards unsupervised self-driving in California and Texas next year. Further the company also introduced Robovan, capable of carrying up to 20 people, and highlighted advancements in Tesla's humanoid Optimus robots, predicted to cost $30,000 at scale. He emphasized the safety benefits of autonomous cars, claiming they could be 10-30 times safer than human drivers.
- In August 2024, BMW Group announced that it is leading innovation in automated driving, becoming the first carmaker to combine Level 2 and Level 3 automation in a single vehicle with the new BMW 7 Series. The car integrates the BMW Highway Assistant for enhanced comfort and the BMW Personal Pilot L3 for hands-free driving in certain situations. This advancement allows drivers to relax during long trips or in traffic jams, although they must be ready to intervene when prompted. BMW's commitment to automation is advancing personal mobility, reducing accidents, and improving traffic flow. The company remains at the forefront of autonomous driving technology, pushing toward future advancements in AI and sensor systems.
- In October 2023, Uber forged a partnership with Waymo, the autonomous car company under Google's parent company, Alphabet. Phoenix has become the inaugural city where Uber has officially introduced access to Waymo's autonomous cars. Waymo vehicles are responsible for providing the autonomous rides offered by Uber and the pricing for these rides is consistent with traditional car rides provided by Uber.
- In August 2023, Baidu, Inc. declared the extension of its autonomous ride-hailing platform, Apollo Go, to encompass Wuhan Tianhe International Airport, broadening the reach of its driverless car service.
- In May 2023, Valeo and DiDi Autonomous Driving entered into a strategic collaboration and investment pact. Valeo is set to invest in DiDi Autonomous Driving and the collaborative effort between the two entities focuses on crafting intelligent safety solutions for L4 robotaxis.
Market Concentration & Characteristics
The Autonomous Cars Market demonstrates a high degree of market concentration, with a small group of global technology giants and established automotive manufacturers leading innovation and commercialization efforts. It is characterized by significant barriers to entry, including the need for advanced research capabilities, large-scale capital investments, and access to high-quality data for artificial intelligence development. Intense collaboration between automakers and technology firms drives rapid advancements in autonomous driving systems, sensor integration, and connectivity solutions. The market shows a strong focus on safety validation, regulatory compliance, and pilot testing, with leaders actively pursuing partnerships to accelerate deployment. Distinct characteristics include a blend of luxury, mainstream, and shared mobility offerings, with product development tailored to both personal and fleet applications. The Autonomous Cars Market is defined by its dynamic pace of innovation, evolving regulatory frameworks, and the strategic positioning of key players to secure long-term competitive advantage
Report Coverage
The research report offers an in-depth analysis based on Autonomy, Fuel, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Industry players will focus on reducing the cost of autonomous technologies to make self-driving cars accessible to a wider consumer base.
- Vehicle-to-everything (V2X) communication will enhance real-time connectivity, supporting safer and smarter road environments.
- Governments will prioritize the development of national infrastructure to support autonomous driving, such as smart traffic signals and high-precision mapping.
- Insurance models and legal frameworks will evolve to address liability and risk associated with autonomous vehicles.
- New business models, including subscription-based autonomous mobility and pay-per-use services, will reshape personal and shared transportation.
- Manufacturers will emphasize energy efficiency, pairing electric propulsion with autonomous systems to meet sustainability goals.
- Large-scale fleet deployments for logistics, public transport, and last-mile delivery will accelerate the commercialization of autonomous vehicles.
- The market will see increased integration of advanced driver-assistance systems (ADAS) in conventional vehicles as a stepping stone to full autonomy.
- Data collection and analytics from autonomous vehicles will drive innovation in predictive maintenance, safety improvements, and route optimization.
- Cross-industry collaborations will intensify, with automakers, software firms, telecom providers, and governments working together to create a seamless mobility ecosystem.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in AI and Sensors
Continuous improvements in artificial intelligence, machine learning, and sensor technologies such as LiDAR, radar, and cameras are enabling vehicles to interpret complex road environments more accurately, increasing the reliability and safety of autonomous cars and accelerating their commercial deployment.
Supportive Regulations and Government Initiatives
Governments in key markets are implementing favorable policies, safety standards, and infrastructure investments, such as smart traffic systems and connected roadways, which facilitate the integration and adoption of autonomous vehicles.
Changing Urban Mobility and Consumer Preferences
Urbanization and the expansion of smart cities are driving demand for innovative mobility solutions, including shared autonomous fleets and robo-taxis, while consumers increasingly seek vehicles with advanced safety and convenience features.
Strategic Industry Investments and Collaborations
Major automakers and technology firms are investing heavily in R&D, pilot projects, and cross-industry partnerships, accelerating the development and commercialization of autonomous driving solutions and expanding the market’s reach.
Focus on Safety, Cybersecurity, and Data Privacy
The industry’s emphasis on robust safety validation, advanced cybersecurity measures, and compliance with data privacy regulations is building consumer trust and supporting the safe, large-scale deployment of autonomous vehicles.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Autonomous Cars Market?
What factors are driving the growth of the Autonomous Cars Market?
What are the key segments within the Autonomous Cars Market?
Who are the major players in the Autonomous Cars Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fuel
- 1.2.1 ICE
- 1.2.2 Electric
- 1.2.3 Hybrid
- 1.3 By End Use
- 1.3.1 Personal
- 1.3.2 Shared Mobility
- 1.4 By Autonomy
- 1.4.1 Level 1
- 1.4.2 Level 2
- 1.4.3 Level 3
- 1.4.4 Level 4
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,700,050 million → 2032: USD 3,193,595 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Autonomous Cars Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Autonomous Cars Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Autonomous Cars Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Autonomous Cars Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Autonomous Cars Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Autonomous Cars Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Autonomous Cars Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Autonomous Cars Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,700,050 million → 2032: USD 3,193,595 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Autonomous Cars Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fuel - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 ICE
- 12.3.7.2 Electric
- 12.3.7.3 Hybrid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Personal
- 12.4.7.2 Shared Mobility
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Autonomy - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Level 1
- 12.5.7.2 Level 2
- 12.5.7.3 Level 3
- 12.5.7.4 Level 4
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Autonomous Cars End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Autonomous Cars Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Autonomous Cars Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Autonomous Cars Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Waymo
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BMW
- 18.4 Baidu
- 18.5 Tesla
- 18.6 Toyota Motor
- 18.7 Ford Motor
- 18.8 General Motors
- 18.9 Hyundai Motor
- 18.10 Mercedes-Benz
- 18.11 Volkswagen
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

