
Market Overview:
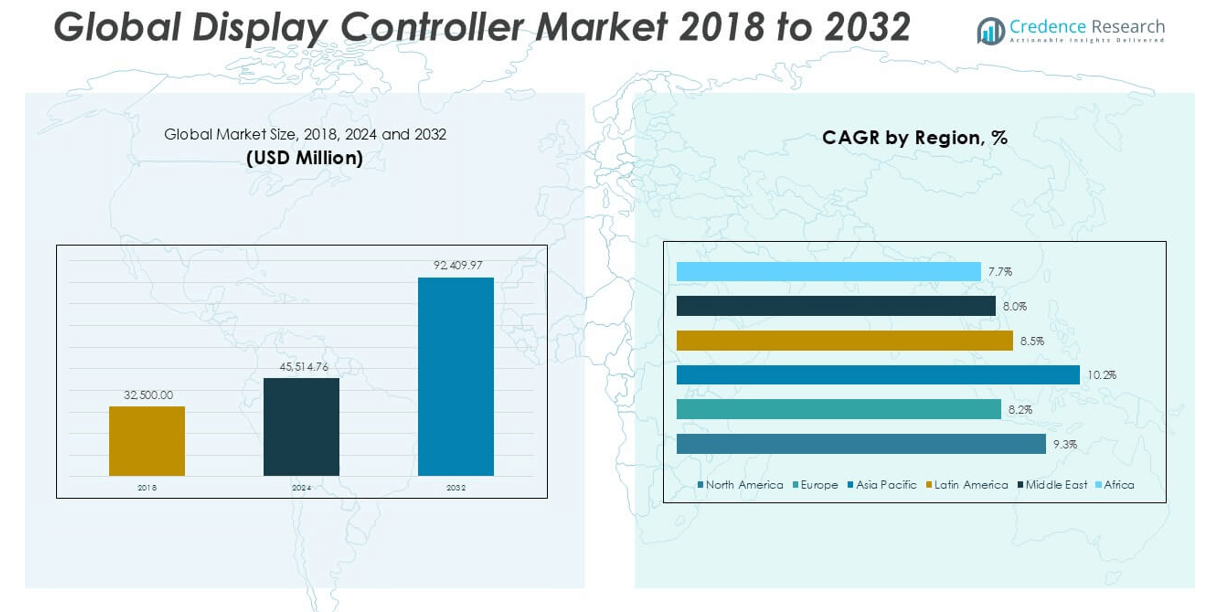
The Display Controller market size was valued at USD 32,500.00 million in 2018 and grew to USD 45,514.76 million in 2024. It is anticipated to reach USD 92,409.97 million by 2032, expanding at a CAGR of 9.31% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Display Controller Market Size 2024 | USD 45,514.76 million |
| Display Controller Market, CAGR | 9.31% |
| Display Controller Market Size 2032 | USD 92,409.97 million |
The Display Controller market is highly competitive, with top players including Samsung Electronics, LG Display, Texas Instruments, STMicroelectronics, NXP Semiconductors, Synaptics, and Himax Technologies. These companies lead through technological innovation, diversified product portfolios, and strategic partnerships. Samsung and LG dominate the high-end display controller space, particularly in OLED and smart display technologies, while Texas Instruments and STMicroelectronics hold strong positions in industrial and automotive applications. Regionally, Asia Pacific leads the market with a 40% share in 2024, driven by high electronics manufacturing capacity and increasing demand across consumer and automotive sectors. North America and Europe follow, supported by strong R&D and advanced industrial infrastructure.
Market Insights
- The global Display Controller market was valued at USD 45,514.76 million in 2024 and is projected to reach USD 92,409.97 million by 2032, growing at a CAGR of 9.31% during the forecast period.
- Rising demand for high-resolution and energy-efficient displays in smartphones, automotive infotainment systems, and smart TVs is driving market growth, with Touch Screen Controllers emerging as the leading segment due to widespread adoption across consumer electronics.
- Key trends include increasing integration of display controllers in connected devices, expansion of IoT applications, and growing use of advanced display panels in electric and autonomous vehicles.
- Major players such as Samsung Electronics, LG Display, Texas Instruments, and STMicroelectronics dominate the competitive landscape, though market growth is constrained by high integration costs and design complexities.
- Asia Pacific holds the largest regional share at 40%, followed by North America (27%) and Europe (18%), supported by robust electronics manufacturing and technology adoption.
Market Segmentation Analysis:
By Type
The Display Controller market, segmented by type, includes Digital Display Controllers, Smart Display Controllers, Touch Screen Controllers, Multi-Display Controllers, and Others. Among these, Touch Screen Controllers hold the dominant market share due to their widespread adoption in smartphones, tablets, kiosks, and interactive displays. Their integration with capacitive and resistive touch technologies drives demand across consumer and commercial electronics. Increasing use of touchscreen interfaces in automotive infotainment systems and industrial control panels further supports this growth. The rising trend toward intuitive user interfaces across applications continues to fuel the demand for advanced touch screen controller solutions globally.
- For instance, Synaptics Incorporated introduced its ClearPad® 3700 family of capacitive touch controllers, which supports up to 10-finger simultaneous input with a scan rate of 240 Hz and screen sizes up to 8 inches, significantly improving responsiveness and precision in smartphones and tablets.
By Application
Based on application, the Display Controller market is segmented into Consumer Electronics, Medical Equipment, Office Automation, Automotive, Industrial Control, and Others. Consumer Electronics emerges as the leading sub-segment, accounting for the highest market share. Within this, Smartphones dominate due to their large-scale production and constant innovation in display technologies. High demand for high-resolution and energy-efficient displays in smartphones and tablets drives the use of sophisticated display controllers. Additionally, the proliferation of smart TVs and wearable devices contributes to the strong growth of this segment. Technological advancements in display resolution and refresh rates further propel market expansion in the consumer electronics domain.
- For instance, Samsung Electronics' Galaxy S24 Ultra utilizes the M13 OLED panel featuring a peak brightness of 2600 nits, managed by Samsung’s advanced IC display controller, which enables optimized performance and power efficiency.
By End-User
The Display Controller market by end-user is categorized into Residential, Commercial, and Industrial segments. The Commercial segment leads the market with the largest share, driven by widespread usage in digital signage, POS terminals, smart offices, and display-based automation systems. The increasing deployment of display-centric solutions across retail, hospitality, healthcare, and education sectors has significantly boosted demand. Moreover, smart display integration in conference rooms, collaborative workspaces, and self-service kiosks reinforces commercial usage. Rising adoption of advanced visual solutions for customer engagement and operational efficiency is a key factor accelerating growth in this segment over residential and industrial counterparts.
Market Overview
Rising Demand for High-Resolution Displays
The growing preference for high-resolution displays in smartphones, televisions, automotive systems, and industrial equipment is a major driver of the display controller market. As consumers and industries demand sharper images, enhanced contrast, and faster refresh rates, manufacturers are integrating advanced display controllers to manage complex display functions. This demand is especially prominent in gaming, AR/VR, and 4K/8K television segments. The push for superior visual experiences in both consumer and professional applications continues to accelerate the adoption of high-performance display controllers globally.
- For instance, LG Display developed a 97-inch OLED.EX display with a resolution of 3840 x 2160 and integrated its Alpha 11 AI processor controller, which enhances image quality by 70% in AI-based upscaling and improves response speed by 30%.
Expanding Consumer Electronics Sector
The rapid expansion of the global consumer electronics industry significantly fuels the growth of the display controller market. Smartphones, tablets, wearable devices, and smart TVs heavily rely on display controllers to ensure efficient processing and output of visual content. Continuous innovation and shorter product life cycles in consumer devices necessitate advanced controller technologies. Additionally, rising disposable incomes, especially in emerging economies, are leading to increased adoption of display-enabled electronics, driving consistent demand for high-quality display controllers in the consumer segment.
- For instance, MediaTek’s Dimensity 9300 SoC integrates an Imagiq 990 display controller that supports refresh rates up to 180Hz at FHD+ resolution and HDR10+ video processing, enabling fluid and visually rich experiences in next-generation smartphones.
Technological Advancements in Automotive Displays
The integration of advanced display technologies in automotive applications-such as infotainment systems, digital instrument clusters, and heads-up displays-serves as a key growth driver. Modern vehicles increasingly feature interactive and multi-display dashboards that require robust display controllers to handle real-time data and seamless transitions. The shift toward connected, autonomous, and electric vehicles further amplifies the need for sophisticated display control systems. Automakers are investing in display innovations to enhance user experience, improve safety, and differentiate their products in a competitive market.
Key Trends & Opportunities
Proliferation of Smart Devices and IoT Integration
The widespread adoption of smart devices and IoT-enabled systems presents strong growth opportunities for the display controller market. Devices such as smart home panels, wearables, healthcare monitors, and industrial automation systems all utilize display controllers to manage user interfaces. As the Internet of Things continues to expand across sectors, the demand for compact, energy-efficient, and intelligent display controllers grows. These controllers play a vital role in facilitating human-machine interaction, driving innovation and new application areas for display technologies.
- For instance, STMicroelectronics launched the STM32U5 series MCU with a built-in LTDC (LCD-TFT Display Controller) supporting resolutions up to WXGA (1366 x 768) and embedded Chrom-ART graphics accelerator, offering low-power UI control for battery-powered IoT devices.
Growth in Industrial and Medical Display Applications
Emerging applications in the industrial and medical sectors offer significant growth potential. Industrial control systems and diagnostic medical equipment now rely on advanced displays for accurate data visualization and user interaction. Display controllers in these segments must meet stringent performance, reliability, and compliance standards. As automation and digitalization increase, particularly in Industry 4.0 environments and telehealth platforms, the need for specialized display controller solutions designed for harsh or regulated environments continues to rise.
- For instance, Renesas Electronics introduced the RZ/G2L MPU series with a built-in 3D graphics engine and video codec supporting up to 1920 x 1080 resolution, tailored for medical ultrasound machines and factory HMIs requiring robust visual performance and real-time data display.
Key Challenges
High Integration Costs and Complex Design Requirements
One of the key challenges in the display controller market is the high cost of integration and the complexity of designing advanced controller systems. As displays become more sophisticated, the underlying controller architecture must manage greater data volumes, multiple interfaces, and higher refresh rates. These requirements increase development costs and time, particularly for smaller manufacturers. Ensuring compatibility with various display panels and user interfaces further complicates the design process, slowing market entry for new players.
Rapid Technological Changes and Short Product Lifecycles
The fast-paced nature of display technology presents a major challenge, especially for manufacturers aiming to stay competitive. Continuous advancements in display resolutions, panel types, and refresh technologies demand frequent upgrades to controller components. Keeping up with changing specifications requires ongoing R&D investments and agile supply chains. This dynamic environment can strain resources, lead to inventory obsolescence, and pressure pricing strategies, particularly in cost-sensitive consumer markets.
Supply Chain Disruptions and Semiconductor Shortages
Persistent supply chain disruptions and global semiconductor shortages have significantly impacted the display controller market. Display controllers rely heavily on microchips and specialized components, which have faced availability issues since 2020. These disruptions have delayed production schedules and increased manufacturing costs. Additionally, geopolitical tensions and trade restrictions have created uncertainties in sourcing raw materials and electronic components, forcing companies to diversify supply bases or invest in regional manufacturing, increasing operational complexity.
Regional Analysis
North America
In 2018, the North America display controller market was valued at USD 8,921.25 million, growing to USD 12,293.26 million in 2024, and is projected to reach USD 24,913.89 million by 2032, registering a CAGR of 9.3%. The region accounted for approximately 27% of the global market share in 2024, driven by high adoption of advanced display technologies in consumer electronics, automotive, and industrial sectors. The presence of leading tech companies, increasing demand for smart displays, and strong R&D infrastructure contribute significantly to regional growth. Continued investment in infotainment systems and display-integrated devices further supports market expansion.
Europe
Europe’s display controller market was valued at USD 6,032.00 million in 2018 and reached USD 7,982.04 million in 2024. It is projected to grow to USD 14,910.59 million by 2032, at a CAGR of 8.2%. The region held about 18% of the global market share in 2024. The European market is bolstered by the automotive industry's strong presence, particularly in Germany and France, where the demand for high-performance digital instrument clusters and infotainment systems is on the rise. Additionally, advancements in medical imaging and display systems across the region are fueling the demand for specialized display controllers.
Asia Pacific
Asia Pacific leads the global display controller market, holding the largest market share of around 40% in 2024. The market was valued at USD 12,593.75 million in 2018, reached USD 18,130.61 million in 2024, and is expected to surge to USD 39,255.83 million by 2032, at a robust CAGR of 10.2%. The region’s growth is driven by rapid urbanization, a booming electronics manufacturing sector, and increasing consumption of smartphones, tablets, and smart TVs in countries like China, India, Japan, and South Korea. Government initiatives promoting industrial automation and digital infrastructure further accelerate the adoption of display controllers.
Latin America
The display controller market in Latin America stood at USD 2,457.00 million in 2018 and expanded to USD 3,413.15 million by 2024. It is anticipated to reach USD 6,512.13 million by 2032, registering a CAGR of 8.5%. Holding a market share of about 7.5% in 2024, the region benefits from growing demand in consumer electronics and rising adoption of digital technologies across sectors. Brazil and Mexico are the primary contributors, supported by increasing penetration of smartphones and the gradual integration of smart automotive and industrial display solutions across urban and semi-urban areas.
Middle East
The Middle East display controller market grew from USD 1,339.00 million in 2018 to USD 1,765.68 million in 2024 and is forecasted to reach USD 3,262.58 million by 2032, registering a CAGR of 8.0%. The region accounted for approximately 4% of the global market share in 2024. Demand is driven by increased investment in smart city initiatives, retail digitization, and expanding healthcare infrastructure, particularly in the Gulf Cooperation Council (GCC) countries. The rising use of interactive digital displays and automation in commercial and industrial sectors also contributes to sustained growth across the region.
Africa
Africa’s display controller market was valued at USD 1,157.00 million in 2018 and reached USD 1,930.01 million in 2024. It is expected to grow to USD 3,554.94 million by 2032, registering a CAGR of 7.7%. Representing around 4.2% of the global market share in 2024, the region's growth is gradually accelerating due to increasing mobile penetration, digital transformation in government and education, and growing urbanization. Countries such as South Africa, Nigeria, and Kenya are emerging as key markets, driven by demand for display-enabled consumer electronics and the slow but steady advancement of industrial and healthcare display technologies.
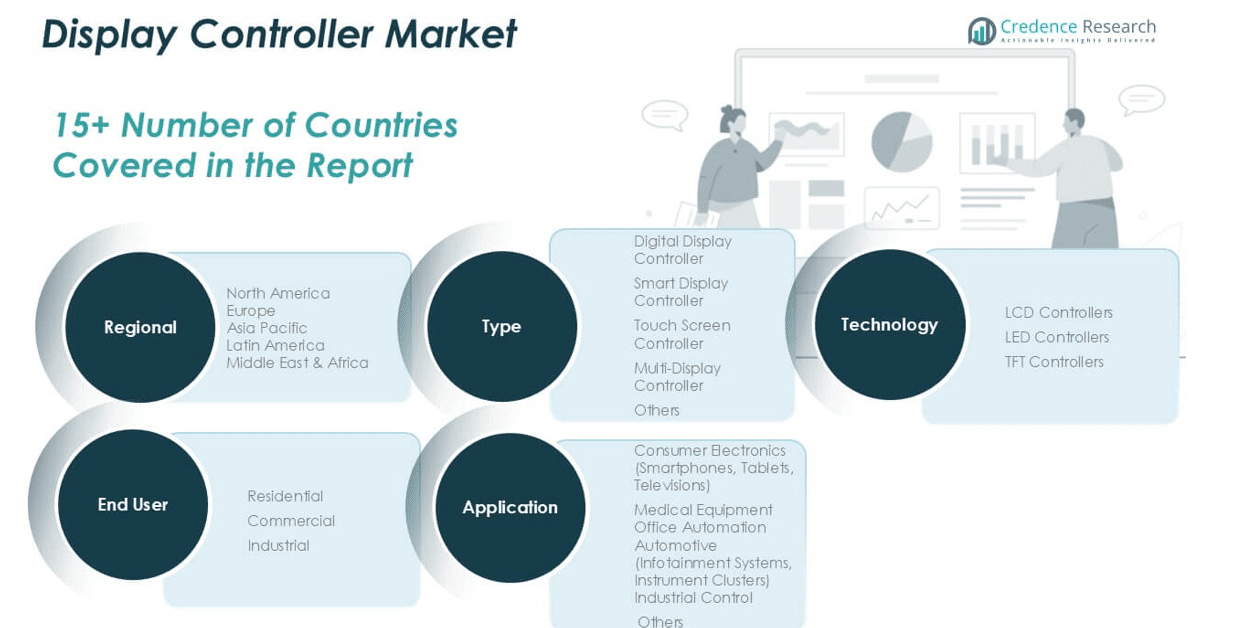
Market Segmentations:
By Type
- Digital Display Controller
- Smart Display Controller
- Touch Screen Controller
- Multi-Display Controller
- Others
By Application
- Consumer Electronics
- Smartphones
- Tablets
- Televisions
- Medical Equipment
- Office Automation
- Automotive
- Infotainment Systems
- Instrument Clusters
- Industrial Control
- Others
By End-User
- Residential
- Commercial
- Industrial
By Technology
- LCD Controllers
- LED Controllers
- TFT Controllers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Display Controller market is characterized by the presence of several global players striving to enhance their technological capabilities and expand their market presence. Companies such as Samsung Electronics, LG Display, Texas Instruments, and STMicroelectronics lead the market with strong product portfolios and robust R&D investments. These players focus on innovations in high-resolution display control, energy efficiency, and integration for consumer electronics, automotive, and industrial applications. Strategic initiatives such as partnerships, acquisitions, and product launches are commonly employed to gain competitive advantage. The market also sees rising contributions from Taiwanese and Japanese firms, which offer cost-effective and specialized solutions. Overall, competition remains intense, driven by rapid technological evolution, customer demand for superior display performance, and the growing adoption of smart and connected devices.
Key Player Analysis
- Samsung Electronics Co., Ltd. (South Korea)
- LG Display Co., Ltd. (South Korea)
- Texas Instruments, Inc. (USA)
- Toshiba Corporation (Japan)
- Fujitsu Ltd. (Japan)
- Siemens AG (Germany)
- STMicroelectronics N.V. (Switzerland)
- NXP Semiconductors N.V. (Netherlands)
- Synaptics Incorporated (USA)
- Himax Technologies, Inc. (Taiwan)
- MediaTek Inc. (Taiwan)
- National Instruments Corporation (USA)
- Silicon Laboratories Inc. (USA)
- Panasonic Corporation (Japan)
- Analog Devices, Inc. (USA)
- Parade Technologies Ltd. (Taiwan)
- Innolux Corporation (Taiwan)
- ON Semiconductor Corporation (USA)
- Renesas Electronics Corporation (Japan)
Recent Developments
- In April 2025, Toshiba released updated firmware and configuration utilities for its TCx Touch Display 6150 series, supporting both Windows and Linux operating systems. The updates focus on enhancing the monitor controller's performance and enabling support for new features in Toshiba's retail and industrial displays. The new utilities include a Monitor Update Utility and a Display Configuration Utility.
- In March 2025, LG Display introduced its Gen 4 OLED monitor panels with a four-layer primary RGB tandem structure, achieving a peak white brightness of 4,000 nits, a 33% increase over previous designs. They also announced plans to produce 34-inch and 39-inch ultra-wide panels later in 2025, and are developing a glossy 32-inch 4K OLED panel for mainstream monitors, showcasing advancements in both TV and monitor display controller technology.
- In March 2025, At MWC 2025, Samsung showcased concept devices with innovative display formats, previewing future commercial applications.
- In January 2025, Siemens launched the NX Immersive Designer suite, a collaborative effort with Sony, to revolutionize 3D industrial and engineering visualization. This new suite integrates Sony's high-resolution OLED microdisplay technology and advanced controllers with Siemens' NX software, enabling immersive, photorealistic 3D experiences. It utilizes Siemens' digital twin and AI capabilities for real-time rendering and intuitive interaction with 3D models.
- In January 2025, Toshiba launched new 32-bit microcontrollers (MCUs) with Arm Cortex-M4 cores, expanding their motor control lineup. These MCUs are designed for smarter and safer display and motor control in consumer and industrial devices, boasting improved real-time operation, enhanced diagnostics, and better integration for advanced display applications. The new devices are part of Toshiba's M4K group and M470 group and are well-suited for field-oriented control (FOC) of AC motors, brushless DC motors, and various inverter controls. .
- In August 2024, Texas Instruments, Inc. (USA) released the DLPC8445 DLP display controller, the smallest ever (9mm x 9mm), enabling ultra-compact 4K UHD projectors and AR smartglasses. This controller provides 100+ inch diagonal displays, ultra-low latency (sub-millisecond), fast variable refresh rates, and is optimized for battery-powered and laser projection. It supports TI’s DLP472TP digital micromirror device and DLPA3085 LED driver. Availability and adoption are targeted for 2025 projectors and AR/VR devices.
Market Concentration & Characteristics
The Display Controller Market exhibits a moderately concentrated structure, with a mix of global technology leaders and specialized regional players shaping its competitive landscape. It features a high degree of technological advancement and innovation, driven by demand across diverse sectors such as consumer electronics, automotive, industrial automation, and healthcare. Major companies, including Samsung Electronics, Texas Instruments, LG Display, and STMicroelectronics, hold significant market shares through robust R&D capabilities, diverse product portfolios, and strong distribution networks. It relies heavily on continuous product upgrades to meet evolving display standards and end-user expectations. The market favors companies with strong semiconductor manufacturing capacity, efficient integration capabilities, and long-term partnerships with OEMs. Entry barriers remain high due to complex design requirements and capital-intensive development cycles. Demand concentration is highest in Asia Pacific, supported by a strong manufacturing base and consumer electronics consumption, followed by North America and Europe. It reflects fast technology turnover and high product replacement cycles, especially in consumer applications.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for display controllers will continue to rise with increasing adoption of high-resolution and energy-efficient displays.
- Integration of display controllers in automotive infotainment and digital instrument clusters will grow significantly.
- Advancements in touch and gesture control technologies will drive innovation in smart display controllers.
- The consumer electronics sector will remain the dominant application segment due to rising smartphone and smart TV usage.
- Industrial automation and medical equipment will present emerging opportunities for specialized display controller solutions.
- Asia Pacific will maintain its leadership in market share, supported by strong manufacturing capabilities and consumer demand.
- Companies will increasingly focus on miniaturization and integration of controllers to meet compact design requirements.
- Strategic collaborations and product innovations will define the competitive strategies of leading market players.
- Supply chain resilience and semiconductor availability will play a critical role in sustaining production growth.
- The shift toward connected devices and IoT ecosystems will enhance the demand for intelligent display controllers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the display controller market?
What drives the display controller market growth?
Which region leads the market?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Display Controller Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Display Controller Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 45,514.76 million → 2032: USD 92,409.97 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Display Controller Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Display Controller Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Display Controller Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Display Controller Market Drivers
- 3.3 Display Controller Market Restraints & Challenges
- 3.4 Display Controller Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Display Controller Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Display Controller Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Display Controller category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Display Controller Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Display Controller Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Display Controller. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Display Controller Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Display Controller Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Display Controller Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Display Controller (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Display Controller
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Display Controller Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Display Controller Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Display Controller Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Display Controller Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Display Controller Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Display Controller Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Display Controller Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Display Controller Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
