
Market Overview:
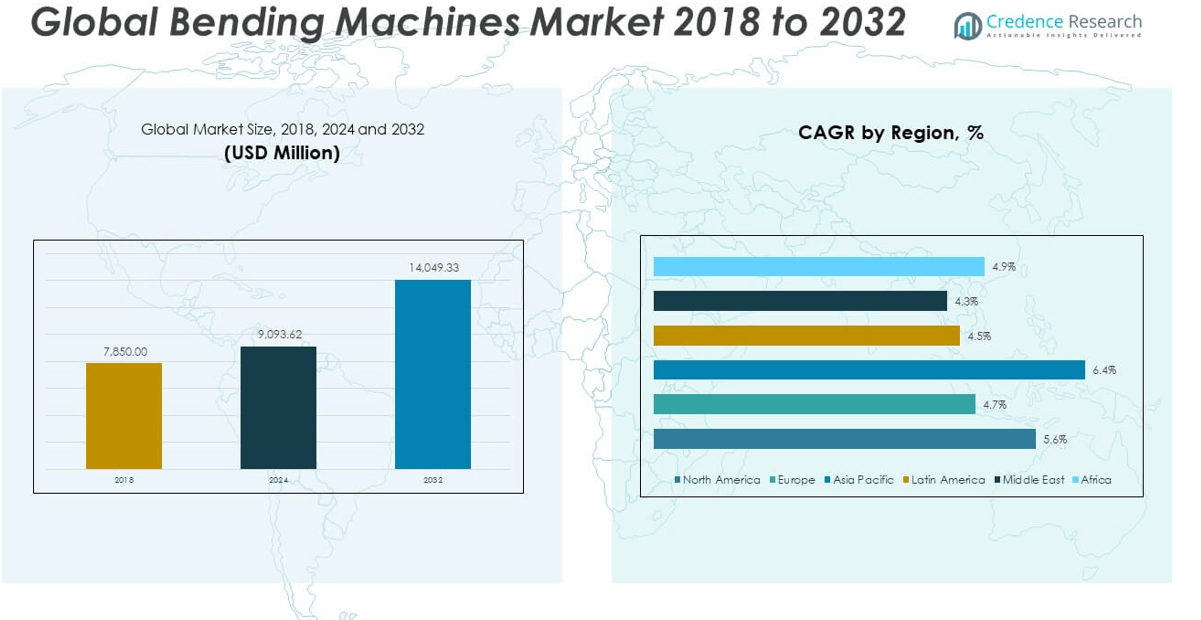
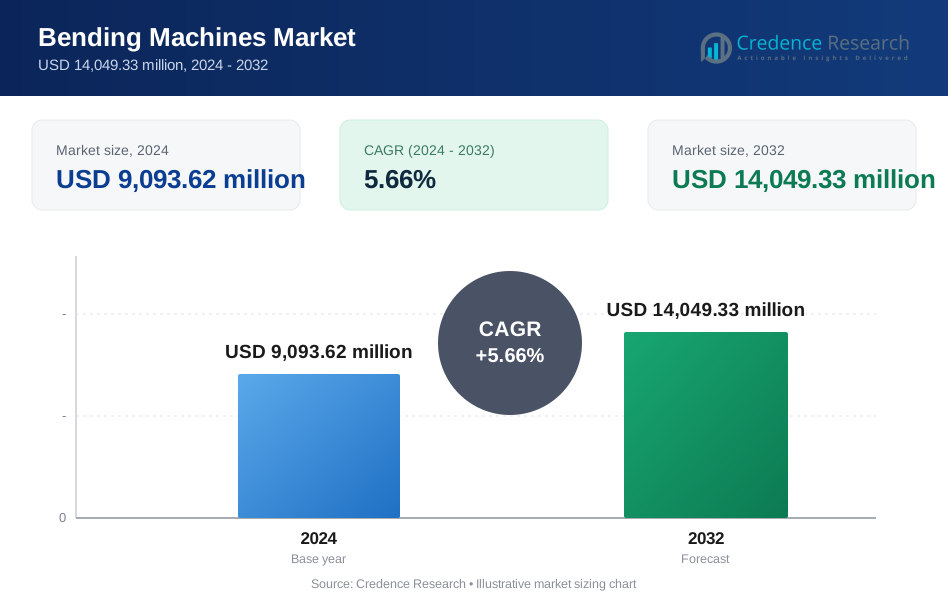
The Bending Machines Market size was valued at USD 7,850.00 million in 2018 to USD 9,093.62 million in 2024 and is anticipated to reach USD 14,049.33 million by 2032, at a CAGR of 5.66% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bending Machines Market Size 2024 | USD 9,093.62 million |
| Bending Machines Market, CAGR | 5.66% |
| Bending Machines Market Size 2032 | USD 14,049.33 million |
The growth of the bending machines market is primarily driven by the accelerating shift toward automation and precision manufacturing across diverse industries. Manufacturers are increasingly adopting CNC-based and servo-electric bending systems to enhance operational efficiency, reduce material wastage, and improve product consistency. The integration of Industry 4.0 technologies such as IoT, AI, and real-time monitoring is further reshaping the landscape by enabling predictive maintenance and remote diagnostics. Additionally, the expanding demand for lightweight and custom-formed components in automotive, aerospace, and construction sectors is creating substantial opportunities for machine vendors. In particular, the automotive industry is embracing bending machines for the fabrication of structural and body parts to meet evolving safety and emission standards. Moreover, growing awareness around energy-efficient and sustainable production practices is fueling the adoption of electric bending machines, which consume less power and produce lower emissions compared to hydraulic systems.
Asia-Pacific dominates the global bending machines market and is expected to maintain its leading position throughout the forecast period. The region’s growth is attributed to rapid industrialization, large-scale infrastructure development, and the presence of major manufacturing hubs in countries such as China, India, Japan, and South Korea. These nations are witnessing significant investment in automotive, aerospace, electronics, and construction sectors, all of which heavily rely on precision metal forming equipment. North America holds the second-largest market share, driven by the strong presence of technologically advanced industries in the United States and Canada. The region is characterized by early adoption of automation and a growing focus on energy-efficient manufacturing. Europe also commands a substantial share of the market, led by countries like Germany, France, and Italy, where high-end bending technologies are utilized in automotive and aerospace manufacturing. Meanwhile, the Middle East & Africa and Latin America are emerging as promising regions due to increasing investments in infrastructure and manufacturing.
Market Insights:
- The Bending Machines Market grew from USD 7,850.00 million in 2018 to USD 9,093.62 million in 2024, and is projected to reach USD 14,049.33 million by 2032, registering a CAGR of 5.66%.
- Automation and precision manufacturing are major growth drivers, with rising adoption of CNC and servo-electric systems replacing manual and hydraulic models across industries.
- Integration of Industry 4.0 technologies, including IoT, AI, and real-time monitoring, is transforming machine operations through predictive maintenance, remote diagnostics, and smart data-driven control.
- The automotive, aerospace, construction, and general machinery sectors are creating strong, sustained demand for bending machines due to increasing use of lightweight and custom-shaped components.
- Energy-efficient electric bending machines are gaining traction over traditional hydraulic systems, meeting both operational cost goals and environmental standards.
- Challenges include high capital investment, ongoing maintenance costs, and a shortage of skilled operators trained in advanced machine programming and operation.
- Asia Pacific dominates the global market with rapid industrialization in China, India, Japan, and South Korea, followed by North America and Europe which show strong adoption of automation and high-end bending technologies.
Market Drivers:
Automation and Precision Demands Are Driving Adoption of Advanced Bending Machines
Modern manufacturing facilities are embracing automation to improve productivity, accuracy, and consistency across operations. The Bending Machines Market benefits from this transition, with industries replacing manual and hydraulic systems with CNC-enabled machines that deliver tighter tolerances and faster output. These automated solutions reduce human error, improve safety, and support lean manufacturing goals. Industrial users prefer programmable machines that allow for quick setup changes and minimal downtime. The trend toward high-mix, low-volume production also favors flexible bending systems that can handle custom shapes and varying material types. Demand for automated precision equipment continues to grow across metalworking, sheet fabrication, and structural steel processing.
Industrial Expansion in Key End-Use Sectors Is Reinforcing Long-Term Market Growth
The construction, automotive, aerospace, and energy sectors are expanding globally, creating strong demand for metal-formed components. The Bending Machines Market is supported by the need to fabricate frames, enclosures, brackets, tubing, and reinforcement parts with consistent quality. The automotive industry, in particular, requires lightweight structural components to meet fuel efficiency standards, which increases usage of tube and pipe bending equipment. Infrastructure development in emerging economies further pushes demand for durable, large-capacity machines. The aerospace industry’s emphasis on structural integrity and material efficiency favors high-precision forming tools. Equipment suppliers are capitalizing on this surge in application-specific demand by offering industry-tailored bending solutions.
- For instance, electric tube benders from AMOB achieve energy savings of up to 50% over hydraulic models and can bend tubes with diameters up to 150 mm, meeting the stringent requirements for automotive and aerospace structural components.
Smart Manufacturing and Industry 4.0 Integration Is Enhancing Market Competitiveness
Manufacturers are integrating smart technologies such as IoT sensors, digital interfaces, and real-time monitoring systems into bending machines. This shift toward connected manufacturing allows users to optimize throughput, track machine performance, and implement predictive maintenance. The Bending Machines Market is experiencing a wave of innovation, where machines support remote diagnostics, cloud-based control systems, and adaptive tooling. These features enable manufacturers to respond quickly to design changes, reduce downtime, and lower operating costs. Factories adopting Industry 4.0 frameworks seek bending solutions that align with data-driven operations. This demand for intelligent equipment strengthens the value proposition of advanced bending systems.
Environmental Concerns and Operational Efficiency Requirements Are Influencing Equipment Choice
Energy efficiency, material conservation, and regulatory compliance are top priorities in capital equipment procurement. It benefits from the growing shift toward electric-drive systems that consume less power than traditional hydraulic counterparts. These machines offer quieter operation, lower maintenance, and precise motion control, aligning with sustainable production strategies. Manufacturers are also investing in machines that reduce scrap and optimize material usage through accurate bend radius control. The focus on waste minimization and lifecycle cost savings makes advanced bending machines a preferred choice. This sustainability-driven demand supports the continued evolution of the Bending Machines Market across all regions.
- For example, AMOB’s 100% electric tube benders use servo motors that only consume energy during active bending, resulting in up to 73% lower energy consumption compared to hydraulic systems.
Market Trends:
Integration of Hybrid Bending Systems Is Reshaping Product Capabilities
Manufacturers are adopting hybrid bending machines that combine the advantages of electric and hydraulic systems. These machines deliver the high force output of hydraulics with the precision and energy efficiency of electric drives. The Bending Machines Market is witnessing a shift toward such hybrid models to address varied application needs across industries. This integration enables smoother operation, higher cycle rates, and reduced power consumption. Equipment makers are focusing on modular designs that allow easy upgrades and adaptability. The rise of hybrid systems reflects growing end-user demand for versatile machines that balance performance and operational cost.
Customized Tooling and Application-Specific Machines Are Gaining Popularity
End users are increasingly seeking bending equipment tailored to specific production requirements. The market is responding with machines equipped with customized tooling, programmable bend sequences, and modular tool sets. The Bending Machines Market is evolving beyond standard models, offering systems designed for unique material types, part geometries, and bending angles. This customization enhances production speed and product consistency in niche applications such as aircraft panels, medical device tubing, and architectural structures. Vendors offering tailored solutions are gaining competitive edge by addressing complex fabrication needs. The trend reflects a shift toward more specialized and application-driven equipment sourcing.
Compact and Space-Efficient Machine Designs Are Becoming Standard in Urban Facilities
Space optimization has become a top priority for small and medium-sized manufacturers, especially in urban and high-rent regions. Equipment makers are introducing compact bending machines with vertical designs, foldable work tables, and integrated controllers. The Bending Machines Market is seeing greater demand from workshops and fabrication units looking to install high-performance equipment within tight floorplans. These compact designs do not compromise on power or functionality, making them ideal for decentralized or mobile operations. Manufacturers are also incorporating ergonomic features to improve operator comfort and reduce fatigue. This design shift aligns with the evolving needs of small-batch, high-frequency production setups.
- The Bystronic ByBend Star 40 & 80, for example, requires less than 6 square meters of floor space and can be operational in under 5 minutes after setup. Despite their compact size, these machines provide up to 80 tons of pressing force and a bending length of 1.5 meters, making them suitable for both small-batch and high-frequency production without sacrificing performance
Integration of Safety-Enhancing Features Is Becoming a Key Product Differentiator
Industrial safety standards are becoming stricter across global markets, driving a focus on safety-integrated machinery. Equipment manufacturers are embedding features such as light curtains, automatic shut-offs, force-limiting actuators, and interlocked guards. The Bending Machines Market is incorporating these safety features not only to meet compliance but also to appeal to risk-averse buyers. Advanced human-machine interfaces (HMIs) with visual alerts and error diagnostics are now common in newer models. Operators benefit from reduced accident risk and easier troubleshooting, while managers gain assurance of regulatory adherence. Safety-centric innovations are now influencing purchase decisions as much as performance and cost.
- For example, The Prima Power BCe Smart 2220 employs dual laser scanners and light curtains that automatically slow machine operation when an operator enters the safety zone, ensuring both productivity and safety.
Market Challenges Analysis:
High Capital Investment and Cost of Ownership Limit Widespread Adoption
One of the primary challenges facing the Bending Machines Market is the high upfront cost associated with advanced machinery. CNC, servo-electric, and hybrid models often require significant capital expenditure, making them inaccessible to small and medium-sized enterprises. Along with purchase cost, companies must account for installation, operator training, software licensing, and routine maintenance. These financial barriers can slow technology adoption, especially in price-sensitive markets or regions with limited industrial funding. It becomes difficult for smaller fabricators to justify the investment unless they operate in high-volume or high-margin sectors. Leasing or financing options exist but may not offer long-term relief for businesses with tight cash flows.
Skilled Labor Shortage and System Complexity Affect Operational Efficiency
Another pressing challenge is the shortage of skilled technicians capable of operating and maintaining modern bending equipment. Advanced systems often feature complex programming interfaces, automation protocols, and safety controls that require specialized knowledge. The Bending Machines Market is heavily affected by the lack of vocational training programs and slow workforce adaptation to digital manufacturing tools. Downtime due to operator error or maintenance delays can erode productivity and profitability. In many regions, experienced technicians are aging out of the workforce, leaving a gap that new entrants struggle to fill. This skills gap hampers efficient machine utilization and weakens the return on capital investment.
Market Opportunities:
Expansion of Renewable Energy and EV Infrastructure Opens New Avenues for Bending Equipment
The rapid development of renewable energy projects and electric vehicle infrastructure is creating significant growth potential for metal forming technologies. Wind turbine towers, solar panel frames, and EV battery enclosures require precision-bent components that support structural integrity and performance. The Bending Machines Market stands to benefit from increased demand for specialized equipment capable of handling large metal profiles and non-ferrous materials. Governments are investing heavily in clean energy and transportation, leading to new fabrication contracts and equipment procurement. It presents an opportunity for manufacturers to diversify product lines and cater to evolving energy sector needs. Customized solutions that meet industry-specific technical standards will gain stronger traction in the coming years.
Growth of Modular Construction and Prefabrication Fuels Demand for Flexible Bending Solutions
The rise of modular construction methods across commercial and residential sectors is driving the need for versatile bending machines. Prefabricated structural components must be shaped with accuracy, often in offsite production environments where space and turnaround time are limited. The Bending Machines Market can address this demand by offering compact, transportable, and digitally controlled machines tailored for construction firms and prefab manufacturers. It creates room for innovation in machine design, automation integration, and on-site usability. With construction trends shifting toward speed and precision, flexible bending solutions are well-positioned to meet market requirements.
Market Segmentation Analysis:
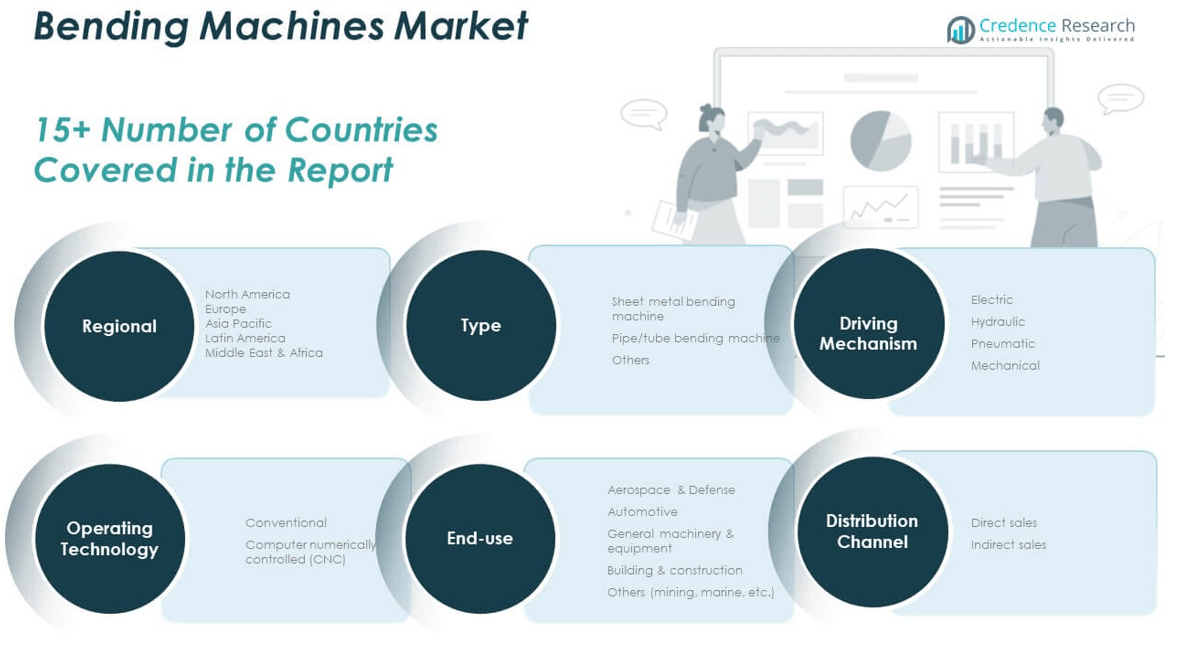
The Bending Machines Market is segmented by type, driving mechanism, operating technology, distribution channel, and end-use industry.
By type, sheet metal bending machines dominate due to widespread use in automotive, construction, and fabrication industries, while pipe/tube bending machines are essential for infrastructure and energy applications. Others include specialized equipment for custom or niche bending requirements.
- For example, the TRUMPF TruBend Series 5000 is a leading example, widely used in automotive and construction for its ability to process a variety of sheet metals with bending lengths up to 4 meters and pressing forces up to 320 tons.
By driving mechanism, hydraulic machines hold a significant share for their high force output and versatility, especially in heavy-duty operations. Electric bending machines are gaining momentum due to their energy efficiency and precision. Pneumatic and mechanical systems serve lower-load or legacy applications where cost or simplicity is a priority.
By operating technology, CNC bending machines lead the market due to their accuracy, repeatability, and integration with digital manufacturing environments. Conventional machines still retain presence in cost-sensitive or low-volume operations.
- For example, the Bystronic Xpert Pro features CNC control with automatic tool and part programming, achieving repeatability of ±0.003°, and is integrated into digital manufacturing lines for high-volume automotive and appliance production.
By distribution channel, direct sales are preferred for large-scale or custom equipment, while indirect sales serve broader regional and aftermarket needs.
By end-use industry, automotive leads in demand for precision and lightweight components, followed by aerospace, construction, and general machinery sectors. The Bending Machines Market continues to diversify across these applications, driven by automation, energy efficiency, and industry-specific requirements.
Segmentation:
By Type:
- Sheet Metal Bending Machine
- Pipe/Tube Bending Machine
- Others
By Driving Mechanism:
- Electric
- Hydraulic
- Pneumatic
- Mechanical
By Operating Technology:
- Conventional
- Computer Numerically Controlled (CNC)
By Distribution Channel:
- Direct Sales
- Indirect Sales
By End-use Industry:
- Aerospace & Defense
- Automotive
- General Machinery & Equipment
- Building & Construction
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Bending Machines Market size was valued at USD 1,993.90 million in 2018 to USD 2,269.71 million in 2024 and is anticipated to reach USD 3,489.71 million by 2032, at a CAGR of 5.6% during the forecast period. North America accounts for 24% of the global market share, driven by robust demand from the automotive, aerospace, and oil & gas sectors. The U.S. leads regional growth with strong adoption of CNC and servo-electric machines across fabrication plants and industrial workshops. High investments in smart factories and advanced manufacturing support the integration of intelligent bending systems. Equipment suppliers are focusing on offering energy-efficient and safety-compliant machines to meet industry standards. It benefits from a skilled labor force and well-established supply chains, which enhance operational efficiency and reliability. Government policies supporting domestic manufacturing continue to strengthen market performance across the region.
Europe
The Europe Bending Machines Market size was valued at USD 1,673.62 million in 2018 to USD 1,845.76 million in 2024 and is anticipated to reach USD 2,654.66 million by 2032, at a CAGR of 4.7% during the forecast period. Europe holds a 20% share in the global market, with Germany, France, and Italy leading demand due to their strong engineering and automotive industries. Manufacturers are adopting precision forming systems to meet evolving quality and performance standards across sectors such as aviation, construction, and rail transport. The region favors eco-efficient machines that comply with environmental regulations and lower operating costs. It also supports R&D investments aimed at improving automation, safety, and production flexibility. Technological innovation and policy incentives for energy-efficient machinery are driving capital upgrades. Compact and modular machines are also in demand to support urban manufacturing environments.
Asia Pacific
The Asia Pacific Bending Machines Market size was valued at USD 3,351.95 million in 2018 to USD 3,981.61 million in 2024 and is anticipated to reach USD 6,489.54 million by 2032, at a CAGR of 6.4% during the forecast period. Asia Pacific dominates the global market with a 43% share, supported by large-scale manufacturing activities in China, Japan, South Korea, and India. Regional industries demand high-capacity and high-speed bending systems to support rapid infrastructure growth and automotive production. Local and multinational vendors are expanding their presence to cater to growing fabrication needs in electronics, shipbuilding, and consumer goods. It benefits from lower production costs, skilled labor, and rising automation across industrial clusters. Governments are actively promoting smart manufacturing through subsidies and digital infrastructure projects. The region remains the most dynamic and high-potential market for bending equipment globally.
Latin America
The Latin America Bending Machines Market size was valued at USD 417.62 million in 2018 to USD 478.23 million in 2024 and is anticipated to reach USD 675.35 million by 2032, at a CAGR of 4.5% during the forecast period. Latin America represents 5% of the global market share, with Brazil and Mexico driving most of the regional demand. The growth is fueled by industrial expansion in automotive assembly, construction, and steel fabrication. Import-dependent markets are beginning to develop local capabilities, increasing the need for versatile and affordable bending solutions. It is witnessing a gradual shift from manual to semi-automated systems in small and medium manufacturing enterprises. Infrastructure modernization projects are creating new equipment opportunities across the region. Challenges such as currency fluctuation and uneven policy implementation continue to affect investment cycles.
Middle East
The Middle East Bending Machines Market size was valued at USD 296.73 million in 2018 to USD 321.86 million in 2024 and is anticipated to reach USD 448.25 million by 2032, at a CAGR of 4.3% during the forecast period. The Middle East holds a 3% share of the global market, primarily driven by demand from the UAE and Saudi Arabia. The region is focusing on infrastructure development, energy diversification, and industrial manufacturing under initiatives like Saudi Vision 2030. Demand for heavy-duty bending systems is increasing in construction, pipeline manufacturing, and defense-related projects. It is investing in automation to reduce reliance on imported labor and improve efficiency. Industrial parks and free zones are attracting global machinery providers looking to establish regional distribution hubs. Growth is steady, though affected by geopolitical uncertainty and fluctuating oil revenues.
Africa
The Africa Bending Machines Market size was valued at USD 116.18 million in 2018 to USD 196.46 million in 2024 and is anticipated to reach USD 291.82 million by 2032, at a CAGR of 4.9% during the forecast period. Africa accounts for 2% of the global market share, with South Africa, Egypt, and Nigeria leading regional consumption. The continent is gradually industrializing, creating demand for metal forming machinery in construction, mining, and transportation sectors. It is experiencing a slow transition from imported used machinery to entry-level new equipment. Access to financing and technical training remains limited, posing challenges for broader market penetration. International players are forming partnerships with local distributors to expand reach. Public infrastructure investments and industrial corridor projects offer long-term market opportunities.
Key Player Analysis:
- Amada Co., Ltd.
- Fidelity National Information Services, Inc. (FIS Inc.)
- Amob
- Baileigh Industrial
- BLM Group
- Bystronic Group
- Euromac
- Horn Machine Tools
- Murata Machinery
- Pedax
- Prima Industries
- Sahinler Metal Makina Industry
- Shuz Tung Machinery Industrial Co., Ltd.
- Transfluid Maschinenbau GmbH
- TRUMPF Group
- Wafios AG
- Finastra
Competitive Analysis:
The Bending Machines Market is highly competitive, with global and regional players focusing on innovation, customization, and automation to maintain market share. Leading companies such as Amada Co., Ltd., TRUMPF Group, Bystronic Group, and Mitsubishi Electric Corporation invest in advanced technologies, including CNC integration, servo-electric systems, and IoT-enabled diagnostics. It features a mix of large manufacturers offering full-service solutions and smaller firms targeting niche applications or regional demand. Companies compete on performance, energy efficiency, machine flexibility, and after-sales support. Strategic partnerships, product launches, and geographic expansion remain common approaches to gain an edge. Manufacturers are also emphasizing operator safety and machine versatility to meet evolving customer needs. Price sensitivity in emerging markets encourages suppliers to offer scalable, modular machines that align with local infrastructure and workforce capabilities.
Recent Developments:
- In April 2025, Fidelity National Information Services (FIS Inc.) announced a definitive agreement to acquire Global Payments’ Issuer Solutions division for $13.5 billion. This strategic move is expected to strengthen FIS’s position in the payments processing sector and is projected to close in the first half of 2026, pending regulatory approvals.
- In November 2024, BLM Group entered a strategic partnership with Hypertherm Associates, which included Hypertherm acquiring a minority stake in BLM. This collaboration is expected to generate commercial synergies and expand both companies’ reach, particularly in Europe and North America, without altering BLM’s organizational structure.
- In Feb 2023, TRUMPF Group announced the launch of its latest TruBend Series 8000, a high-precision bending machine designed for large-format sheet metal processing. This new product is aimed at enhancing productivity and flexibility for manufacturers working with oversized components, offering advanced automation features and improved energy efficiency.
Market Concentration & Characteristics:
The Bending Machines Market displays moderate concentration, with a mix of global leaders and regional players competing across segments. It is characterized by high technical complexity, strong focus on automation, and ongoing innovation in energy efficiency and control systems. Leading companies hold significant market share due to their advanced R&D capabilities and established distribution networks. The market favors suppliers that offer customizable solutions, integrated software, and reliable after-sales support. Barriers to entry remain relatively high due to capital intensity and technical expertise requirements. Competitive dynamics vary by region, with local firms serving cost-sensitive markets and global players targeting high-performance applications.
Report Coverage:
The research report offers an in-depth analysis based on type, driving mechanism, operating technology, distribution channel, and end-use industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for CNC-based bending machines will rise as manufacturers prioritize precision and automation.
- Integration of IoT and smart diagnostics will enhance machine monitoring and maintenance efficiency.
- Energy-efficient electric and hybrid models will gain traction in response to sustainability goals.
- Modular and compact machine designs will see higher adoption in space-constrained urban facilities.
- Growing investments in renewable energy and EV infrastructure will expand application opportunities.
- Asia Pacific will continue leading global growth, driven by industrial expansion and automation.
- Europe and North America will upgrade legacy systems to comply with evolving safety and quality standards.
- Manufacturers will focus on customized solutions tailored to niche industries and part geometries.
- Workforce training and digital skill development will become critical to support advanced machine use.
- Strategic alliances and regional expansion will shape competitive dynamics in emerging markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bending Machines Market?
What are the key segments within the Bending Machines Market?
What are some challenges faced by the Bending Machines Market?
Who are the major players in the Bending Machines Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bending Machines Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bending Machines Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,093.62 million → 2032: USD 14,049.33 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bending Machines Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bending Machines Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bending Machines Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bending Machines Market Drivers
- 3.3 Bending Machines Market Restraints & Challenges
- 3.4 Bending Machines Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bending Machines Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bending Machines Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bending Machines category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bending Machines Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bending Machines Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bending Machines market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bending Machines Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bending Machines Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bending Machines Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bending Machines (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bending Machines Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bending Machines Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bending Machines Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bending Machines Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bending Machines Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bending Machines Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bending Machines Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bending Machines Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bending Machines Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
