
Market Overview
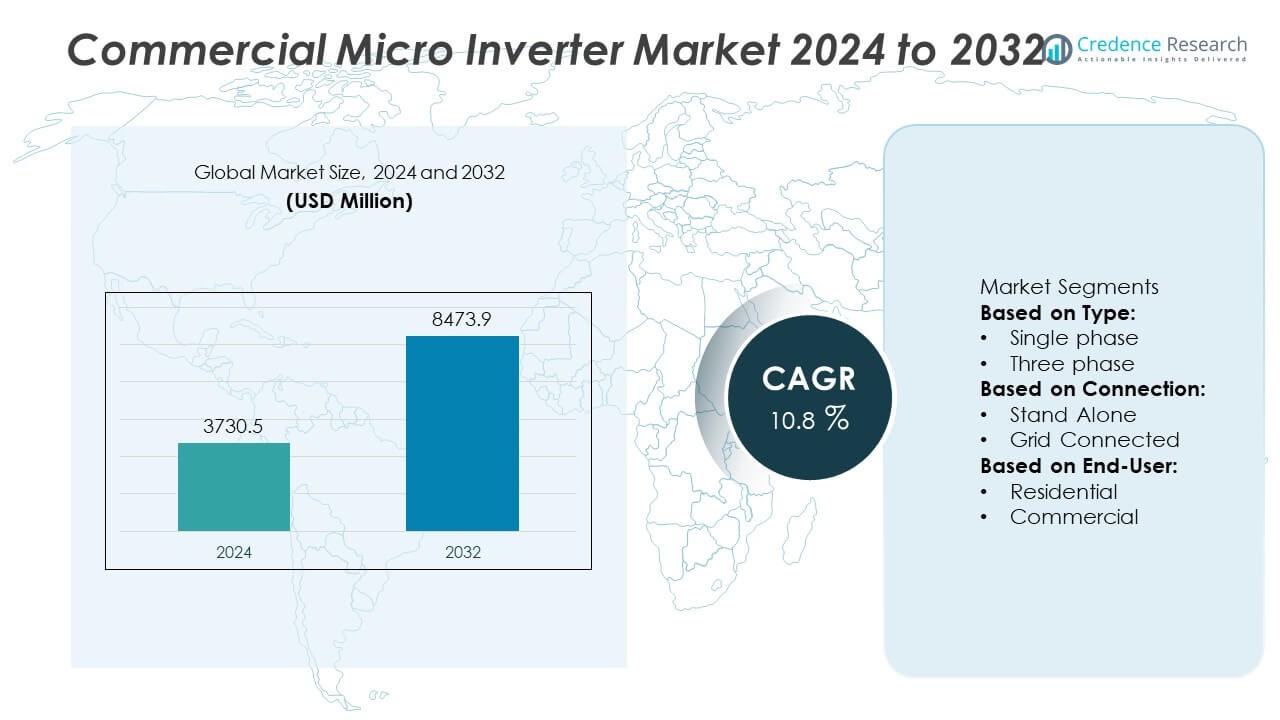
The Commercial Micro Inverter Market size was valued at USD 3,730.5 million in 2024 and is projected to reach USD 8,473.9 million by 2032, registering a CAGR of 10.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Commercial Micro Inverter Market Size 2024 | USD 3,730.5 Million |
| Commercial Micro Inverter Market, CAGR | 10.8% |
| Commercial Micro Inverter Market Size 2032 | USD 8,473.9 Million |
The Commercial Micro Inverter Market is driven by the rising adoption of solar energy solutions, increasing demand for high-efficiency power conversion, and growing emphasis on decentralized energy generation. It benefits from advancements in module-level power electronics that enhance system performance, reliability, and safety. Trends include integration of IoT and AI-based monitoring for real-time energy management, expanding adoption in large-scale commercial projects.
The Commercial Micro Inverter Market shows strong adoption across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, supported by expanding solar infrastructure and favorable renewable energy policies. North America leads in technological innovation and large-scale commercial installations, driven by advanced grid integration standards and high adoption of module-level power electronics. Europe benefits from stringent carbon reduction targets and strong incentives for distributed solar generation. Asia Pacific is experiencing rapid growth due to rising investments in solar projects in countries like China, India, and Australia, alongside increasing demand for energy efficiency in commercial buildings. Latin America and the Middle East & Africa are emerging markets, focusing on decentralized power solutions to address energy access challenges.
Market Insights
- The Commercial Micro Inverter Market was valued at USD 3730.5 million in 2024 and is projected to reach USD 8473.9 million by 2032, growing at a CAGR of 10.8% during the forecast period.
- Growth is driven by increasing adoption of solar PV systems in commercial buildings, demand for higher energy yield, and growing focus on renewable energy integration into smart grids.
- Key trends include the adoption of advanced MPPT technology, integration of IoT-enabled monitoring, and expansion of hybrid-ready micro inverters supporting both solar and storage systems.
- The market is competitive, with leading players such as Enphase, Deye Inverter, Darfon Electronics Corporation, Fimer Group, and Solis Solar focusing on high-efficiency designs, improved thermal performance, and scalable product ranges.
- High initial installation costs, complex maintenance in large-scale deployments, and dependency on semiconductor supply chains act as restraints for wider adoption.
- North America leads in adoption due to strong solar incentives and advanced grid regulations, Europe follows with carbon reduction mandates, and Asia Pacific is rapidly expanding due to large-scale solar investments in China, India, and Australia.
- Emerging markets in Latin America and the Middle East & Africa are witnessing growing demand driven by decentralized power needs, rural electrification programs, and government-backed renewable initiatives, creating opportunities for technology providers with adaptable product designs.
Market Drivers
Rising Demand for Distributed Solar Generation
The Commercial Micro Inverter Market benefits from the growing adoption of distributed solar generation systems across commercial buildings, retail complexes, and industrial facilities. Micro inverters enable module-level conversion, improving system performance in shaded or partially obstructed installations. It supports flexible system design and allows for incremental capacity expansion without complex rewiring. Enhanced safety features, such as rapid shutdown compliance, strengthen their adoption in regulated markets. Growing urban solar rooftop deployments create a consistent demand for solutions that maximize energy harvest. Technological improvements in efficiency and reliability further enhance their appeal to commercial users.
- For instance, Enphase’s IQ8 Series microinverters have undergone more than one million cumulative hours of powered-on testing and now carry an industry-leading warranty of 25 years.
Shift Toward Module-Level Power Optimization
Commercial solar projects increasingly prioritize module-level power optimization to address performance losses from panel mismatches, shading, or debris accumulation. The Commercial Micro Inverter Market responds with advanced designs that operate each panel independently, ensuring consistent energy output across the array. It reduces the impact of underperforming modules and simplifies troubleshooting. Integration with real-time monitoring platforms allows operators to track performance at a granular level. This capability improves maintenance efficiency and extends system lifespan. Demand is particularly strong in markets with diverse roof orientations and complex layouts.
- For instance, Deye's microinverters boast maximum efficiencies up to 96.5%, with MPPT accuracy above 99%, and operate reliably within a wide temperature range from –40°C to +65°C.
Regulatory Support and Renewable Energy Policies
Government incentives, net metering programs, and renewable energy mandates strongly influence the Commercial Micro Inverter Market. Many jurisdictions require compliance with safety standards that micro inverters meet more easily than string inverters. It aligns with grid modernization goals by enabling better energy management and integration with storage solutions. Policies supporting carbon reduction targets accelerate adoption in both developed and emerging markets. Regional subsidies and tax credits reduce the payback period, improving investment attractiveness. Growing utility participation in distributed generation projects also supports market growth.
Technological Advancements in Efficiency and Reliability
Continuous innovation drives the Commercial Micro Inverter Market, with manufacturers focusing on higher conversion efficiencies, extended product warranties, and improved thermal management. It enhances overall system output and reduces operational costs for commercial users. Integration with smart energy management systems enables load balancing and peak shaving capabilities. Advances in semiconductor technology improve power density and reduce component failure rates. Wireless communication features allow seamless integration with monitoring portals. These developments reinforce micro inverters as a preferred choice for high-performance commercial solar installations.
Market Trends
Growing Integration with Energy Storage Systems
The Commercial Micro Inverter Market is experiencing a shift toward solutions that seamlessly integrate with commercial-scale battery storage systems. This trend enables facilities to store excess solar power and use it during peak demand or grid outages. It supports energy independence and reduces reliance on conventional power sources. Manufacturers are developing micro inverters with bidirectional capabilities, allowing both charging and discharging functions. Compatibility with emerging battery chemistries, including lithium-ion and sodium-based storage, is expanding adoption. The combination of solar generation and storage enhances overall project ROI and grid resilience.
- For instance, Enphase has developed a bidirectional EV charger that can power a home during outages by discharging energy from the EV battery to the home or grid using their existing microinverter platform. This technology, called vehicle-to-home (V2H) and vehicle-to-grid (V2G).
Advancements in Monitoring and IoT Connectivity
Enhanced monitoring capabilities are shaping the Commercial Micro Inverter Market, with IoT-enabled devices providing real-time performance data at the module level. It allows operators to detect inefficiencies, faults, or shading issues quickly. Cloud-based dashboards and AI-driven analytics help optimize energy output and reduce maintenance costs. Remote firmware updates ensure systems remain compliant with evolving grid codes. Integration with building energy management systems offers centralized control and improved operational visibility. These innovations improve long-term reliability and performance transparency for commercial solar projects.
- For instance, data from the National Renewable Energy Laboratory showed that systems with IoT-enabled micro inverters achieved a 22% faster fault detection rate and reduced unscheduled maintenance visits by over 15 service hours per year compared to conventional monitoring setups.
Adoption of Higher Power Output Models
Increasing solar panel wattages are driving the demand for micro inverters capable of handling higher power outputs. The Commercial Micro Inverter Market is responding with designs supporting modules exceeding 500 W. It enables compatibility with the latest high-efficiency panels, ensuring optimal energy conversion. This evolution reduces the number of inverters required per installation, lowering installation complexity. Manufacturers are focusing on heat dissipation improvements to maintain performance under higher loads. Higher power handling capacity aligns with the trend toward maximizing energy generation in limited rooftop spaces.
Focus on Compliance with Grid Safety Standards
Evolving electrical safety standards are influencing product development in the Commercial Micro Inverter Market. It is driving innovation in rapid shutdown functions, anti-islanding protection, and voltage regulation. Compliance with codes such as NEC 2017 and IEC standards is now a competitive differentiator. Micro inverters inherently meet many of these requirements, which accelerates their acceptance in regulated markets. Manufacturers are incorporating advanced fault detection and arc-fault circuit interrupter (AFCI) technologies to enhance safety. This focus on regulatory alignment ensures long-term viability and market expansion opportunities.
Market Challenges Analysis
High Initial Costs and Installation Complexity
The Commercial Micro Inverter Market faces challenges from the higher upfront costs compared to traditional string inverters. It requires more units per installation, which increases material and labor expenses for large-scale projects. The distributed architecture also demands careful planning to ensure compatibility with existing electrical systems and local grid regulations. Installers must possess specialized training to manage module-level electronics effectively, adding to operational costs. This complexity can discourage adoption among cost-sensitive commercial operators, particularly in emerging markets. Manufacturers are working to streamline installation processes and reduce per-unit pricing, but economic barriers remain a significant constraint.
Durability Concerns in Harsh Operating Environments
Micro inverters operate in close proximity to solar panels, exposing them to extreme temperatures, humidity, and UV radiation. The Commercial Micro Inverter Market must address concerns about long-term reliability under such conditions. Failures at the module level can require more frequent maintenance interventions compared to centralized systems. Downtime in commercial applications leads to revenue losses, intensifying the impact of reliability issues. Manufacturers are enhancing enclosure protection ratings, thermal management systems, and component quality to extend service life. However, the perception of shorter operational lifespans compared to central inverters continues to challenge wider market adoption.
Market Opportunities
Rising Demand for Module-Level Power Optimization
The Commercial Micro Inverter Market is positioned to benefit from the growing need for module-level performance optimization in diverse installation environments. It allows individual solar panels to operate independently, reducing output losses from shading, soiling, or module mismatch. This capability is particularly valuable for complex commercial rooftops with varied orientations and obstructions. The shift toward high-efficiency solar modules further strengthens demand for inverters that can maximize power harvest from each unit. Businesses seeking to enhance return on investment are adopting micro inverters to achieve higher energy yields over system lifetimes. This trend creates strong opportunities for manufacturers that offer scalable, high-reliability solutions tailored for large commercial arrays.
Integration with Smart Energy Management Systems
The integration of micro inverters with advanced monitoring and smart energy management platforms presents a significant growth avenue for the Commercial Micro Inverter Market. It enables real-time tracking of energy production, system diagnostics, and predictive maintenance at the module level. These features align with the increasing adoption of IoT and AI-driven analytics in commercial energy infrastructure. The capability to integrate with battery storage systems and demand response programs also enhances value for building owners. As energy regulations push for greater grid interactivity, micro inverters with advanced communication protocols and remote control capabilities will gain preference. Vendors that deliver seamless interoperability with energy management ecosystems can capture a competitive advantage in this expanding segment.
Market Segmentation Analysis:
By Type
The Commercial Micro Inverter Market is segmented by type into single-phase and three-phase micro inverters. Single-phase units are commonly deployed in smaller commercial installations and facilities with lower load requirements. They offer ease of installation, cost efficiency, and compatibility with smaller arrays. Three-phase micro inverters dominate larger commercial projects where higher power output and balanced load distribution are critical. It ensures improved grid stability, reduced transmission losses, and optimized performance for industrial-scale systems. The increasing deployment of high-capacity solar modules in commercial rooftops is boosting demand for three-phase micro inverters, particularly in manufacturing facilities, warehouses, and large retail complexes.
- For instance, Enphase’s IQ8A three-phase micro inverter delivers a peak output power of 366 VA per phase with 97% CEC efficiency, enabling stable operation in commercial rooftops exceeding 500 kW capacity as documented in its 2024 technical datasheet.
By Connection
Market segmentation by connection includes wired and wireless configurations. Wired micro inverters maintain strong adoption in the Commercial Micro Inverter Market due to their proven reliability, reduced interference risks, and robust data transmission in harsh environments. They are preferred in large-scale projects where stable, high-speed communication between modules and monitoring systems is essential. Wireless micro inverters are gaining traction for their flexibility in installation, lower cabling costs, and simplified system expansion. It supports easier deployment in complex roof layouts and retrofitting scenarios. The advancement of secure wireless protocols and improved signal range is expected to strengthen the appeal of wireless solutions for future commercial installations.
- For instance, APsystems’ DS3 wireless-ready micro inverter uses a 2.4 GHz Zigbee communication module with an effective outdoor range of 300 m, while maintaining encrypted data transfer as verified in its UL 1741 compliance report.
By End-User
The Commercial Micro Inverter Market serves diverse end-user segments, including commercial buildings, industrial facilities, and institutional establishments. Commercial buildings such as office complexes, shopping centers, and hospitality venues deploy micro inverters to maximize rooftop solar efficiency while maintaining aesthetics and minimizing downtime. Industrial facilities adopt these systems to power high-load operations with reliable, module-level performance monitoring, ensuring minimal production disruption. It also finds adoption in institutions like schools, hospitals, and government buildings, where energy reliability and operational continuity are critical. Growing sustainability commitments and renewable energy targets across these sectors are driving investments in micro inverter-based solar systems, reinforcing their role as a key component of commercial solar infrastructure.
Segments:
Based on Type:
- Single phase
- Three phase
Based on Connection:
- Stand Alone
- Grid Connected
Based on End-User:
- Residential
- Commercial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds 37% of the Commercial Micro Inverter Market, supported by strong renewable energy adoption, favorable government incentives, and mature solar infrastructure. The United States leads regional demand, driven by state-level clean energy mandates and investment tax credits that encourage commercial solar deployment. Canada is expanding its adoption through net metering policies and corporate sustainability commitments. It benefits from the presence of leading micro inverter manufacturers and strong supply chain networks that ensure consistent product availability. Technological advancements, such as integrated monitoring platforms and high-efficiency three-phase models, further strengthen adoption across commercial rooftops and industrial installations. Rising energy costs and the shift toward decentralized power generation continue to drive market penetration in this region.
Europe
Europe accounts for 29% of the Commercial Micro Inverter Market, fueled by ambitious renewable energy targets under the European Green Deal and country-specific solar incentives. Germany, France, and the Netherlands are key contributors, with widespread rooftop solar integration in commercial and industrial sectors. The region’s strict grid compliance standards and focus on high-quality installations favor micro inverters due to their safety features, module-level optimization, and ability to meet EN 50549 and other local standards. It also benefits from increased adoption in southern Europe, where high solar irradiation supports greater returns on investment. The integration of storage solutions with micro inverters is gaining traction in markets like Italy and Spain, supporting energy independence and peak shaving strategies for businesses.
Asia Pacific
Asia Pacific holds 23% of the Commercial Micro Inverter Market, with rapid growth driven by urbanization, industrial expansion, and rising corporate investments in clean energy. Australia leads in adoption due to favorable feed-in tariffs and high solar penetration in commercial properties. China is emerging as a strong market with large-scale manufacturing capabilities and supportive solar policies in industrial parks and export-driven facilities. Japan’s strict building regulations and demand for high-efficiency, space-saving systems contribute to micro inverter deployment in dense urban environments. India’s growing commercial solar segment benefits from falling installation costs and corporate sustainability programs. It is further boosted by government-led rooftop solar initiatives that encourage SMEs and institutions to adopt distributed solar solutions.
Latin America
Latin America represents 6% of the Commercial Micro Inverter Market, led by Brazil, Mexico, and Chile. Brazil’s net metering regulations and expanding commercial rooftop installations drive demand, while Mexico leverages solar to reduce operational costs in retail and manufacturing. Chile’s mining sector increasingly integrates solar power to offset high energy expenses in remote locations. It is supported by partnerships between international inverter suppliers and local EPC (Engineering, Procurement, and Construction) companies, enabling efficient deployment in diverse geographical conditions. The region’s abundant solar resources and supportive policy frameworks are expected to sustain steady growth in the coming years.
Middle East & Africa
The Middle East & Africa hold 5% of the Commercial Micro Inverter Market, with growth concentrated in Gulf Cooperation Council (GCC) countries and South Africa. The UAE and Saudi Arabia are driving demand through large-scale commercial solar projects aligned with their national renewable energy targets. South Africa’s adoption is fueled by the need for reliable power supply in response to grid instability and load-shedding issues. It benefits from falling solar component costs and the integration of micro inverters with battery storage systems to provide consistent energy for commercial operations. Ongoing infrastructure investments and favorable climate conditions offer strong potential for market expansion in this region.
Key Player Analysis
- Fenice Energy
- Sparq Systems
- Sensol
- SunEvo Solar
- Fimer Group
- Enphase
- Solis Solar
- Statcon Energiaa
- Darfon Electronics Corporation
- Deye Inverter
Competitive Analysis
The Commercial Micro Inverter Market features strong competition among established global players and emerging regional manufacturers. Leading companies include Enphase, Deye Inverter, Darfon Electronics Corporation, Fimer Group, Fenice Energy, Sparq Systems, Sensol, Statcon Energiaa, SunEvo Solar, and Solis Solar. Enphase maintains a dominant position with its high-efficiency IQ series, offering advanced grid support features and remote monitoring capabilities. Deye Inverter focuses on scalable micro inverter solutions with multiple MPPT inputs for optimal energy harvesting in varying conditions. Darfon Electronics Corporation delivers compact, lightweight designs targeting ease of installation and low maintenance in commercial solar arrays. Fimer Group emphasizes durability and high power output for large-scale deployments, supported by strong service networks. Fenice Energy and Solis Solar are expanding through cost-competitive offerings tailored for high-growth markets in Asia and Latin America. Sparq Systems and Sensol drive innovation in modular designs and integrated storage compatibility. Statcon Energiaa and SunEvo Solar strengthen their regional presence through customized solutions meeting local regulatory and grid requirements. Together, these players compete through efficiency advancements, product reliability, and integration with smart energy management platforms.
Recent Developments
- In November 2024, Enphase enabled seamless system expansions by allowing IQ8 Series microinverters to integrate with existing IQ7 microinverters through automatic software updates-no additional gateway required.
- In February 2024, Enphase Energy announced the launch of its new IQ8P Microinverter, designed to support higher-powered solar panels up to 480 W. This innovation aligns with the growing trend toward more powerful residential PV systems. It offers improved energy harvesting and faster installation.
- In July 2023, Enphase Energy has started shipping its first U.S.-made microinverters from Columbia, South Carolina. This move is part of their strategy to expand manufacturing within the United States.
Market Concentration & Characteristics
The Commercial Micro Inverter Market is moderately concentrated, with a mix of established multinational manufacturers and emerging regional players competing through product innovation and geographic expansion. It is characterized by rapid technological advancements, particularly in high-efficiency, grid-compliant designs that enhance energy harvest and operational reliability. Leading vendors focus on integrating advanced MPPT (Maximum Power Point Tracking) capabilities, higher power ratings, and IoT-based monitoring features to differentiate their offerings. The market benefits from strong demand in regions with high solar adoption rates, where stringent grid standards and incentive programs drive performance-focused solutions. Competitive dynamics are shaped by partnerships with EPC contractors, distribution networks, and solar module manufacturers to expand market reach. Vendors with strong R&D pipelines, scalable manufacturing, and proven installation track records maintain a distinct advantage. It continues to evolve toward solutions that offer simplified installation, longer warranty periods, and compatibility with diverse commercial solar configurations, supporting wider adoption across global markets.
Report Coverage
The research report offers an in-depth analysis based on Type, Connection, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will increase with the expansion of commercial solar installations across developed and emerging markets.
- Integration of advanced MPPT technology will enhance system efficiency and energy yield.
- Adoption of IoT-enabled micro inverters will grow for real-time performance monitoring and predictive maintenance.
- Hybrid and energy storage-compatible models will gain traction in regions promoting self-consumption.
- Manufacturers will focus on expanding global distribution networks to capture new markets.
- Stringent grid compliance regulations will drive innovation in safety and reliability features.
- Modular and scalable designs will support larger commercial rooftop and ground-mounted systems.
- Partnerships between inverter manufacturers and solar module producers will strengthen product integration.
- Increased investment in R&D will lead to higher power ratings and extended product lifespans.
- Asia Pacific and Middle East markets will see rapid adoption supported by favorable policy frameworks.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Commercial Micro Inverter, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Commercial Micro Inverter market projected to grow between 2025 and 2032?
Which Commercial Micro Inverter market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Commercial Micro Inverter market?
Who are the leading companies in the Commercial Micro Inverter market?
Which region commanded the largest share of the Commercial Micro Inverter market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Commercial Micro Inverter Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Commercial Micro Inverter Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,730.5 million → 2032: USD 8,473.9 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Commercial Micro Inverter Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Commercial Micro Inverter Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Commercial Micro Inverter Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Commercial Micro Inverter Market Drivers
- 3.3 Commercial Micro Inverter Market Restraints & Challenges
- 3.4 Commercial Micro Inverter Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Commercial Micro Inverter Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Commercial Micro Inverter Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Commercial Micro Inverter category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Commercial Micro Inverter Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Commercial Micro Inverter Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Commercial Micro Inverter. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Commercial Micro Inverter Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Commercial Micro Inverter Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Commercial Micro Inverter Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Commercial Micro Inverter (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Commercial Micro Inverter
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Commercial Micro Inverter Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Commercial Micro Inverter Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Commercial Micro Inverter Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Commercial Micro Inverter Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Commercial Micro Inverter Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Commercial Micro Inverter Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Commercial Micro Inverter Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Commercial Micro Inverter Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
