
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
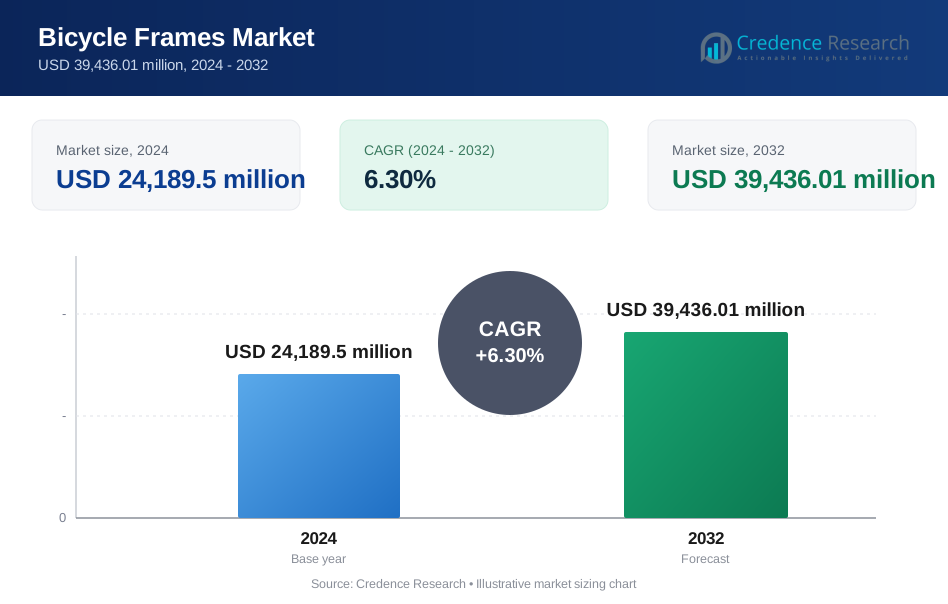
| Bicycle Frames Market Size 2024 | USD 24,189.5 Million |
| Bicycle Frames Market, CAGR | 6.30% |
| Bicycle Frames Market Size 2032 | USD 39,436.01 Million |
Market Overview
The Bicycle Frames Market is projected to grow from USD 24,189.5 million in 2024 to USD 39,436.01 million by 2032, achieving a compound annual growth rate (CAGR) of 6.30%.
The bicycle frames market is driven by the increasing popularity of cycling as a sustainable mode of transportation and a fitness activity. Rising environmental concerns and government initiatives promoting eco-friendly practices further boost demand for bicycles. Technological advancements in materials, such as lightweight carbon fiber and aluminum alloys, enhance frame performance and durability. Additionally, the growing trend of electric bicycles (e-bikes) is expanding market opportunities, as consumers seek innovative solutions for commuting and recreational purposes. These drivers and trends collectively contribute to the robust growth of the bicycle frames market.
The global bicycle frames market is geographically diverse, with significant growth in regions like Asia-Pacific and Europe. Asia-Pacific dominates the market, driven by countries such as China and Taiwan, known for large-scale production and exports of bicycle frames. Europe follows closely due to increasing cycling culture and government initiatives promoting eco-friendly transportation. Key players include Hero Cycles, MERIDA BIKES, and Dengfu Sports Equipment Co., Ltd., leading the market with innovative frame designs and advanced materials. Other prominent companies like Kinesis Industry Co., Ltd. and LightCarbon Composite Technology Co., Ltd. further enhance market competitiveness.
Market Drivers
Growing Interest in Cycling
Cycling has surged in popularity as a recreational activity, exercise option, and sustainable mode of transportation. This growing interest has led to increased demand for bicycles, subsequently driving the need for bicycle frames. For instance, a recent survey revealed that millions of people participate in cycling daily, with the number of bicycles sold in the European Union amounting to over 22 million. As more individuals embrace cycling for its health benefits and environmental advantages, manufacturers are poised to meet this rising demand with a diverse range of bicycle frames catering to various preferences and performance levels. The shift towards cycling as a primary mode of transport reflects a broader trend towards active lifestyles and eco-friendly commuting.
Health and Fitness Awareness The rising awareness of health and fitness is a significant driver of the bicycle frames market. As individuals become more conscious of their health, cycling is increasingly recognized as an effective way to stay active and fit. For instance, the World Health Organization (WHO) highlights that regular physical activity, including cycling, provides significant physical and mental health benefits, such as reducing the risk of cardiovascular diseases, diabetes, and depression. The promotion of cycling as a low-impact, enjoyable exercise option has encouraged more people to invest in bicycles, leading to a corresponding increase in demand for high-quality bicycle frames. This heightened focus on health underscores cycling’s role as an essential activity for maintaining physical well-being in today’s fast-paced lifestyle.
Urbanization and Traffic Congestion
Increasing urbanization and worsening traffic congestion are pivotal factors contributing to the bicycle frames market's growth. As cities become more crowded, cycling emerges as a viable alternative to cars, offering a solution to the challenges of urban transport. This shift in commuting preferences has resulted in a surge in demand for bicycles, which directly influences the need for bicycle frames. The convenience and efficiency of cycling in congested urban environments make it an attractive choice for commuters seeking to navigate their cities more effectively.
Technological Advancements and Customization
Technological advancements in frame materials and design have significantly impacted the bicycle frames market. Innovations such as carbon fiber and titanium allow for the creation of lighter, stronger, and more durable frames, appealing to cyclists seeking high-performance equipment. Additionally, the growing trend of customization and personalization in bicycle design has fueled demand for frames that can be tailored to individual preferences and needs. This focus on innovation and personalization enhances the market's dynamism, attracting a diverse customer base eager to invest in bicycles that reflect their unique styles and requirements.
Market Trends
Lightweight Materials and Customization Trends
The bicycle frames market is witnessing a significant shift towards lightweight materials and advanced construction techniques. Carbon fiber continues to dominate the high-end segment, celebrated for its exceptional strength-to-weight ratio, allowing manufacturers to produce frames that offer both performance and agility. For instance, companies like Specialized and Trek have reported that their carbon fiber frames are preferred by professional cyclists for their lightweight and robust nature. Titanium frames provide a compelling balance between strength and weight, catering to premium buyers seeking durability and a refined ride experience. Aluminum remains a popular choice for mid-range frames due to its affordability and robustness, while emerging specialized alloys are enhancing frame properties, such as fatigue resistance and corrosion protection. In addition to material advancements, customization and personalization are becoming key trends in the industry. Modular designs enable riders to interchange parts based on their unique riding styles and preferences, fostering a more tailored cycling experience. Advances in 3D printing technology further amplify this trend by allowing for the creation of highly customized frames with unique geometries, enabling cyclists to own bikes that truly reflect their individual needs and aesthetics. These trends signify a broader shift towards enhancing performance and personal expression in cycling.
Integration of Technology and Sustainability
The integration of technology into bicycle frames is increasingly prominent, reshaping the cycling experience. Specialized e-bike frames are designed to accommodate electric bike components such as batteries and motors, responding to the growing demand for electric-assisted cycling. Foldable frames are also gaining traction, particularly for urban commuting, as they offer convenience in storage and transport. Simultaneously, the industry is moving towards sustainability and eco-friendly materials. Manufacturers are exploring the use of recycled materials to minimize environmental impact, while natural materials like bamboo and wood are rising in popularity for their aesthetic appeal and sustainability credentials. This focus on environmentally responsible practices is driving innovation and attracting environmentally conscious consumers. Additionally, there is a growing emphasis on comfort and ergonomics, with frame geometries being refined to enhance handling and rider comfort across various riding styles. Adjustable features, including customizable seatposts and handlebars, allow cyclists to achieve optimal fit and comfort, further improving the overall riding experience. Collectively, these trends reflect a market evolution that prioritizes performance, personalization, and sustainability, catering to the diverse needs of modern cyclists.
Market Challenges Analysis
High Manufacturing Costs and Global Supply Chain Disruptions
The bicycle frames market faces significant challenges stemming from high manufacturing costs and global supply chain disruptions. The production of high-quality bicycle frames often necessitates the use of expensive materials such as carbon fiber and titanium, which can substantially inflate manufacturing expenses. For instance, according to a report by the World Economic Forum, the cost of carbon fiber production is significantly higher than that of traditional materials due to the complex manufacturing processes involved. Additionally, the requirement for skilled labor in frame production further exacerbates these costs. Advanced manufacturing techniques, including 3D printing and carbon fiber layup, while innovative, are also capital-intensive, creating financial barriers for manufacturers looking to adopt these technologies. Compounding these challenges is the dependence on global supply chains for raw materials. Disruptions due to geopolitical events, natural disasters, or economic fluctuations can lead to delays and increased costs, forcing manufacturers to adapt quickly to shifting conditions. Furthermore, manufacturing facilities located in different regions may encounter additional hurdles, such as labor shortages, transportation issues, and trade restrictions, which can hinder production efficiency and overall profitability. These combined factors create a precarious landscape for manufacturers as they strive to balance quality, cost, and supply chain reliability.
Intense Competition and Environmental Concerns
The bicycle frames market is also marked by intense competition and environmental concerns that challenge manufacturers. Established brands wield significant market power due to strong brand recognition and customer loyalty, making it difficult for new entrants to carve out a share of the market. This competitive pressure often leads to price wars, forcing manufacturers to lower prices and compromising their ability to maintain profitability. Additionally, the rapid pace of technological advancements poses a unique challenge, as manufacturers must stay abreast of the latest trends to avoid obsolescence in their product offerings. As consumer preferences shift, manufacturers face difficulties in accurately predicting demand, which can result in stockouts or excess inventory that hampers profitability. On the environmental front, the production processes, particularly for carbon fiber frames, can have a substantial carbon footprint, raising concerns among consumers and regulators alike. Increasingly stringent environmental regulations impose additional compliance burdens and costs on manufacturers, compelling them to adopt more sustainable practices. This complex interplay of competition, consumer expectations, and regulatory requirements creates a challenging environment where manufacturers must innovate and adapt to remain competitive while addressing their environmental impact.Top of Form
Market Segmentation Analysis:
By Method: The bicycle frame market is segmented based on production methods, with Traditional and Hydroforming Casting techniques playing a significant role. Traditional methods, which have been used for decades, rely on techniques like welding and brazing to assemble bicycle frames. These methods are commonly used for steel and aluminum frames and remain popular due to their cost-effectiveness and accessibility for manufacturers. In contrast, Hydroforming Casting is a more advanced method that involves shaping metal tubes under high pressure. This technique is preferred for creating lightweight, high-strength frames made from materials such as aluminum and carbon fiber. Hydroforming allows for more complex frame designs and improves the frame's strength-to-weight ratio, making it ideal for performance-focused bicycles. The growing demand for lightweight, durable, and efficient frames has led to increased adoption of hydroforming casting methods in high-end and performance bike models.
By Type: The market is also categorized by bicycle type, with Electric Bicycles (E-Bikes) and Muscular Bikes (Non-Electric Bikes) representing two major segments. E-Bikes have gained traction due to their convenience and growing demand for eco-friendly transportation. These frames are designed to accommodate electric components such as batteries and motors, requiring sturdier, more robust materials to handle the added weight and torque. On the other hand, Muscular Bikes (non-electric) remain highly popular, especially among fitness enthusiasts and recreational cyclists. These frames emphasize lightweight design and performance, appealing to cyclists who prioritize speed and agility. The shift towards electric bikes is driving innovation in frame design, especially for urban commuters, while traditional non-electric bikes continue to dominate in sports and leisure categories. Both segments contribute to the growing diversity and technological advancements in the bicycle frame market.
Segments:
Based on Method:
- Traditional
- Hydroforming Casting
Based on Type:
- Electric Bicycle (E-Bike)
- Muscular Bike (Non-Electric Bike)
Based on Frame Type:
- Moto-Style Frames
- Step-Through Frames
- Mountain Bike Frames
- Road or Step-Over Frames
- City Bike Frames
- Folding Bike Frames
- Hybrid Bike Frames
- Cargo Bike Frames
Based on Frame Material:
- Aluminum
- Steel
- Titanium
- Carbon Fibers
Based on Application:
- City/Urban
- Mountain/Trekking
- Others
Based on Manufacturing Model:
- OEM/ODM
- OBM
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share in the global bicycle frames market, accounting for approximately 25% of the total market share. The region's demand is driven by the growing adoption of bicycles for recreational activities, fitness, and commuting in urban areas. Rising awareness of environmental sustainability and increasing investments in cycling infrastructure, such as bike lanes and shared biking programs, have further fueled the demand for bicycles and frames. The surge in popularity of electric bicycles (E-bikes) in cities like New York and San Francisco has also contributed to the market's growth, particularly in the high-performance and urban commuter segments. Additionally, the presence of major manufacturers and the increasing trend toward lightweight materials, like carbon fiber and titanium, in performance bikes are shaping market developments in North America.
Europe: Europe holds the largest market share, accounting for over 30% of the global bicycle frames market. This region's dominance is attributed to the strong cycling culture, particularly in countries like the Netherlands, Germany, and Denmark, where bicycles are a primary mode of transportation. Government initiatives promoting cycling as a sustainable alternative to cars, combined with extensive cycling infrastructure, have spurred demand for bicycle frames across the continent. Europe is also witnessing a rapid rise in the adoption of E-bikes, especially in urban areas, as cities push for greener commuting options to reduce traffic congestion and pollution. Moreover, European consumers' preference for high-quality, durable frames made from eco-friendly materials is influencing manufacturers to adopt sustainable production practices and innovative frame designs, making Europe a leading market for premium and performance bicycle frames.
Key Player Analysis
- Hero Cycles
- LightCarbon Composite Technology Co., Ltd.
- AD Group
- MERIDA BIKES
- Maxway Cycles Co., Ltd.
- Kinesis Industry Co., Ltd.
- Romet
- Dengfu Sports Equipment Co., Ltd.
- VDL Bike Frame Technologies
- INT'L Corp
Competitive Analysis
The bicycle frames market is highly competitive, with leading players focusing on innovation, material advancements, and product diversification to maintain market share. Companies like Maxway Cycles Co., Ltd., Kinesis Industry Co., Ltd., LightCarbon Composite Technology Co., Ltd., AD Group, Dengfu Sports Equipment Co., Ltd., MERIDA BIKES INT'L Corp, Romet, VDL Bike Frame Technologies, and Hero Cycles lead the market. These companies invest in research and development to create lightweight, durable frames made from advanced materials like carbon fiber and titanium. They also emphasize customization, offering a variety of frame designs catering to different riding styles. Competitive strategies include expanding product lines, enhancing production efficiency, and exploring eco-friendly materials to meet growing consumer demand for sustainable options. Additionally, partnerships and acquisitions help these key players strengthen their global presence and customer base, making the competitive landscape dynamic and ever-evolving.
Recent Developments
- In December 2023, Light Carbon Composite Technology announced a new foldable ebike, the LCE-XO, with a carbon fiber frame and carbon fiber fork, made by Toray T700 mixed with T800 high-modulus carbon fiber layers.
- In July 2023, Trek introduced an electric bike variant of its Fuel EXe, featuring an alloy frame. This new electric mountain bike maintains the same geometry and utilizes a 150/140mm travel suspension layout, aligning with the design characteristics of its carbon counterparts.
- In June 2023, Portuguese group Semapa completed 100 percent acquisition of bike frame maker Triangle's for 195 million dollars.
- In January 2023, Fujitsu and Teijin started joint trials with V Frames and Advanced Bikes to increase the recycled materials environmental value in the bicycle frames that V Frames GmbH produces
Market Concentration & Characteristics
The bicycle frames market is moderately concentrated, with a mix of global and regional players driving competition. Leading manufacturers, such as Maxway Cycles Co., Ltd., Kinesis Industry Co., Ltd., and MERIDA BIKES INT'L Corp, hold a significant market share due to their advanced technologies, strong brand presence, and extensive distribution networks. The market is characterized by a growing focus on innovation, particularly in frame materials like carbon fiber, titanium, and lightweight alloys. Companies are increasingly adopting eco-friendly manufacturing processes to cater to the rising demand for sustainable products. Additionally, customization and personalization are key trends, with consumers seeking tailored solutions for specific riding preferences. Despite the presence of dominant players, smaller manufacturers are also finding niche opportunities by offering specialized or affordable options, adding diversity to the market landscape. Overall, the market is dynamic, with innovation and sustainability acting as key competitive factors.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Method, Type, Frame Type, Frame Material, Application, Manufacturing Model and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for lightweight and durable materials like carbon fiber and titanium will continue to drive innovation in bicycle frames.
- Electric bicycle (E-bike) frames are expected to see significant growth as the popularity of e-bikes increases globally.
- Customization and personalization will remain key trends, with consumers seeking tailored frames to suit their riding preferences.
- The integration of smart technology, such as sensors and wireless features, will enhance frame designs for added functionality.
- Environmental sustainability will play a growing role, with more manufacturers using recycled and eco-friendly materials.
- Foldable and compact frames will gain traction in urban markets, offering convenience for commuters.
- Manufacturers will increasingly adopt advanced manufacturing techniques like hydroforming and 3D printing for greater efficiency and innovation.
- Growing government support for cycling infrastructure will positively impact the bicycle frames market.
- Rising disposable income in emerging markets will boost demand for premium and high-performance frames.
- Direct-to-consumer sales models will expand, reducing costs and increasing accessibility for customers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bicycle Frames market?
What factors are driving the growth of the Bicycle Frames market?
What are the key segments within the Bicycle Frames market?
What are some challenges faced by the Bicycle Frames market?
Who are the major players in the Bicycle Frames market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bicycle Frames Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bicycle Frames Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 24,189.5 million → 2032: USD 39,436.01 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bicycle Frames Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bicycle Frames Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bicycle Frames Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bicycle Frames Market Drivers
- 3.3 Bicycle Frames Market Restraints & Challenges
- 3.4 Bicycle Frames Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bicycle Frames Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bicycle Frames Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bicycle Frames category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bicycle Frames Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bicycle Frames Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bicycle Frames market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bicycle Frames Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bicycle Frames Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bicycle Frames Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bicycle Frames (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bicycle Frames Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bicycle Frames Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bicycle Frames Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bicycle Frames Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bicycle Frames Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bicycle Frames Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bicycle Frames Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bicycle Frames Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bicycle Frames Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
