
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Cheese Packaging Market Size 2024 | USD 3,656 Million |
| Cheese Packaging Market, CAGR | 3.90% |
| Cheese Packaging Market Size 2032 | USD 4,965.13 Million |
Market Overview
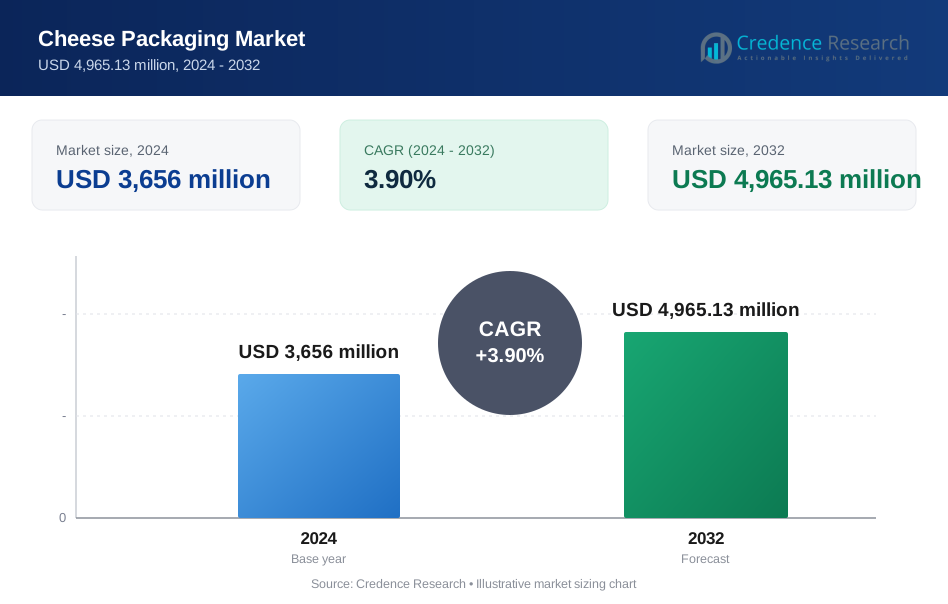
The Cheese Packaging Market is projected to grow from USD 3,656 million in 2024 to USD 4,965.13 million by 2032, exhibiting a compound annual growth rate (CAGR) of 3.90%.
The Cheese Packaging Market is driven by increasing consumer demand for convenient, longer-lasting, and eco-friendly packaging solutions. Key trends include the adoption of advanced packaging technologies that enhance product shelf life and freshness, as well as a shift towards sustainable and recyclable materials to meet environmental regulations. Additionally, the growing popularity of ready-to-eat cheese products and expanding cheese varieties are propelling the need for innovative packaging designs that ensure product safety and quality. These drivers and trends collectively highlight the market's focus on efficiency, sustainability, and consumer convenience.
The cheese packaging market is characterized by significant regional demand, with North America and Europe leading due to their well-established dairy industries and advanced packaging technologies. In North America, key players like Amcor plc and Berry Global Inc. drive innovation, while Europe sees substantial contributions from Constantia Flexibles Group GmbH and Mondi plc. The Asia-Pacific region is emerging as a high-growth area, spurred by increasing cheese consumption and growing economies. Prominent global players such as WINPAK LTD, Sealed Air Corp, and ProAmpac LLC are expanding their reach, meeting diverse packaging needs across various markets.
Market Drivers
Increasing Consumption of Cheese
Cheese consumption is rising globally due to a growing preference for high-protein and high-fat diets. For instance, in 2022, the average consumer in the United States ate about 41.8 pounds of cheese. This trend is particularly evident in developing regions like Asia, where westernized food habits are increasingly influencing local diets. The demand for cheese is also driven by its versatile use in various convenient food products, such as on-the-go snacks, processed meals, and ready-to-eat foods. As consumers seek nutritious and flavorful options, cheese has become a staple in both traditional meals and modern culinary creations, contributing significantly to market growth.
Advancements in Packaging Technology
Advancements in cheese packaging technologies are crucial in enhancing product shelf life, maintaining freshness, and preventing contamination. Innovations such as resealable packages, modified atmosphere packaging, and antimicrobial films are at the forefront of this evolution. These technologies ensure that cheese products remain safe and appealing to consumers by providing extended shelf life and superior quality preservation. The introduction of such advanced packaging solutions addresses the need for both food safety and consumer convenience, setting new standards in the industry.
Rising Demand for Convenience and Aesthetics
Modern consumers increasingly prioritize convenience and aesthetic appeal in their purchasing decisions. For example, 56% of Italian consumers would like a wider range of cheeses to be available in smaller packs. Cheese packaging that is easy to open, resealable, and visually attractive is more likely to capture consumer interest. This shift towards user-friendly and appealing packaging designs aligns with the broader trend of enhancing the overall consumer experience. Packaging that offers practical features, such as easy handling and resealing options, not only adds value to the product but also boosts brand loyalty by meeting the consumers' lifestyle needs.
Growth of the E-commerce Sector
The rising popularity of online grocery shopping is creating a significant demand for robust cheese packaging solutions. By 2034, eCommerce is projected to capture a 26.4% market share in the cheese packaging market. As consumers increasingly rely on e-commerce for their grocery needs, packaging that can withstand transportation and ensure product integrity during delivery becomes essential. The growth of the e-commerce sector necessitates durable and reliable packaging that protects cheese products from damage and contamination during transit. This trend underscores the importance of innovation in packaging materials and design to cater to the logistics challenges posed by online retailing, further driving the cheese packaging market forward.
Market Trends
Shifting Towards Sustainable Packaging
Consumers are becoming increasingly environmentally conscious, and this shift is significantly impacting the cheese packaging market. There's a growing demand for sustainable packaging solutions that are biodegradable, compostable, or made from recycled materials. For instance, in 2019, 87% of cheese packaging around the globe contained plastic. There’s a growing demand for sustainable packaging solutions that are biodegradable, compostable, or made from recycled materials. As awareness about environmental issues rises, both consumers and manufacturers are prioritizing eco-friendly alternatives to traditional packaging. This trend is driving innovations in packaging materials, with companies exploring options like plant-based plastics and recyclable paper products. Brands that adopt sustainable packaging solutions are likely to gain a competitive edge by appealing to the eco-conscious segment of the market and demonstrating their commitment to environmental stewardship.
Functional Packaging with Benefits
Cheese packaging is evolving to offer more than just product protection. Modern packaging solutions are incorporating features that enhance the overall consumer experience. In terms of functional packaging, a study showed that 65% of consumers find easy-to-open mechanisms important, while 60% appreciate resealable closures. Controlled portion sizes are also becoming popular, with 50% of consumers indicating they prefer single-serve options for convenience and portion control. Antimicrobial packaging, which can extend the shelf life of cheese by up to 25%, is gaining traction as well. This type of packaging helps maintain product freshness and safety, which is particularly important for perishable items like cheese. The rise of single-serve packaging is also notable, driven by the growing demand for convenience and portion control. Single-serve options are especially popular for snacking cheeses and cheese used in prepared meals, offering both practicality and reduced food waste. Moreover, there is an increasing focus on transparency and information. Consumers want to know where their food comes from and how it is produced. In response, cheese packaging is incorporating windows or clear materials to showcase the product and provide more information. On-pack labeling that highlights ethical sourcing and sustainable practices is also becoming more common, catering to the informed consumer's desire for transparency and accountability in food production.
Market Challenges Analysis
Balancing Functionality and Sustainability
Creating cheese packaging that successfully balances functionality with sustainability presents a significant challenge. Traditional packaging materials, particularly certain plastics, are highly effective at protecting cheese and maintaining its freshness. However, these materials often pose serious environmental concerns due to their non-biodegradable nature and potential contribution to plastic waste. The industry is increasingly focused on developing sustainable alternatives that can offer comparable protective qualities. Innovations in biodegradable and compostable materials are promising, but they often require ongoing research and development to ensure they can effectively preserve cheese and prevent spoilage. This balancing act demands significant effort from manufacturers to achieve both high performance and environmental responsibility, as they work to find solutions that do not compromise on either front.
Cost Considerations and Regulatory Challenges
Cost considerations and regulatory compliance are significant hurdles in the cheese packaging market. Sustainable packaging materials and advanced functionalities typically come with a higher price tag compared to traditional options. This poses a challenge for cheese manufacturers who must balance the need for high-quality, innovative packaging with the necessity of keeping product prices competitive. Additionally, the packaging must meet stringent food safety regulations and labeling requirements, which can add complexity to the design and production process. Ensuring that packaging is not only compliant but also informative and visually appealing requires careful planning and execution. Furthermore, addressing food waste through packaging solutions that extend shelf life is a persistent issue. Inefficient packaging can lead to cheese spoilage and contribute to unnecessary waste. As such, ongoing efforts are needed to develop packaging that enhances product longevity while minimizing environmental impact and adhering to regulatory standards.
Market Segmentation Analysis:
By Packaging Format:
The cheese packaging market encompasses various formats tailored to meet different consumer needs and product types. Boxes are widely used for both retail and bulk cheese packaging due to their ability to provide ample protection and stackability. Cups and pouches are favored for their convenience and suitability for single-serve portions, catering to the rising demand for on-the-go cheese options. Trays and flow wraps offer versatile solutions for packaging slices and blocks of cheese, ensuring freshness and visual appeal. Containers are employed for a range of cheese products, from grated varieties to soft cheeses, while lids and foils are crucial for sealing and preserving cheese in various formats. Others include innovative packaging solutions that address specific market demands, such as eco-friendly materials or custom shapes. Each format is chosen based on factors like shelf life, convenience, and consumer preference, reflecting the market's adaptation to evolving packaging needs.
By Material:
The cheese packaging market utilizes diverse materials to cater to different packaging requirements and sustainability goals. Plastic remains the most common material due to its versatility and cost-effectiveness. Within this category, Polyethylene Terephthalate (PET), Polypropylene (PP), and Polyethylene (PE) are popular for their durability and barrier properties. Ethylene Vinyl Alcohol (EVOH) and Polyamide are used for their advanced protective features, suitable for premium cheese products. Glass is valued for its recyclability and ability to maintain cheese freshness, though it is less common due to cost and fragility. Paper is gaining traction for its eco-friendly attributes, particularly in sustainable packaging solutions. Aluminum offers excellent barrier properties and is used for products requiring extended shelf life. Others include biodegradable and compostable materials, reflecting the market's shift towards sustainable practices. Each material is selected based on factors like protection, sustainability, and consumer preferences, highlighting the industry's adaptability to various packaging needs.
Segments:
Based on Packaging Format:
- Boxes
- Cups
- Pouches
- Trays
- Flow Wraps
- Containers
- Lids and Foils
- Others
Based on Material:
- Plastic
- Polyethylene Terephthalate (PET)
- Polypropylene (PP)
- Polyethylene (PE)
- Ethylene Vinyl Alcohol (EVOH)
- Polyamide
- Others
- Glass
- Paper
- Aluminum
Based on Distribution Channel:
- E-commerce
- Retail Stores
- Convenience Stores
- Hypermarkets
- Supermarkets
- Others
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Europe
Europe dominates the global cheese packaging market, commanding a substantial 45% market share. This leadership position is primarily driven by the region's rich cheese-making heritage, diverse cheese varieties, and strong consumer demand. Countries like France, Italy, Germany, and the Netherlands contribute significantly to this market dominance, with their centuries-old cheese production traditions and innovative packaging solutions. European cheese manufacturers and packagers have been at the forefront of developing sustainable packaging materials, responding to growing environmental concerns and stringent regulations. The region's market is characterized by a high level of sophistication in packaging design, focusing on extended shelf life, improved barrier properties, and enhanced visual appeal. Additionally, Europe's cheese packaging sector benefits from advanced technologies such as modified atmosphere packaging (MAP) and intelligent packaging systems, which ensure product freshness and quality. The increasing trend towards convenience and on-the-go consumption has also spurred innovations in portion-sized and resealable packaging formats, further solidifying Europe's position in the global cheese packaging market.
North America
North America holds the second-largest share in the cheese packaging market at 30%, with the United States being the primary contributor. The region's market is driven by a growing consumer preference for natural and artisanal cheeses, coupled with an increasing demand for convenient and portable cheese products. North American cheese packagers have been quick to adopt flexible packaging solutions, which offer benefits such as improved product protection, extended shelf life, and reduced environmental impact. The market has seen a significant shift towards eco-friendly packaging materials, including recyclable plastics and bioplastics, in response to consumer demand for sustainable options. Moreover, the rise of e-commerce and direct-to-consumer cheese sales has led to innovations in packaging designed to withstand the rigors of shipping while maintaining product integrity. The North American cheese packaging market also benefits from a robust dairy industry and continuous investments in packaging technology, including advancements in barrier films and active packaging solutions. As consumers increasingly seek premium and specialty cheeses, the demand for high-quality, visually appealing packaging continues to drive growth and innovation in the North American market.
Key Player Analysis
- Amcor plc
- Adapa Group
- WINPAK LTD
- Constantia Flexibles Group Gmbh
- Berry Global Inc
- Mondi plc
- Sonoco Products Company
- Schur Flexibles Holding GesmbH
- Sealed Air Corp
- Stora Enso Oyj
- ProAmpac LLC
- Kendall Packaging Corporation
- SKOPOS SA
- Lactalis International
- Fonterra Co-operative Group
- Royal Friesland Campina N.V.
- Arla Foods
- SAVENCIA SA
- BEL SA
- Britannia Industries
- Saputo Inc
- Portco Packaging Corporation
- Swiss Pac Pvt Ltd
- Flexipol
Competitive Analysis
The cheese packaging market is highly competitive, with leading players leveraging innovation and diverse product offerings to gain market share. Amcor plc stands out with its advanced, sustainable packaging solutions, focusing on reducing environmental impact while enhancing product shelf life. Berry Global Inc. emphasizes the development of flexible, high-performance materials, catering to a broad range of packaging needs. WINPAK LTD and Sealed Air Corp are renowned for their innovative designs and technologies that improve product protection and convenience. Constantia Flexibles Group GmbH and Mondi plc drive market growth with eco-friendly materials and enhanced functionality. ProAmpac LLC excels in providing versatile and cost-effective packaging solutions. Other notable players, including Schur Flexibles Holding GesmbH and Stora Enso Oyj, focus on integrating smart technologies and sustainable practices. These companies continuously invest in R&D to maintain a competitive edge, addressing evolving consumer preferences and regulatory requirements in the cheese packaging sector.
Recent Developments
- In April 2024, Amcor announced the expansion of its printing and converting capabilities in North America for the dairy market to support customer needs for flexible packaging.
- In April 2023, Stora Enso Oyj introduced Trayforma BarrPeel, which is a sustainable barrier-coated paperboard material for pressed trays for fresh food like cheese. They also reduce the 10% plastic in the trays.
- In November 2023, Mondi plc announced the collaboration with Skånemejerier to develop cheese packaging. The company created a mono-material polypropylene-based packaging for ICA’s Hushållsost cheese.
- In February 1, 2022, Ornua Foods declared that they was switching its Pilgrims Choice grated cheese into a fully-recyclable and environmentally sustainable packaging, which would contribute to a 15% savings of materials and 48% reduction in carbon footprint.
- In December 16, 2021, Coveris, a sustainable packaging manufacturer, introduced a range of lightweight, fully-recyclable pouches for Tesco’s grated cheese and Ornua Foods. New packaging, MonoFlexBE format is a direct replacement for hard-to-recycle plastics and meets current shelf-life requirements. New packaging also offers a significant plastic weight reduction of 680mg of plastic per bag, in turn, contributing to the reduction in carbon footprint.
Market Concentration & Characteristics
The cheese packaging market exhibits moderate to high concentration, characterized by the dominance of several key players who lead in innovation and technology. Major companies such as Amcor plc, Berry Global Inc., and Constantia Flexibles Group GmbH significantly influence market dynamics with their advanced, sustainable packaging solutions. This concentration is driven by the need for high-quality, efficient packaging that meets evolving consumer demands and stringent regulatory standards. The market is marked by continuous innovation, with companies investing heavily in R&D to develop packaging that enhances product freshness, extends shelf life, and offers convenience. Additionally, the focus on sustainability is shaping market characteristics, as manufacturers increasingly prioritize eco-friendly materials and practices. Strategic mergers and acquisitions further intensify competition, as companies seek to expand their market presence and capabilities. Overall, the cheese packaging market is defined by a balance between technological advancement and the drive for environmental responsibility.
Report Coverage
The research report offers an in-depth analysis based on Packaging Format, Material, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The cheese packaging market is anticipated to grow steadily due to increasing consumer demand for diverse cheese products.
- Advances in packaging technology will focus on enhancing shelf life and maintaining product freshness.
- There will be a continued shift towards sustainable and eco-friendly packaging materials to meet environmental regulations.
- The adoption of smart packaging solutions with tracking and monitoring capabilities will rise.
- Single-serve and portion-controlled packaging formats will become more popular due to consumer convenience trends.
- Innovations in resealable and easy-to-open packaging will cater to growing demands for user-friendly solutions.
- E-commerce growth will drive the development of packaging that ensures product integrity during transport.
- Regional expansions and investments by key players will enhance market presence in emerging economies.
- There will be increased focus on packaging designs that offer both functionality and aesthetic appeal.
- Collaboration between packaging manufacturers and food producers will lead to more tailored and efficient packaging solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Consumption of Cheese
Global cheese consumption is rising due to changing dietary preferences, especially in developing regions adopting Western food habits. This drives demand for packaging solutions that can accommodate a wider variety of cheese products and formats.
Advancements in Packaging Technology
Innovations such as resealable packages, modified atmosphere packaging, and antimicrobial films are extending shelf life and maintaining product quality, making cheese products safer and more appealing to consumers.
Demand for Convenience and Aesthetics
Consumers increasingly seek cheese packaging that is easy to open, resealable, and visually attractive, which enhances user experience and supports the trend toward on-the-go and portion-controlled cheese products.
Growth of E-commerce Sector
The expansion of online grocery shopping requires robust packaging that can protect cheese during transit, leading to increased demand for durable, tamper-evident, and transport-friendly packaging solutions.
Shift Towards Sustainable Packaging
Rising environmental awareness and regulatory pressures are pushing manufacturers to adopt biodegradable, compostable, and recyclable materials, driving innovation in eco-friendly cheese packaging.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cheese Packaging Market?
What factors are driving the growth of the Cheese Packaging Market?
What are the key segments within the Cheese Packaging Market?
What are some challenges faced by the Cheese Packaging Market?
Who are the major players in the Cheese Packaging Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Plastic
- 1.2.2 Glass
- 1.2.3 Paper
- 1.2.4 Aluminum
- 1.2.5 Others
- 1.3 By Packaging Format
- 1.3.1 Boxes
- 1.3.2 Cups
- 1.3.3 Pouches
- 1.3.4 Trays
- 1.3.5 Flow Wraps
- 1.3.6 Containers
- 1.3.7 Lids and Foils
- 1.3.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,656 million → 2032: USD 4,965.13 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cheese Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cheese Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cheese Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cheese Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cheese Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cheese Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cheese Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cheese Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,656 million → 2032: USD 4,965.13 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cheese Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Plastic
- 12.3.7.2 Glass
- 12.3.7.3 Paper
- 12.3.7.4 Aluminum
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Packaging Format - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Boxes
- 12.4.7.2 Cups
- 12.4.7.3 Pouches
- 12.4.7.4 Trays
- 12.4.7.5 Flow Wraps
- 12.4.7.6 Containers
- 12.4.7.7 Lids and Foils
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cheese Packaging Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cheese Packaging Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cheese Packaging Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Amcor plc
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Berry Global Inc.
- 17.4 Constantia Flexibles Group GmbH
- 17.5 Mondi plc
- 17.6 WINPAK LTD
- 17.7 Sealed Air Corp
- 17.8 ProAmpac LLC
- 17.9 Stora Enso Oyj
- 17.10 Sonoco Products Company
- 17.11 Schur Flexibles Holding GesmbH
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

