
Market Overview
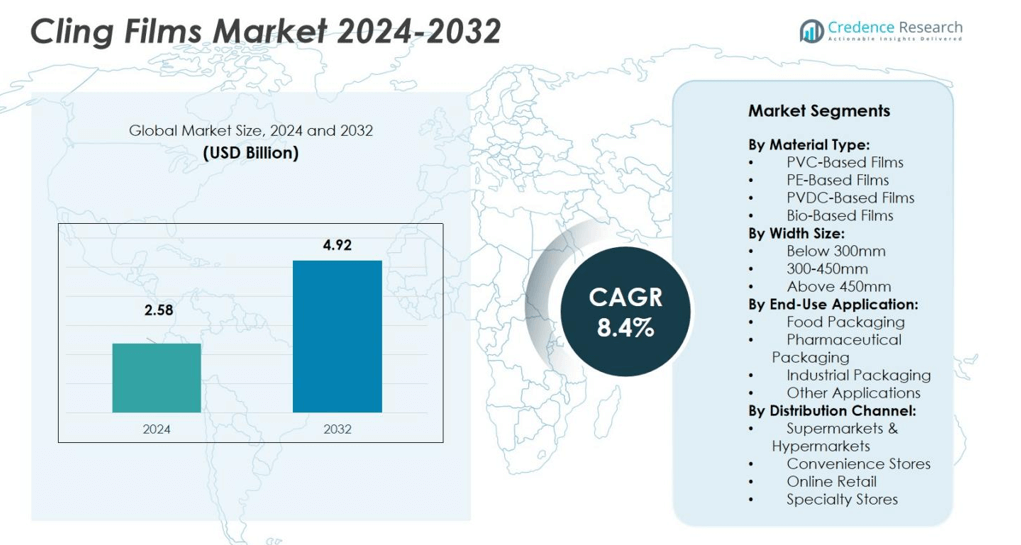
Cling Films Market size was valued USD 2.58 Billion in 2024 and is anticipated to reach USD 4.92 Billion by 2032, at a CAGR of 8.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cling Films Market Size 2024 | USD 2.58 Billion |
| Cling Films Market, CAGR | 8.4% |
| Cling Films Market Size 2032 | USD 4.92 Billion |
The Cling Films Market is led by prominent players such as Amcor plc, Berry Global Inc., Sealed Air, Reynolds Consumer Products, Mitsubishi Chemical Group Corporation, Sigma Plastics Group, Anchor Packaging LLC, POLIFILM, IPG, and Greendot Biopak. These companies focus on innovation in recyclable and bio-based cling films to meet evolving environmental standards and consumer demand for sustainable packaging. Strategic collaborations, technological advancements in film extrusion, and product diversification strengthen their global presence. North America holds the leading regional position with a 34% market share in 2024, driven by robust retail and food packaging sectors, while Asia Pacific, with a 29% share, emerges as the fastest-growing region due to expanding food delivery networks and rising urbanization.
Market Insights
- The Cling Films Market was valued at USD 2.58 Billion in 2024 and is projected to reach USD 4.92 Billion by 2032, growing at a CAGR of 8.4% during the forecast period.
- Rising demand for fresh and hygienic food packaging drives market expansion, with the food packaging segment holding 63% share in 2024. Increasing use of cling films in supermarkets and e-commerce enhances convenience and shelf life.
- Sustainability trends encourage the adoption of bio-based and recyclable films, replacing conventional PVC-based options and aligning with global environmental regulations.
- Leading players such as Amcor plc, Berry Global Inc., Sealed Air, and Reynolds Consumer Products focus on innovation and strategic partnerships to strengthen market competitiveness.
- North America leads the global market with a 34% share, followed by Europe at 28% and Asia Pacific at 29%, which remains the fastest-growing region due to rapid urbanization and food delivery growth.
Market Segmentation Analysis:
By Material Type
PVC-based films dominate the Cling Films Market with a 46% share in 2024, owing to their strong stretchability, clarity, and superior cling properties. These films are widely used in food and industrial packaging due to cost-effectiveness and ease of processing. PE-based films hold a growing portion supported by demand for non-toxic and recyclable materials. PVDC-based variants find niche use in barrier packaging applications requiring moisture and gas resistance. Bio-based films expand rapidly as brands adopt sustainable and compostable alternatives aligned with eco-friendly regulations.
- For instance, Chyi Yang has integrated advanced adhesive syringe technology into its PE film production lines, which has enabled significantly improved flow rate control and cost reductions across over 60 years of refining production processes, resulting in sustainable PE cling film output scaling into the thousands of tons yearly.
By Width Size
The 300–450mm width segment leads the market with a 52% share in 2024, favored across retail, catering, and household packaging applications. This width provides the ideal balance between coverage area and ease of handling for standard food trays and storage wraps. Below 300mm films maintain demand in small food portions and pharmaceutical packs. Above 450mm variants cater to industrial packaging, particularly pallet wrapping and bulk food processing. Manufacturers focus on versatile roll sizes to meet diverse consumer and commercial requirements.
- For instance, CrystalWrap’s CW Catering Film is available in the 450mm width and 300m roll length, widely used in commercial food service packaging due to its high clarity and durability suitable for wrapping fresh and prepared food items.
By End-Use Application
Food packaging dominates the Cling Films Market, accounting for a 63% share in 2024, driven by rising demand for fresh produce, meat, and ready-to-eat meals. Cling films extend shelf life, prevent contamination, and improve product presentation in supermarkets and foodservice outlets. Pharmaceutical packaging utilizes films for product protection and sterile wrapping, while industrial applications include bundling and protective covering. The growing focus on hygienic food handling and increasing urban consumption trends continue to reinforce the dominance of food packaging applications globally.
Key Growth Drivers
Rising Demand for Fresh and Convenient Food Packaging
The growing consumption of fresh produce, ready-to-eat meals, and bakery items drives strong demand for cling films. Consumers prefer lightweight, transparent, and stretchable wraps that preserve freshness and prevent contamination. Retailers increasingly use these films for improved product visibility and hygiene. Expanding supermarket and e-commerce food delivery networks further accelerate usage. The trend toward smaller portion packaging in urban households continues to strengthen the adoption of cling films across food applications worldwide.
- For instance, Sealed Air developed the CRYOVAC Brand rBDF S10 film, which features a thickness of 21 microns, making it one third lighter and three times thinner than widely used conventional films.
Shift Toward Sustainable and Recyclable Materials
Sustainability initiatives across packaging industries are a major growth catalyst for bio-based and recyclable cling films. Manufacturers invest in developing polyethylene and polylactic acid (PLA) films that meet performance standards while reducing plastic waste. Government regulations promoting eco-friendly packaging encourage the transition from PVC-based products. Major brands introduce compostable film ranges to meet retailer sustainability targets. The increasing consumer preference for environmentally responsible products is reshaping material innovation in the cling film market.
- For instance, KMA Packaging's C-Range includes home-compostable cling films engineered for strength and clarity, which comply with European standards and are now trusted by fresh produce companies and supermarkets across Europe.
Expanding Applications in Industrial and Pharmaceutical Sectors
Beyond food packaging, cling films find growing adoption in industrial bundling, protective wrapping, and pharmaceutical packaging. Their ability to safeguard products against moisture, dust, and tampering enhances appeal across logistics and manufacturing. Pharmaceutical firms use high-clarity films for secure, sterile wrapping of medical devices and supplies. The rise in export-oriented packaging and temperature-sensitive goods boosts demand for high-performance films with barrier and anti-static features, broadening market reach across end-user industries.
Key Trends & Opportunities
Advancements in Film Technology and Manufacturing Efficiency
Ongoing innovation in film extrusion and polymer processing enhances film performance, clarity, and recyclability. Multi-layered films with superior cling and puncture resistance are gaining traction across both household and industrial applications. Automated film winding and cutting technologies improve consistency and reduce waste during production. These technological upgrades enable manufacturers to meet evolving performance demands while improving operational efficiency and profit margins.
- For instance, Dow Chemical's multi-layer stretch films exhibit superior transverse directional tear resistance of up to 700 g/mil, enhancing puncture resistance for durable packaging.
Rising Adoption of Smart and Antimicrobial Films
Manufacturers increasingly explore smart cling films with antimicrobial and self-healing properties for safer food preservation. These films extend shelf life by reducing bacterial growth and spoilage. The growing interest in smart packaging solutions aligns with health and safety concerns among consumers. Integration of additives that enhance UV protection and odor control also creates new commercial opportunities for premium food packaging applications in global retail markets.
- For instance, chitosan-based films with natural antimicrobial properties have been effectively used to preserve fresh food and extend shelf life, demonstrating strong inhibition against foodborne pathogens like E. coli and S. aureus.
Key Challenges
Environmental and Regulatory Pressure on Plastic Use
Strict government regulations on single-use plastics present a major challenge for cling film producers. PVC-based films face increasing scrutiny due to non-biodegradable characteristics and recycling difficulty. Manufacturers must invest in developing recyclable or bio-based alternatives that comply with packaging waste directives. Meeting these evolving standards raises production costs and affects profit margins, especially for small-scale producers competing with global players.
Volatility in Raw Material Prices
Fluctuating prices of petrochemical-based raw materials such as polyethylene and PVC resins create uncertainty in production costs. Global supply chain disruptions and energy price volatility further impact material availability. These variations affect manufacturers’ pricing strategies and profit stability. Companies are increasingly turning to localized sourcing, material substitution, and long-term supplier contracts to minimize the effects of raw material price instability in the cling film industry.
Regional Analysis
North America
North America dominates the Cling Films Market, capturing a 34% share in 2024, driven by strong demand from the food packaging and retail sectors. The U.S. leads the region, supported by widespread adoption of high-quality, food-grade PVC and PE films in supermarkets and catering services. The presence of major players like Berry Global and Reynolds Consumer Products accelerates innovation in recyclable packaging. Regulatory emphasis on sustainability further promotes bio-based film development, while high disposable income and a growing meal-kit industry continue to support steady market growth.
Europe
Europe holds a 28% market share in 2024, led by Germany, the U.K., and France. The region’s growth is fueled by stringent environmental regulations favoring recyclable and compostable films. European manufacturers invest heavily in R&D to replace conventional PVC with eco-friendly materials such as PLA and PE. Rising consumer awareness of food hygiene and waste reduction drives cling film usage in households and retail packaging. The expansion of organized retail and strong sustainability commitments among EU nations further strengthen Europe’s market position.
Asia Pacific
Asia Pacific accounts for a 29% share in 2024, emerging as the fastest-growing region in the cling films industry. Rising urbanization, expanding retail infrastructure, and the booming food delivery sector in China, India, and Japan drive consumption. Local producers rapidly adopt cost-effective manufacturing and bio-based innovations to meet surging regional demand. Increasing middle-class income and preference for hygienic food packaging contribute to high-volume sales. Government initiatives promoting sustainable packaging further enhance market opportunities across developing economies in the region.
Latin America
Latin America holds a 6% market share in 2024, with Brazil and Mexico leading the demand. The market benefits from increasing adoption of packaged and ready-to-eat food products. Growing supermarket chains and food processing industries stimulate the use of cling films for food preservation and display. Manufacturers focus on low-cost PE and recyclable film production to serve domestic markets. However, limited recycling infrastructure and price sensitivity among consumers moderate growth potential across the region.
Middle East & Africa
The Middle East & Africa region captures a 3% share in 2024, driven by expanding retail formats and rising consumption of packaged food. The GCC countries show higher adoption rates supported by increasing disposable income and urban lifestyle trends. Demand for industrial-grade cling films also grows with regional trade and logistics development. However, dependence on imports for raw materials and limited local manufacturing capabilities pose challenges. Gradual expansion of foodservice chains and modern retail outlets continues to support steady growth in this region.
Market Segmentations:
By Material Type:
- PVC-Based Films
- PE-Based Films
- PVDC-Based Films
- Bio-Based Films
By Width Size:
- Below 300mm
- 300-450mm
- Above 450mm
By End-Use Application:
- Food Packaging
- Pharmaceutical Packaging
- Industrial Packaging
- Other Applications
By Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores
- Online Retail
- Specialty Stores
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Cling Films Market features major players such as Amcor plc, Berry Global Inc., Sealed Air, Reynolds Consumer Products, Mitsubishi Chemical Group Corporation, Sigma Plastics Group, Anchor Packaging LLC, POLIFILM, IPG, and Greendot Biopak. These companies compete through product innovation, sustainability initiatives, and global distribution expansion. Leading firms focus on developing recyclable, bio-based, and compostable cling films to meet growing environmental regulations and consumer preferences. Strategic partnerships with food and retail brands enhance visibility and market penetration. Technological advancements in multi-layer extrusion and improved film clarity further strengthen competitive advantage. Regional players emphasize cost-effective production and customized film solutions to serve niche markets. Continuous R&D investments in high-performance and eco-friendly materials define the evolving market dynamics, with sustainability and packaging efficiency becoming the key differentiators among top competitors.
Key Player Analysis
- Amcor plc
- Reynolds Consumer Products
- POLIFILM
- Berry Global Inc.
- Greendot Biopak
- Sealed Air
- Anchor Packaging LLC
- Sigma Plastics Group
- Mitsubishi Chemical Group Corporation
- IPG
Recent Developments
- In Nov 2025, NatureWorks and Sukano unveiled compostable BOPLA films at K 2025. The launch targets high-performance, mono-material packaging on existing BOPP lines. The duo emphasized printability and optical gains.
- In Sept 2025, Amcor highlighted Omni® Xtra+ recycle-ready PE cling film at Fachpack. The film is a PVC alternative with anti-fog and high clarity. Amcor positioned it for fresh-food wrap.
- In Feb 2025, Berry Global launched Bontite Sustane stretch film with 30% PCR. The film targets pallet wrap and retail distribution. It advances recycled-content films in food logistics.
- In Aug 2025, Cortec introduced Eco Works 100 compostable packaging film. The film is 100% biobased and industrially compostable. It suits wrap applications replacing petroleum films
Report Coverage
The research report offers an in-depth analysis based on Material Type, Width Size, End Use Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for bio-based and recyclable cling films will rise due to sustainability regulations.
- Food packaging will continue to dominate, driven by growing consumption of ready-to-eat meals.
- Technological advancements will enhance film strength, clarity, and biodegradability.
- Asia Pacific will remain the fastest-growing region supported by urbanization and retail expansion.
- Manufacturers will invest in multilayer extrusion and advanced polymer technologies.
- Partnerships with foodservice and retail brands will strengthen global market presence.
- Smart and antimicrobial cling films will gain traction for improved food safety.
- Price fluctuations of petrochemical raw materials will influence production strategies.
- Online retail and e-commerce packaging applications will expand rapidly.
- Industry focus will shift toward circular economy practices and sustainable packaging solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Cling Films Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cling Films Market projected to grow between 2025 and 2032?
Which Cling Films Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cling Films Market?
Who are the leading companies in the Cling Films Market?
Which region commanded the largest share of the Cling Films Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.58 Billion → 2032: USD 4.92 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cling Films Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cling Films Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cling Films Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cling Films Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cling Films Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cling Films Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cling Films Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cling Films Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.58 Billion → 2032: USD 4.92 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cling Films Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cling Films Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cling Films Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cling Films Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
