
Companion Animal Pharmaceutical Market Overview:
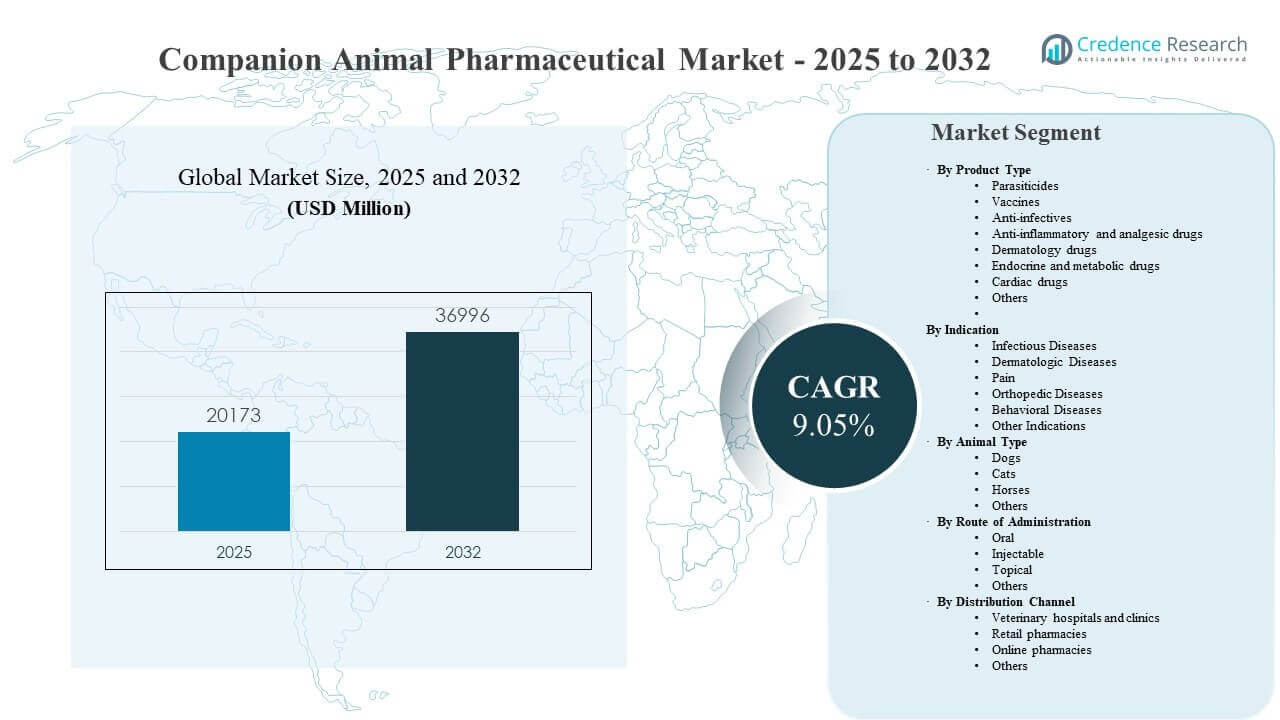
The global Companion Animal Pharmaceutical Market size was estimated at USD 20173 million in 2025 and is expected to reach USD 36996 million by 2032, growing at a CAGR of 9.05% from 2025 to 2032. Growth is primarily driven by sustained expansion in preventive care and chronic therapy demand as companion animals receive more frequent veterinary visits and longer-duration treatment plans. Rising standards of care in clinics and hospital networks are improving diagnosis rates and supporting earlier intervention across parasitic, dermatologic, pain, and metabolic conditions. Demand growth is also reinforced by expanding pharmaceutical portfolios, stronger commercialization of novel therapeutics, and wider access to veterinary services in emerging urban markets.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Companion Animal Pharmaceutical Market Size 2025 | USD 20173 million |
| Companion Animal Pharmaceutical Market, CAGR | 9.05% |
| Companion Animal Pharmaceutical Market Size 2032 | USD 36996 million |
Key Market Trends & Insights
- The Companion Animal Pharmaceutical Market is expanding at 9.05% CAGR during 2025–2032, supported by increasing therapy intensity per treated animal.
- The Companion Animal Pharmaceutical Market is projected to reach USD 36996 million by 2032, reflecting broad-based growth across preventive and therapeutic categories.
- North America accounted for 33.60% of 2025 revenue, supported by strong veterinary infrastructure and higher prescription adherence in clinic-led pathways.
- Veterinary hospitals and clinics represented 56.30% share in 2025, reflecting the role of diagnosis and point-of-care dispensing in treatment initiation.
- Parasiticides held a 27.40% share in 2025, driven by recurring ectoparasite and endoparasite prevention across canine and feline populations.
Segment Analysis
Companion animal pharmaceuticals demand is shaped by the shift toward preventive care, earlier diagnosis, and longer treatment duration for chronic conditions. Owners increasingly prioritize clinical follow-ups, which supports prescription renewals and structured care pathways for dermatology, pain management, and metabolic disorders. Product selection often favors convenience, safety, and dosing compliance, supporting stronger adoption of palatable oral formats and long-acting options where clinically appropriate. Purchasing decisions also reflect trust in veterinary recommendations, which reinforces the dominance of clinic-based distribution.
Buyer behavior is increasingly influenced by treatment outcomes, ease of administration, and the perceived value of comprehensive protection. Preventives and chronic therapies benefit from repeat purchasing cycles, which improves category resilience even when discretionary spending moderates. Digital engagement is supporting refill reminders and higher continuity of care, particularly where online channels integrate with veterinary prescriptions. Therapeutic innovation and label expansions are strengthening category depth and supporting premiumization in high-frequency conditions.
By Product Type Insights
Parasiticides accounted for the largest share of 27.40% in 2025. High recurrence of flea, tick, and internal parasite exposure supports consistent year-round prophylaxis across dogs and cats. Convenient dosing formats, including chewables and topical solutions, improve compliance and reinforce repeat purchasing patterns. Combination claims and broader coverage profiles support switching toward premium branded solutions, particularly in regions with higher preventive-care adherence.
By Indication Insights
Infectious Diseases accounted for the largest share of 33.90% in 2025. Routine veterinary protocols sustain steady utilization through vaccination schedules and clinic-driven treatment pathways. Strong awareness of transmissible risks supports earlier visits and higher prescription uptake for companion animals showing symptoms. Clinical oversight and antimicrobial stewardship shape product choice and treatment duration, reinforcing the importance of veterinarian-led decision-making.
By Animal Type Insights
Dogs accounted for the largest share of 42.80% in 2025. Higher diagnosis volumes in dogs across parasitic prevention, dermatology, and pain management translate into greater prescription throughput. Owner willingness to pay tends to be higher for canine therapies due to perceived quality-of-life benefits and stronger engagement in preventive routines. Wider availability of dog-specific dosing and product formats supports faster adoption and stronger category penetration.
By Route of Administration Insights
Oral accounted for the largest share of 46.10% in 2025. Oral therapies benefit from at-home administration convenience, which improves compliance for monthly preventives and longer-duration chronic regimens. Palatable formulations reduce administration friction and support persistence, especially for multi-dose schedules. Oral formats also integrate well with clinic counseling and refill routines, reinforcing continuity of care and repeat purchasing.
By Distribution Channel Insights
Veterinary hospitals and clinics accounted for the largest share of 56.30% in 2025. Clinics remain the primary decision point for diagnosis, prescription selection, and therapy initiation, which concentrates dispensing volumes. In-clinic availability supports immediate treatment start and improves follow-up adherence through scheduled checkups and re-evaluation. Online pharmacies continue to expand as fulfillment and home delivery models improve, but prescriptions and clinical oversight keep clinics central to channel share.
Companion Animal Pharmaceutical Market Drivers
Rising preventive-care adoption and adherence
Preventive care protocols are expanding as owners increasingly prioritize year-round protection against parasites and infectious threats. Veterinary practices reinforce preventive routines through standard wellness visits, vaccination schedules, and recurring prophylaxis reminders. Convenience-led product formats improve compliance, which strengthens repeat purchasing and longer customer lifecycles. Broader availability of combination solutions supports uptake by reducing the number of separate treatments required. This driver supports stable baseline demand even in mixed economic conditions.
- For instance, Merck Animal Health’s BRAVECTO Chews provide 12-week flea and tick protection in a single dose, start killing fleas within 2 hours, and reach 88% efficacy within 4 hours and 100% efficacy within 12 hours after treatment, which directly supports adherence through less frequent re-dosing.
Growth in chronic-condition diagnosis and long-duration therapy
Companion animals are living longer, which increases diagnosis rates for chronic dermatologic, pain-related, orthopedic, and metabolic conditions. Veterinary clinics are improving case identification through better diagnostics and structured follow-up care plans. Longer treatment duration increases prescription volume per patient and supports category expansion beyond episodic care. Owner expectations around comfort and quality of life are strengthening willingness to maintain maintenance therapies. This dynamic supports sustained growth in specialty and long-term pharmaceutical categories.
Expansion of veterinary service networks and clinical capacity
Growth in veterinary hospitals, clinic groups, and service networks increases access to professional diagnosis and prescription therapies. Consolidated networks standardize care pathways, which improves therapy initiation and adherence through repeat visits. Better clinical capacity also supports faster uptake of newer therapies, especially in dermatology and pain management. Practice education and client engagement tools strengthen follow-up compliance, reinforcing prescription continuity. This driver also improves distribution efficiency and product availability across regions.
- For instance, Mars Veterinary Health says its Veterinary Health division supports care delivery through about 3,000 veterinary clinics worldwide and roughly 70,000 veterinary professionals, giving large networks the operating scale to standardize follow-up and prescription continuity across regions.
Innovation, portfolio expansion, and brand-led premiumization
Pharmaceutical innovation and portfolio expansion are broadening therapy options and improving differentiation across preventive and specialty categories. Label extensions and improved safety profiles support greater veterinarian confidence and higher adoption in routine practice. Premiumization is strengthened by owner focus on efficacy, convenience, and minimized adverse effects. Companies are also improving patient experience with palatable formulations and simplified dosing. These factors raise value per treated animal and support sustained revenue growth.
Companion Animal Pharmaceutical Market Challenges
Pricing sensitivity remains a constraint in markets where out-of-pocket payment dominates and pet insurance penetration is limited. Even when demand is clinically supported, cost considerations can drive switching to generics, shorter therapy duration, or delayed treatment initiation. Veterinary practices also face capacity constraints in some areas, which can lengthen appointment wait times and reduce follow-up rates. Supply continuity and cold-chain needs for select products can add operational friction. These factors can moderate growth in value-added therapies.
Regulatory complexity and tightening antimicrobial stewardship can slow adoption for certain anti-infective classes and raise the burden of evidence for label expansion. Differences in country-level approval processes and pharmacovigilance requirements add time and cost to commercialization. Counterfeit risks and inconsistent online pharmacy quality controls can erode trust and complicate channel strategy. In addition, owner compliance can decline when administration is challenging or adverse effects are perceived. These barriers require stronger education and monitoring across the treatment journey.
- For instance, Elanco’s Osurnia ear gel, formulated with florfenicol 10 mg/mL, terbinafine 10 mg/mL, and betamethasone acetate 1.0 mg/mL, was evaluated in 284 dogs and achieved a 64.78% treatment success rate versus 43.42% for placebo with just two doses given one week apart, illustrating both the high evidence threshold around antimicrobial-containing therapies and the importance of simplified dosing to improve compliance.
Companion Animal Pharmaceutical Market Trends and Opportunities
Demand is shifting toward more integrated preventive solutions that reduce administration burden and improve continuity of care. Combination therapies and broader coverage claims are strengthening value propositions, particularly in high-frequency parasitic prevention. Digital engagement tools, including reminders and refill workflows, are improving adherence and supporting more predictable revenue streams. Increasing clinic standardization across multi-site networks is also improving protocol-driven prescribing. These trends collectively support higher repeat purchasing and improved treatment persistence.
- For instance, Zoetis states that Simparica Trio is the first monthly chew to protect against heartworm disease, 6 tick species, fleas, and intestinal worms, with studies showing 100% heartworm protection after 1 dose, flea killing beginning within 4 hours, and 100% flea effectiveness in 8 hours; in parallel, Covetrus reported that Stones Corner Veterinary Surgery saved around 5 hours per week and $300 per month after automating reminders through Covetrus Ascend.
Opportunities are expanding in emerging urban markets where veterinary infrastructure is scaling and pet ownership is rising. Growth in teleconsultation models can widen access to prescription pathways when combined with reliable fulfillment and compliance support. Specialty areas such as dermatology, pain, and endocrine management offer attractive expansion potential as diagnosis rates improve and owners accept longer therapy duration. Partnerships with clinic networks can strengthen adoption through education and protocol integration. Product innovation that simplifies dosing and improves tolerability can accelerate conversion from legacy regimens.
Regional Insights
North America
Companion Animal Pharmaceutical Market performance in North America is supported by well-developed veterinary hospital networks, high diagnostic intensity, and strong adherence to preventive and chronic therapies. The region accounted for 33.60% share in 2025, reflecting higher per-pet pharmaceutical spend and clinic-led prescribing pathways. Parasiticide adoption remains high due to established preventive routines, while dermatology and pain management drive growth in specialty prescriptions. Channel strength is reinforced by point-of-care dispensing and structured follow-up programs in clinic groups.
Europe
Companion Animal Pharmaceutical Market demand in Europe is supported by a large pet base, mature veterinary care, and consistent preventive health behavior across key markets. Europe represented 25.30% share in 2025, supported by strong clinician oversight and steady utilization across vaccines, parasiticides, and chronic-condition therapies. Procurement and prescribing often emphasize safety, evidence, and cost control, which can shape brand switching and therapy selection. Clinic-based channels remain central, supported by routine wellness pathways and high owner engagement in animal health.
Asia Pacific
Companion Animal Pharmaceutical Market growth in Asia Pacific is supported by accelerating pet humanization, rising discretionary spend in urban centers, and expanding veterinary infrastructure. Asia Pacific accounted for 23.80% share in 2025, reflecting large population scale and improving access to veterinary services. Demand is rising across preventives, dermatology therapies, and pain management as diagnosis improves and owner awareness increases. Distribution modernization and stronger private clinic networks are improving therapy initiation and adherence, supporting higher category penetration over time.
Latin America
Companion Animal Pharmaceutical Market momentum in Latin America is supported by rising pet ownership and the expansion of private veterinary clinics in major cities. Latin America represented 8.90% share in 2025, with demand centered on core preventives, anti-infectives, and analgesics. Affordability considerations influence product mix and can increase reliance on value brands and generics in certain markets. As clinic networks expand and preventive-care awareness improves, repeat purchasing cycles are strengthening, supporting gradual category premiumization.
Middle East & Africa
Companion Animal Pharmaceutical Market growth in the Middle East & Africa is supported by expanding companion animal ownership in select higher-income markets and increasing access to veterinary services in major urban areas. The region held 8.40% share in 2025, reflecting a smaller installed base and uneven distribution depth across countries. Demand is strongest in parasitic prevention and essential therapies, while specialty categories grow where veterinary capacity and owner spending are increasing. Development of modern clinic formats and reliable supply chains can improve penetration and continuity of care.
Competitive Landscape
Competition in the Companion Animal Pharmaceutical Market is shaped by broad portfolios across parasiticides, vaccines, anti-infectives, and specialty therapies, supported by strong commercialization through veterinary channels. Leading companies compete through innovation, label expansions, palatability and dosing convenience, and sustained clinic engagement via education and protocol integration. Differentiation is strengthened by evidence generation, pharmacovigilance strength, and access to multi-site veterinary networks that improve adoption speed. Channel strategy and distribution coverage remain critical as online fulfillment expands alongside clinic dispensing.
Zoetis maintains a strong competitive position through a diversified companion animal portfolio and deep engagement with veterinary hospitals and clinics, which supports consistent prescribing and refill continuity. The company’s strategy typically emphasizes product lifecycle management, expanded indications, and clinic-driven education that strengthens protocol-based utilization. Portfolio breadth helps address both preventive and chronic-care needs, improving share retention across high-frequency categories. Investment in commercial execution and veterinary partnerships supports adoption of differentiated therapies where outcomes, safety, and convenience drive switching.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Zoetis
- Merck Animal Health
- Elanco Animal Health
- Boehringer Ingelheim Animal Health
- Virbac
- Dechra Pharmaceuticals
- Vetoquinol
- Ceva Santé Animale
- Norbrook
- Bimeda
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In February 2026, MSD Animal Health announced that the U.S. FDA approved NUMELVI for dogs, a treatment for pruritus associated with allergic dermatitis, and said the product is expected to reach veterinary clinics and hospitals across the U.S. in spring 2026.
- In September 2025, MSD Animal Health announced the European launch of NUMELVI, describing it as the first and only second-generation JAK inhibitor approved for the treatment of pruritus associated with allergic dermatitis in dogs after European Commission approval on July 24, 2025.
- In January 2025, Ceva Animal Health entered into a long-term collaboration with Touchlight to develop and manufacture new dbDNA vaccines and therapeutics across a broad range of animal health indications, expanding Ceva’s technology access in animal health.
- In September 2024, Elanco Animal Health announced the FDA approval and U.S. launch of Zenrelia for dogs, a once-daily oral JAK inhibitor indicated for control of pruritus associated with allergic dermatitis and atopic dermatitis in dogs at least 12 months of age.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 20173 million |
| Revenue forecast in 2032 | USD 36996 million |
| Growth rate (CAGR) | 9.05% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Product Type; By Indication; By Animal Type; By Route of Administration; By Distribution Channel |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Zoetis; Merck Animal Health; Elanco Animal Health; Boehringer Ingelheim Animal Health; Virbac; Dechra Pharmaceuticals; Vetoquinol; Ceva Santé Animale; Norbrook; Bimeda |
| No.of Pages | 326 |
Segmentation
By Product Type
- Parasiticides
- Vaccines
- Anti-infectives
- Anti-inflammatory and analgesic drugs
- Dermatology drugs
- Endocrine and metabolic drugs
- Cardiac drugs
- Others
By Indication
- Infectious Diseases
- Dermatologic Diseases
- Pain
- Orthopedic Diseases
- Behavioral Diseases
- Other Indications
By Animal Type
- Dogs
- Cats
- Horses
- Others
By Route of Administration
- Oral
- Injectable
- Topical
- Others
By Distribution Channel
- Veterinary hospitals and clinics
- Retail pharmacies
- Online pharmacies
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Companion Animal Pharmaceutical Market?
What is the CAGR of the Companion Animal Pharmaceutical Market?
What is the largest segment in the Companion Animal Pharmaceutical Market?
What factors are driving growth in the Companion Animal Pharmaceutical Market?
Who are the leading companies in the Companion Animal Pharmaceutical Market?
Which region leads the Companion Animal Pharmaceutical Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Companion Animal Pharmaceuticals Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Companion Animal Pharmaceuticals Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 20173 million → 2032: USD 36996 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Companion Animal Pharmaceuticals Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Companion Animal Pharmaceuticals Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Companion Animal Pharmaceuticals Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Companion Animal Pharmaceuticals Market Drivers
- 3.3 Companion Animal Pharmaceuticals Market Restraints & Challenges
- 3.4 Companion Animal Pharmaceuticals Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Companion Animal Pharmaceuticals Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Companion Animal Pharmaceuticals Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Companion Animal Pharmaceuticals category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Companion Animal Pharmaceuticals Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Companion Animal Pharmaceuticals Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Companion Animal Pharmaceuticals. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Companion Animal Pharmaceuticals Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2025
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Companion Animal Pharmaceuticals Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2025)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Companion Animal Pharmaceuticals Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Companion Animal Pharmaceuticals (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Companion Animal Pharmaceuticals
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Companion Animal Pharmaceuticals Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Companion Animal Pharmaceuticals Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Companion Animal Pharmaceuticals Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Companion Animal Pharmaceuticals Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Companion Animal Pharmaceuticals Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Companion Animal Pharmaceuticals Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Companion Animal Pharmaceuticals Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Companion Animal Pharmaceuticals Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
