
Complementary and Alternative Medicines Market Overview:
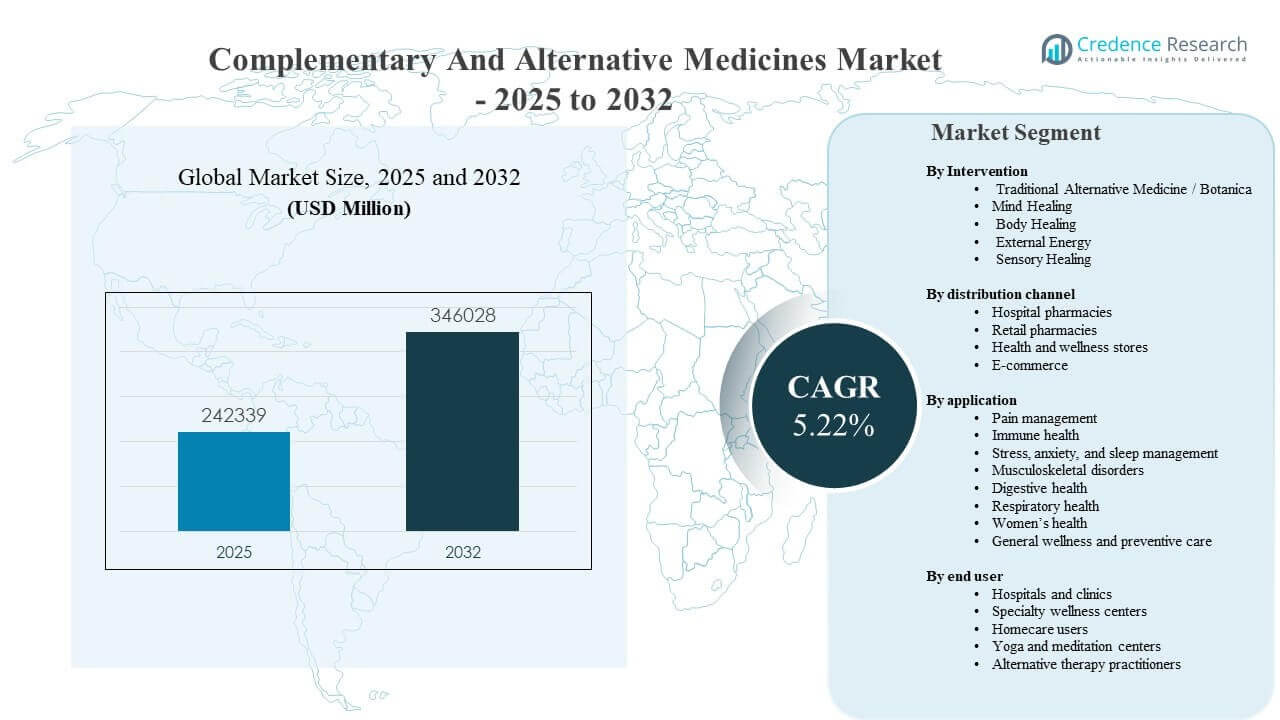
The global Complementary And Alternative Medicines Market size was estimated at USD 242,339 million in 2025 and is expected to reach USD 346,028 million by 2032, growing at a CAGR of 5.22% from 2025 to 2032. Rising consumer preference for holistic wellness approaches, including plant-based remedies and mind-body interventions, continues to expand demand across self-care, preventive health, and chronic-condition support. Wider omnichannel availability through pharmacies, wellness retail, and e-commerce is also improving access and repeat purchase behavior across mature and emerging markets.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Complementary And Alternative Medicines Market Size 2025 | USD 242,339million |
| Complementary And Alternative Medicines Market, CAGR | 5.22% |
| Complementary And Alternative Medicines Market Size 2032 | USD 346,028 million |
Key Market Trends & Insights
- The Complementary And Alternative Medicines Market is projected to expand at a CAGR of 5.22% from 2025–2032, increasing from USD 242,339 million (2025) to USD 346,028 million (2032).
- Traditional Alternative Medicine / Botanicals accounted for the largest intervention share at 36.4% in 2025, supported by routine consumption patterns and broad product availability.
- Asia Pacific represented an estimated 34.6% share in 2025, reflecting high utilization of heritage medicine systems and expanding modern retail distribution.
- Europe represented an estimated 29.3% share in 2025, supported by established consumer familiarity with several complementary modalities and strong wellness retail footprint.
- North America represented an estimated 24.7% share in 2025, reinforced by supplement penetration, practitioner-driven recommendations, and e-commerce acceleration.
Segment Analysis
Demand patterns in the Complementary And Alternative Medicines Market reflect two parallel buying behaviors: product-led purchases (botanicals, traditional formulations, supplements) and service-led utilization (mind-body practices, body-based therapies, energy and sensory modalities). Products tend to scale faster through retail and e-commerce, with repeat buying driven by preventive health routines, immunity support, digestion, and general wellness goals. Services expand through practitioner networks, specialty centers, and increasingly through digital instruction and tele-wellness formats.
Consumer adoption is also shaped by a mix of cultural familiarity and condition-specific value perceptions. Pain management, stress and sleep support, and musculoskeletal care often drive trial and continued use, especially when consumers seek non-pharmacological options or adjunct therapies. As clinical validation, standardization, and regulated quality improve in selected categories, provider recommendations and pharmacy-led education are strengthening credibility and influencing channel mix.
By Intervention Insights
Traditional alternative medicine and botanicals accounted for the largest share of 33.78% in 2025. The category leads because botanicals and established systems such as Ayurveda and Traditional Chinese Medicine fit daily preventive routines and are widely accessible through OTC retail and wellness outlets. Product standardization, branded formulations, and growing consumer familiarity with ingredients also support repeat purchase and premiumization. The category benefits from broad applicability across immunity, digestive health, and general wellness, which sustains demand across age groups.
By distribution channel Insights
Hospital pharmacies and retail pharmacies continue to support credibility-led purchasing, especially for consumers seeking guidance on interactions, dosing, and quality. Health and wellness stores play a key role in discovery and trial, particularly for premium botanicals and specialized formulations. E-commerce is expanding reach for both mass and niche brands through subscriptions, bundled offers, and content-led education. Channel performance is increasingly influenced by trust signals such as certifications, testing claims, practitioner endorsements, and transparent sourcing.
By application Insights
Pain management and musculoskeletal disorders remain strong demand drivers because many consumers seek non-invasive and longer-term supportive care options. Stress, anxiety, and sleep management are expanding use of mind healing and sensory modalities, supported by lifestyle pressures and broader acceptance of mental wellness routines. Immune health and digestive health benefit from repeat consumption cycles and seasonal demand patterns. Women’s health and respiratory health also contribute to growth through targeted formulations and integrative wellness programs.
By end user Insights
Hospitals and clinics primarily influence adoption where complementary approaches are positioned as supportive care or wellness adjuncts within broader treatment pathways. Specialty wellness centers drive service utilization through bundled programs spanning mind-body, body healing, and sensory practices. Homecare users represent a growing base as guided content, wearable-enabled routines, and product availability improve consistency of use. Yoga and meditation centers and alternative therapy practitioners play a critical role in awareness, trial, and long-term engagement through community-based participation.
Complementary And Alternative Medicines Market Drivers
Rising preference for natural and preventive health routines
Consumers increasingly prioritize natural positioning, clean-label expectations, and preventive routines that support daily wellbeing. Botanicals, teas, and supplements fit routine consumption behavior and offer broad accessibility across multiple channels. Cultural familiarity and intergenerational usage patterns further reinforce adoption in key consuming regions. Wellness brands also benefit from education-led marketing that frames complementary approaches as part of self-care and lifestyle optimization.
- For instance, Gaia Herbs introduced its industry-first “Meet Your Herbs” traceability platform by placing a unique identification number on every bottle, allowing consumers to check harvest, testing, and purity records online and via smartphone apps, a system the company developed after nearly 25 years in herbal manufacturing.
Expansion of stress, anxiety, and sleep management needs
Workload intensity, lifestyle pressures, and sleep disruption continue to raise demand for calming, restorative, and routine-based interventions. Mind healing and sensory healing approaches align with daily time-efficient habits and nonpharmacologic preferences. Yoga, meditation, breathwork, and therapeutic touch-related modalities gain traction through wider social acceptance and improved accessibility. Digital platforms also expand reach for guided routines and coaching-led programs.
- For instance, Headspace’s 21-session Anxiety and Depression Program, delivered in 5-10 minute daily sessions, reported a 34.5% reduction in anxiety symptoms, a 33.9% reduction in depression symptoms, and a 30.2% improvement in sleep quality in a randomized controlled trial involving 168 participants.
Broadening channel access and digital discovery
E-commerce and digital wellness ecosystems expand consumer access to products and services beyond local practitioner networks. Online education, reviews, and subscription models strengthen repeat purchase behavior for supplements and botanicals. Retail pharmacies and health and wellness stores remain important for trust-led conversion, especially among first-time users. Omnichannel strategies improve convenience and support continued market penetration across demographics.
Increased integration with conventional care pathways in select markets
Integrative programs and clinician openness in certain settings support structured referrals and service utilization. Hospitals, clinics, and specialty centers increasingly evaluate complementary modalities for supportive care and patient experience outcomes. This shift strengthens credibility and reduces perceived barriers for consumers who seek evidence-oriented guidance. Practitioner alignment also encourages standardized protocols that support repeat usage and coordinated care experiences.
Complementary And Alternative Medicines Market Challenges
Quality variability and inconsistent standardization remain persistent challenges across botanicals and supplement categories. Differences in sourcing, active compound consistency, labeling practices, and third-party testing can affect consumer trust and repeat purchase behavior. Regulatory approaches also vary by country, which creates complexity in claims, packaging, and cross-border commercialization. These factors can increase compliance costs and slow product expansion across markets.
Evidence expectations and skepticism in clinical settings can limit broader institutional adoption for selected modalities. Some interventions face limited consensus on efficacy, creating uneven acceptance across provider networks. Misleading claims from fringe providers can also increase scrutiny across the broader category and trigger tighter oversight. Pricing sensitivity can constrain access in markets where disposable income and insurance coverage remain limited.
- For instance, Pear Therapeutics’ reSET-O prescription digital therapeutic includes 67 interactive lessons, and the clinical evidence cited in support of its FDA market authorization reported 77.3% abstinence during weeks 9 to 12 versus 62.1% with treatment as usual, while dropout fell to 17.6% from 31.6%.
Complementary And Alternative Medicines Market Trends and Opportunities
Personalized wellness, including condition-specific formulations and lifestyle-aligned protocols, is accelerating product innovation. Brands increasingly position offerings around gut health, immune support, women’s health, and stress resilience using format improvements and differentiated ingredient blends. Data-driven engagement through apps, coaching, and guided routines supports higher retention for mind-body interventions. Cross-selling between services and products creates bundled value propositions across multiple end users.
- For instance, Viome uses metatranscriptomic sequencing to power personalized wellness programs with over 30 health scores and more than 400 food recommendations in its app, while also enabling users to order customized supplements, prebiotics, and probiotics through the same account.
Premiumization is strengthening opportunities for brands that invest in sourcing transparency and verified quality systems. Clean-label positioning, ethical sourcing, and third-party testing can support pricing power and stronger consumer trust. Practitioner partnerships and retail expansion can broaden reach for professional-grade supplement portfolios. Emerging markets also offer runway through increased awareness, urban wellness center expansion, and growing modern trade penetration.
Regional Insights
North America
North America represented an estimated 24.7% share in 2025, supported by high consumer spending on supplements and wellness products and strong penetration of retail pharmacies and specialty wellness stores. The region benefits from broad digital adoption that supports product discovery and repeat purchasing through e-commerce. Practitioner influence in integrative and functional wellness ecosystems supports protocol-led consumption. Demand is also strengthened by large addressable populations managing chronic pain, stress, and sleep issues.
Europe
Europe represented an estimated 29.3% share in 2025, supported by established familiarity with several complementary practices and steady demand for botanicals and body-based therapies. A strong wellness retail footprint and specialized practitioners support service utilization across urban centers. Consumers often prioritize natural positioning and trusted brands with visible quality assurances. The region also benefits from structured consumer behavior around preventive care and wellness routines.
Asia Pacific
Asia Pacific represented an estimated 34.6% share in 2025, reflecting deep cultural integration of traditional systems and large-scale consumer utilization. The region benefits from both mass-market household use and premium branded offerings, with modernization of formulations and packaging improving mainstream accessibility. Expanding wellness centers and practitioner networks support service adoption, especially for musculoskeletal, digestive, and preventive care needs. Digital channels also accelerate access among younger consumer cohorts across major markets.
Latin America
Latin America represented an estimated 7.9% share in 2025, supported by rising interest in plant-based wellness and lifestyle-led self-care. Demand is strengthened by growing modern retail availability and increasing use of supplements for immune and digestive positioning. Market development remains uneven across countries due to differences in spending power and availability of trained practitioners. Brand-building and education-led marketing can improve conversion and repeat purchase behavior.
Middle East & Africa
Middle East and Africa represented an estimated 3.5% share in 2025, supported by growth in urban wellness centers, premium retail expansion, and higher health awareness in key cities. Adoption is influenced by affordability, uneven distribution, and limited practitioner density in many markets. Private clinics and premium wellness operators play an outsized role where integrative offerings are available. E-commerce growth can expand access, particularly for supplements and packaged botanicals.
Competitive Landscape
Competition in the Complementary And Alternative Medicines Market is shaped by brand trust, ingredient sourcing, formulation differentiation, and omnichannel reach. Leading players compete through standardized quality, targeted condition-specific portfolios, and education-led marketing that improves consumer understanding and repeat purchase. Partnerships with practitioners, wellness centers, and retail chains help reinforce credibility, while e-commerce capabilities support subscription growth and personalized regimen bundles.
Boiron is positioned around recognized homeopathic heritage and broad consumer access, with a focus on consistent product availability and clear usage communication. Brand differentiation typically depends on trust signals, packaging clarity, and consumer familiarity, which support repeat purchasing for common wellness needs. As digital engagement grows, education-led content and retail partnerships become more important for discovery and conversion. Portfolio breadth across common indications also helps maintain shelf presence in key channels.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Boiron
- Herb Pharm
- Himalaya Wellness
- Traditional Medicinals
- Nature’s Sunshine Products
- Pure Encapsulations
- Tsumura & Co.
- Weleda AG
- Gaia Herbs
- Standard Process
- Jarrow Formulas
- Columbia Nutritional
- Nordic Nutraceuticals
- Sheng Chang Pharmaceutical
- AYUSH Ayurvedic Pte Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In a March 2026, Herbalife said it had agreed to acquire certain assets from Bioniq, a UK-based personalized supplements company, to expand its personalized nutritional supplement capabilities. The company added that the deal supports its push to become a more technology-enabled, data-driven wellness platform and scale personalized nutrition globally.
- In an October 2025, Ashpveda partnered with Dabur NewU to launch its Festive 2025 Collection across 20 stores. The rollout expanded the reach of Ashpveda’s Ayurvedic skincare, haircare, and personal care offerings through Dabur NewU’s retail network.
- In an August 2025, Reliance Consumer Products acquired a majority stake in a joint venture with Naturedge Beverages to enter the healthy functional beverage segment. The company said this strengthens its herbal-natural beverage portfolio through Shunya drinks, which are positioned around Indian herbs such as Ashwagandha, Brahmi, Khus, Kokum, and green tea.
- In a July 2025, Apollo AyurVAID launched its first “Tested Safe” Ayurveda products, marking its expansion beyond clinical care into classical formulations, OTC products, and medical foods. The company also said it had partnered with Avesthagen Limited to co-develop scientifically validated botanical-actives based dietary supplements, reinforcing its evidence-based Ayurveda strategy.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 242,339 million |
| Revenue forecast in 2032 | USD 346,028 million |
| Growth rate (CAGR) | 5.22% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Intervention; By distribution channel; By application; By end user |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Boiron; Herb Pharm; Himalaya Wellness; Traditional Medicinals; Nature’s Sunshine Products; Pure Encapsulations; Tsumura & Co.; Weleda AG; Gaia Herbs; Standard Process; Jarrow Formulas; Columbia Nutritional; Nordic Nutraceuticals; Sheng Chang Pharmaceutical; AYUSH Ayurvedic Pte Ltd. |
| No. of Pages | 332 |
Segmentation
By Intervention
Traditional Alternative Medicine / Botanicals
- Ayurveda
- Traditional Chinese Medicine
- Traditional Japanese Medicine
- Traditional Korean Medicine
- Traditional Mongolian Medicine
- Traditional Tibetan Medicine
- Naturopathic Medicine
- Apitherapy
- Bach Flower Therapy
- Zang Fu Theory
- Others
Mind Healing
- Autosuggestion
- Hypnotherapy
- Neuro-linguistic Programming
- Self-hypnosis
- Spiritual Mind Treatment
- Transcendental Meditation
- Others
Body Healing
- Acupressure
- Acupuncture
- Alexander Technique
- Auriculotherapy
- Autogenic Training
- Chiropractic
- Cupping Therapy
- Kinesiology
- Osteomyology
- Osteopathy
- Pilates
- Qigong
- Reflexology
- Yoga
- Others
External Energy
- Magnetic Therapy
- Bio-magnetic Therapy
- Magnetic Resonance Therapy
- Radionics
- Reiki
- Therapeutic Touch
- Chakra Healing
- Others
Sensory Healing
- Aromatherapy
- Music Therapy
- Sonopuncture
- Sound Therapy
- Others
By Distribution Channel
- Hospital pharmacies
- Retail pharmacies
- Health and wellness stores
- E-commerce
By Application
- Pain management
- Immune health
- Stress, anxiety, and sleep management
- Musculoskeletal disorders
- Digestive health
- Respiratory health
- Women’s health
- General wellness and preventive care
By End User
- Hospitals and clinics
- Specialty wellness centers
- Homecare users
- Yoga and meditation centers
- Alternative therapy practitioners
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Complementary And Alternative Medicines Market?
What is the CAGR for the Complementary And Alternative Medicines Market?
Which intervention segment is the largest in the Complementary And Alternative Medicines Market?
What factors are driving growth in the Complementary And Alternative Medicines Market?
Who are the leading companies in the Complementary And Alternative Medicines Market?
Which region leads the Complementary And Alternative Medicines Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 242,339 million → 2032: USD 346,028 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Complementary And Alternative Medicines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Complementary And Alternative Medicines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Complementary And Alternative Medicines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Complementary And Alternative Medicines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Complementary And Alternative Medicines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Complementary And Alternative Medicines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Complementary And Alternative Medicines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Complementary And Alternative Medicines Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 242,339 million → 2032: USD 346,028 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Complementary And Alternative Medicines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Complementary And Alternative Medicines Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Complementary And Alternative Medicines Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Complementary And Alternative Medicines Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

