
Market Overview:
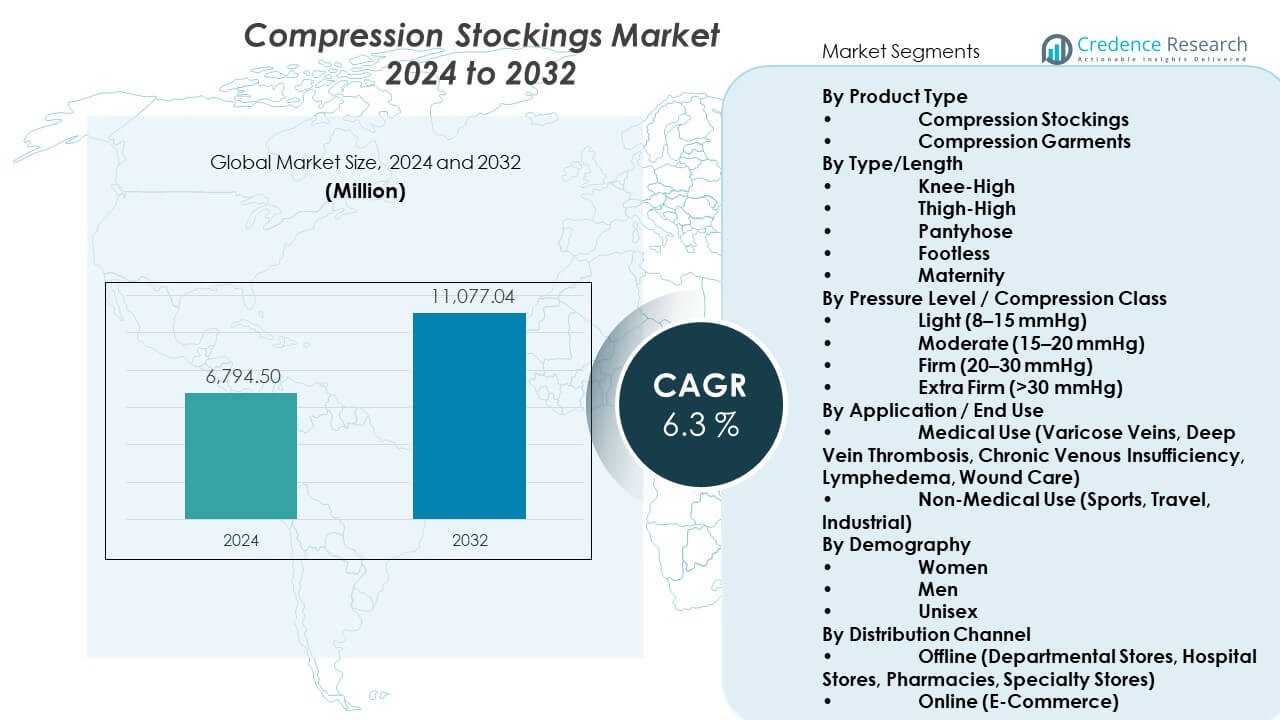
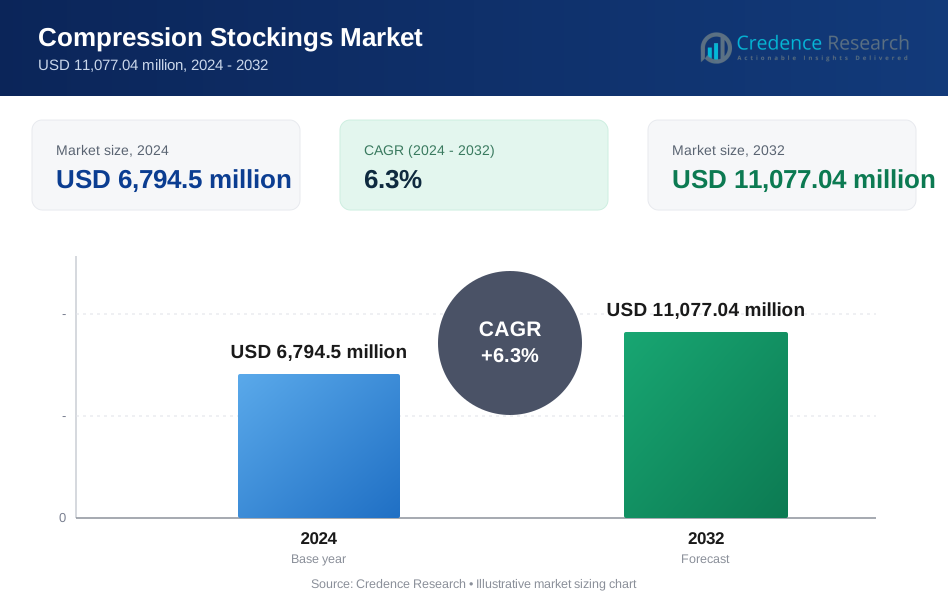
The Compression Stockings Market shows steady expansion due to rising awareness of vein care and preventive therapy. The market is projected to grow from USD 6,794.5 million in 2024 to USD 11,077.04 million by 2032, with a compound annual growth rate (CAGR) of 6.3% during the forecast period. Strong product innovation and wider retail access improve overall penetration.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Compression Stockings Market Size 2024 | USD 6,794.5 Million |
| Compression Stockings Market, CAGR | 6.3% |
| Compression Stockings Market Size 2032 | USD 11,077.04 Million |
The market records stronger drivers due to a higher focus on vascular health and early intervention. Rising sedentary lifestyles and long working hours increase leg discomfort, which lifts stocking use among office workers. Athletes adopt graduated compression for better blood flow and recovery support. Home-care growth encourages user-friendly designs with softer fabrics and better breathability. Hospitals prescribe these stockings for post-surgery care and long-term circulation support. More brands develop fashion-friendly designs that appeal to younger users. Medical professionals promote compression therapy in preventive care programs. These factors sustain broad adoption across age groups.
Regional demand varies due to lifestyle patterns and healthcare awareness. North America leads due to strong clinical adoption and early diagnosis of venous disorders. Europe follows with wide usage among elderly groups and strong medical guidelines. Asia Pacific is emerging due to urban lifestyles, a rising elderly population, and wider retail access. Countries like China and India expand faster because of improving healthcare access and growing preventive care habits. Latin America and the Middle East show moderate but rising demand as awareness improves. Africa remains early-stage but benefits from gradual expansion of vascular care services.
Market Insights:
- The Compression stockings market reached USD 6,794.5 million in 2024 and is projected to hit USD 11,077.04 million by 2032, growing at a 3% CAGR during the forecast period.
- North America leads with 34% share due to strong clinical adoption, high awareness, and established vascular care programs.
- Europe follows with 29% share, supported by advanced healthcare systems and broad acceptance among elderly populations; Asia Pacific holds 24% share, driven by urbanization and wider preventive care adoption.
- Asia Pacific is the fastest-growing region, supported by rising venous disorder cases, improving hospital infrastructure, and increased lifestyle use across China, India, and Japan.
- The Knee-High segment holds the largest share at 41%, driven by comfort and clinical preference, while the Moderate Compression (15–20 mmHg) class accounts for 33%, supported by strong demand for daily preventive use.
Market Drivers:
Growing Need for Circulation Support Across Age Groups
The Compression Stockings Market grows due to rising cases of venous disorders in aging groups. Many adults face leg fatigue from long hours of sitting or standing in daily routines. Doctors recommend stockings for post-surgery care and chronic venous conditions. Sports users adopt higher compression levels to improve circulation during training. Office workers use light compression to reduce swelling after extended workdays. Home-care settings prefer soft fabrics that support long-term therapy. Wider medical awareness increases early adoption across demographics. Product diversity lifts acceptance among younger and older users.
- For instance, CEP Sportswear uses medi Compression Technology that maintains medically tested graduated pressure for performance and recovery, verified through medi GmbH’s clinical compression standards.
Rising Prevalence of Lifestyle-Related Vascular Issues
Demand increases due to higher cases of varicose veins linked to inactive routines. People with obesity experience more circulation concerns that require preventive therapy. Hospitals prescribe medical-grade stockings after orthopedic or vascular procedures. Athletes use compression gear to improve recovery and reduce muscle stress. Busy professionals seek wearable solutions that ease daily discomfort. Brands develop lighter, breathable designs for long shifts and travel. Improved fabric strength supports steady pressure for clinical outcomes. Retail channels expand access for consumers with lifestyle-linked conditions.
- For instance, Sigvaris medical stockings are ISO 13485–certified and validated for precise graduated compression through controlled manufacturing and pressure testing.
Expansion of Preventive Healthcare and Home-Based Therapy
Preventive care programs highlight early management of leg swelling and circulation issues. Consumers learn about compression benefits through clinics and fitness centers. Home-care support teams encourage stockings for mobility improvement. Elderly users adopt compression gear to reduce discomfort during walking. Medical-grade variants aid long-term treatments for chronic venous insufficiency. Product innovation supports easy wearing mechanisms for daily use. Hospitals use stockings in recovery rooms to reduce deep vein thrombosis risk. Preventive messaging lifts trust in compression therapy.
Higher Adoption Driven by Sports, Travel, and Work Routines
Active groups use compression stockings to improve performance and reduce fatigue. Frequent travelers adopt graduated compression to manage swelling during long flights. Office staff rely on mild compression to ease daily strain from prolonged work. Healthcare providers promote compression during pregnancy for leg relief. Athletes prefer durable fibers that maintain pressure during intense movement. Retailers offer wider designs to match lifestyle needs and comfort habits. Awareness campaigns highlight benefits for recovery and circulation improvement. Broader lifestyle adoption supports steady demand.
Market Trends:
Shift Toward Advanced Fabrics and Seamless Construction
The Compression Stockings Market witnesses stronger interest in breathable and soft materials. Manufacturers use seamless knitting to increase comfort during long wear hours. Newer fabric blends offer moisture control for active and medical users. Brands integrate stronger elasticity to maintain consistent pressure levels. Consumers prefer lightweight designs that look closer to daily wear socks. Hospitals request durable materials that hold compression after repeated washing. Trend shifts favor thin compression apparel suitable for long shifts. Better textile engineering supports product acceptance across regions.
- For instance, Juzo applies its exclusive FiberSoft® technology, which wraps every elastic (Lycra) fiber with soft, protective threads (polyamid fibers), to provide a comfortable, breathable, and durable garment.
Increasing Interest in Fashion-Friendly and Discreet Designs
Users now demand products that blend with everyday outfits for better comfort. Brands offer skin-tone shades that match diverse user groups. Fashion-forward patterns gain adoption in younger demographics. Travel users prefer sleek stockings that fit active wardrobes. Athletes choose bold colors and modern cuts for sport routines. Design-led innovation improves confidence among first-time users. Retailers expand options that resemble modern hosiery. Style upgrades support broader lifestyle integration.
Growing Use of Digital Platforms for Custom Fit Solutions
Consumers rely on digital tools to pick correct compression levels. Retailers provide online measurement guides to support proper sizing. Users check mobile apps that track leg symptoms and usage patterns. E-commerce platforms expand access in areas with limited retail networks. Digital channels help compare product types for home-care or travel use. Clinics use virtual fitting support during telehealth consultations. Brands offer size calculators for accurate fitting. Online engagement improves confidence in product selection.
Rising Integration of Smart Textiles and Performance Features
Smart fabrics attract interest due to embedded sensors for health tracking. These designs monitor pressure distribution to improve medical outcomes. Athletes explore variants with temperature regulation for outdoor routines. Brands test fabrics that adjust compression during movement. Hospitals show interest in heat-regulating fibers that aid recovery. Travel-friendly options include odor control and antibacterial layers. Sports users benefit from reinforced zones for high-intensity use. Innovation enhances performance-oriented adoption.
Market Challenges Analysis:
Limited Awareness and Adoption Barriers Among New Users
The Compression Stockings Market faces challenges due to low understanding of correct usage. Many users struggle with sizing, which reduces comfort during daily wear. Incorrect pressure selection leads to dissatisfaction and early discontinuation. Retail staff often lack training for guiding buyers through technical grades. Elderly users find difficulty wearing high-compression variants without assistance. Fashion concerns lower acceptance among younger groups. Hospitals need better patient education after surgical procedures. Limited clarity on product types affects overall adoption rates.
High Product Costs and Variations in Medical Compliance
Price-sensitive users hesitate to purchase premium medical-grade variants. Some buyers shift to low-cost options that lack quality and durability. Insurance coverage varies across regions, limiting adoption in specific groups. Users avoid regular replacement cycles due to higher expenses. Hospitals face budget limits when procuring large volumes for patient care. Non-compliance reduces clinical outcomes among chronic condition users. Product misuse leads to discomfort and lower adherence. Market growth slows where affordability remains a concern.
Market Opportunities:
Rising Focus on Preventive Care and Customized Compression Solutions
The Compression Stockings Market gains new opportunities through advanced sizing systems and tailored compression levels. Medical teams promote early screening for venous disorders, increasing product uptake. Brands develop personalized fit solutions that improve comfort for long-term users. Hospitals incorporate compression therapy into preventive care programs. Sports groups demand performance-oriented compression gear with stronger durability features. Digital platforms enable guided selection for new buyers. Companies expand premium offerings for professional and lifestyle users. Growing health awareness lifts adoption across diverse age brackets.
Growth Potential in Emerging Markets and Lifestyle-Driven Segments
Emerging economies show rising demand due to urban lifestyles and higher healthcare access. Younger consumers adopt compression gear for fitness and travel routines. Clinics expand vascular care services in fast-developing regions. Retail channels grow through pharmacies, sports stores, and digital platforms. Product innovation targets breathable, stylish, and easy-wear designs. Hospitals support compression therapy in more recovery plans. Brands explore partnerships to strengthen regional distribution. Lifestyle-focused adoption widens the overall market base.
Market Segmentation Analysis:
By Product Type
The Compression Stockings Market leads with compression stockings due to strong clinical adoption across hospitals and home-care settings. Compression garments follow as users seek broader coverage for chronic venous issues. Stockings retain higher preference for daily wear and preventive use. Garments gain traction among patients who require extended support across larger leg areas. Sports users adopt lighter designs for comfort during training. Medical teams recommend stockings after surgery for circulation improvement. Both categories benefit from better fabric technology. It supports demand across long-term therapy groups.
- For instance, Thuasne’s Venoflex Medical line undergoes laboratory-controlled gradient compression testing to ensure accuracy for medical use.
By Type/Length
Knee-high stockings hold stronger usage due to comfort and easy application for daily routines. Thigh-high variants serve patients with advanced venous concerns. Pantyhose designs attract users seeking full-leg coverage in lifestyle or work settings. Footless styles gain adoption in warmer regions. Maternity variants support swelling and circulation needs during pregnancy. Each type meets specific mobility and comfort needs. Broader choices improve adoption across age groups. Retailers expand these options to support personal preference.
- For instance, Sigvaris pantyhose styles use double-covered yarns tested for stretch retention and glide performance during donning.
By Pressure Level / Compression Class
Light and moderate compression levels record higher use among first-time buyers and lifestyle-focused users. Firm and extra-firm classes serve clinical needs for chronic venous insufficiency and post-treatment care. Light compression suits long work shifts, travel routines, and mild symptoms. Moderate pressure supports early varicose vein management. Stronger classes require professional guidance to ensure correct application. Each level targets specific therapeutic needs. Better product labeling supports correct pressure selection. Awareness campaigns help users understand benefits.
By Application / End Use
Medical use dominates due to rising venous disorders and wider hospital adoption. Conditions like varicose veins, DVT, and lymphedema drive steady demand. Wound care teams integrate compression for recovery protocols. Non-medical use grows in sports, travel, and industrial routines. Athletes use compression to ease muscle fatigue and improve performance. Travelers choose it for swelling management. Industrial workers adopt mild compression for long standing hours. Each segment supports diverse usage needs.
By Demography
Women lead usage due to higher prevalence of venous concerns and pregnancy-related swelling. Men adopt compression during sports, industrial work, and medical therapy. Unisex designs support broader comfort and fit preferences. Retailers expand neutral shades for both gender groups. Demographic diversity strengthens category appeal. Product lines adapt to body shape variations. Wider size ranges increase accessibility. Each group contributes to stable category growth.
By Distribution Channel
Offline channels lead due to strong trust in pharmacies, hospital stores, and specialty outlets. Trained staff guide buyers through sizing and pressure selection. Department stores offer lifestyle variants. Online channels grow quickly with better convenience and digital measurement guides. E-commerce platforms expand access in remote areas. Users compare brands and compression levels more easily. Online growth supports new consumer entry. Digital reach lifts overall market penetration.
Segmentation:
By Product Type
- Compression Stockings
- Compression Garments
By Type/Length
- Knee-High
- Thigh-High
- Pantyhose
- Footless
- Maternity
By Pressure Level / Compression Class
- Light (8–15 mmHg)
- Moderate (15–20 mmHg)
- Firm (20–30 mmHg)
- Extra Firm (>30 mmHg)
By Application / End Use
- Medical Use (Varicose Veins, Deep Vein Thrombosis, Chronic Venous Insufficiency, Lymphedema, Wound Care)
- Non-Medical Use (Sports, Travel, Industrial)
By Demography
- Women
- Men
- Unisex
By Distribution Channel
- Offline (Departmental Stores, Hospital Stores, Pharmacies, Specialty Stores)
- Online (E-Commerce)
- North America (US, Canada, Mexico)
- Europe (Germany, France, UK, Italy, Spain, Rest of Europe)
- Asia-Pacific (China, India, Japan, Australia, New Zealand, Rest of APAC)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East & Africa (MEA)
Regional Analysis:
North America
The Compression Stockings Market holds a leading position in North America with nearly 34% share. Strong clinical use supports higher adoption across hospitals and home-care settings. The region records greater awareness of venous disorders and preventive therapy. It benefits from wider insurance coverage for medical compression products. Retail presence in pharmacies and specialty stores strengthens access for adults and elderly users. Sports adoption also grows as athletes use compression for recovery. Technology-driven product upgrades help maintain strong market penetration.
Europe
Europe follows with an estimated 29% share, driven by strong clinical guidelines and wide acceptance among aging groups. Healthcare systems in Germany, France, and the UK integrate compression therapy into vascular care. Users adopt stockings for long work shifts, travel, and pregnancy-related swelling. Manufacturers in the region offer advanced textile solutions that improve comfort. Retail networks support access through pharmacies and medical stores. Awareness campaigns help users adopt compression early. The market stays stable due to high preventive care focus.
Asia Pacific
Asia Pacific accounts for nearly 24% share and shows the fastest growth due to rising urban lifestyles and larger elderly populations. Countries like China, India, and Japan drive strong adoption across medical and non-medical applications. It benefits from expanding vascular care centers in urban hospitals. Younger users adopt compression for sports, travel, and long working hours. E-commerce growth supports access to multiple pressure levels and wearable designs. Manufacturers launch affordable options to meet regional needs. Market expansion continues with higher preventive care awareness.
Latin America and Middle East & Africa (MEA)
Latin America holds around 8% share, supported by growing healthcare access and rising awareness of venous disorders. Brazil and Mexico lead usage due to wider hospital networks. MEA captures nearly 5% share, with growth driven by increasing chronic venous cases and expanding retail channels. Both regions show rising adoption in travel and industrial sectors. Hospitals promote compression therapy in surgical recovery. Digital retail platforms support product reach in developing urban areas. Market growth improves as awareness expands across demographics.
Key Player Analysis:
- SIGVARIS GROUP
- medi GmbH & Co. KG
- BSN Medical GmbH (Essity)
- 3M Company (3M Health Care)
- Enovis Corporation (DJO Global)
- Julius Zorn GmbH (Juzo)
- Cardinal Health
- Essity Aktiebolag
- Mölnlycke Health Care AB
- Tactile Systems Technology, Inc. (Tactile Medical)
- Paul Hartmann AG
- Medtronic Plc
- Medline Industries
- 2XU Pty Ltd.
- Spanx, LLC
- Triumph International Corporation
- Leonisa, Inc.
- European Lingerie Group AB
- Creswell Sock Mills
- Bio Compression Systems, Inc.
- Stryker
- FIGS, Inc.
- Thuasne
Competitive Analysis:
The Compression Stockings Market shows strong competition led by global medical textile brands and specialist compression manufacturers. Leading players focus on advanced knitting technologies, improved fabric durability, and better pressure accuracy. It benefits from companies expanding clinical-grade offerings to address venous disorders and post-surgical needs. Many brands strengthen portfolios with breathable designs and lifestyle-friendly variants. Partnerships with hospitals improve adoption across recovery programs. Sports brands also enter the category with performance-oriented compression products. Established players maintain dominance through wide retail networks and strong medical endorsements. Competitive pressure increases as new entrants introduce affordable digital-fit solutions.
Recent Developments:
- In October 2025, Cardinal Health announced the international launch of the Kendall SCD SmartFlow™ Compression System, extending its availability beyond the U.S. market. The all-in-one solution is designed to enhance blood circulation and treat pain and swelling related to venous stasis, providing clinicians with operational efficiencies through its automated technology features.
- In June 2025, Mölnlycke Health Care AB announced its largest investment to date-a €115 million expansion of its wound care manufacturing capacity in Brunswick, Maine, USA. The five-year investment will increase the facility's production capabilities by 10% and create new employment opportunities. Although primarily focused on wound care products, this expansion strengthens Mölnlycke's overall U.S. manufacturing infrastructure and supply chain capabilities.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type and By Type/Length. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise due to higher awareness of venous disorders across age groups.
- Preventive care adoption will expand in office workers and travel users.
- Medical-grade variants will gain traction in postoperative recovery programs.
- Lifestyle compression designs will grow with improved fabric comfort.
- Digital measurement tools will improve product fit and reduce sizing errors.
- Sports and fitness use will expand among younger consumers.
- E-commerce will strengthen distribution across emerging markets.
- Manufacturers will focus on breathable, skin-friendly materials.
- Hospitals will integrate compression therapy into broader vascular care.
- New entrants will target affordable compression solutions for home users.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Need for Circulation Support Across Age Groups
Increasing prevalence of venous disorders among aging populations and adults with sedentary lifestyles is driving demand for compression stockings, as these products are recommended for post-surgery care, chronic venous conditions, and daily fatigue relief.
Rising Prevalence of Lifestyle-Related Vascular Issues
More cases of varicose veins and circulation problems linked to obesity and inactive routines are prompting hospitals and clinics to prescribe compression stockings, while athletes and office workers adopt them for recovery and daily comfort.
Expansion of Preventive Healthcare and Home-Based Therapy
Preventive care programs and home-care support teams are promoting early adoption of compression stockings for mobility improvement and long-term therapy, leading to broader usage across demographics and increased product innovation for ease of use.
Higher Adoption Driven by Sports, Travel, and Work Routines
Active individuals, frequent travelers, and professionals are increasingly using compression stockings to manage swelling, reduce fatigue, and improve performance, supported by product designs tailored for comfort and lifestyle integration.
Shift Toward Advanced Fabrics and Fashion-Friendly Designs
Manufacturers are innovating with breathable, seamless, and stylish compression stockings that appeal to both medical and lifestyle users, enhancing comfort and encouraging adoption among younger and fashion-conscious consumers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Compression stockings market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Compression stockings market projected to grow between 2024 and 2032?
Which Compression stockings market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Compression stockings market?
Who are the leading companies in the Compression stockings market?
Which region commanded the largest share of the Compression stockings market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type/Length
- 1.2.1 Knee-High
- 1.2.2 Thigh-High
- 1.2.3 Pantyhose
- 1.2.4 Footless
- 1.2.5 Maternity
- 1.3 By Product Type
- 1.3.1 Compression Stockings
- 1.3.2 Compression Garments
- 1.4 By Pressure Level / Compression Class
- 1.4.1 Light (8–15 mmHg)
- 1.4.2 Moderate (15–20 mmHg)
- 1.4.3 Firm (20–30 mmHg)
- 1.4.4 Extra Firm (>30 mmHg)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,794.5 million → 2032: USD 11,077.04 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Compression Stockings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Compression Stockings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Compression Stockings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Compression Stockings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Compression Stockings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Compression Stockings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Compression Stockings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Compression Stockings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,794.5 million → 2032: USD 11,077.04 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Compression Stockings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type/Length - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Knee-High
- 12.3.7.2 Thigh-High
- 12.3.7.3 Pantyhose
- 12.3.7.4 Footless
- 12.3.7.5 Maternity
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Compression Stockings
- 12.4.7.2 Compression Garments
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Pressure Level / Compression Class - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Light (8–15 mmHg)
- 12.5.7.2 Moderate (15–20 mmHg)
- 12.5.7.3 Firm (20–30 mmHg)
- 12.5.7.4 Extra Firm (>30 mmHg)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Compression Stockings Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Compression Stockings Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Compression Stockings Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 SIGVARIS GROUP
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 medi GmbH & Co. KG
- 17.4 BSN Medical GmbH (Essity)
- 17.5 3M Company (3M Health Care)
- 17.6 Julius Zorn GmbH (Juzo)
- 17.7 Cardinal Health
- 17.8 Mölnlycke Health Care AB
- 17.9 Tactile Systems Technology, Inc. (Tactile Medical)
- 17.10 Medline Industries
- 17.11 Thuasne
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

