
Market Overview:
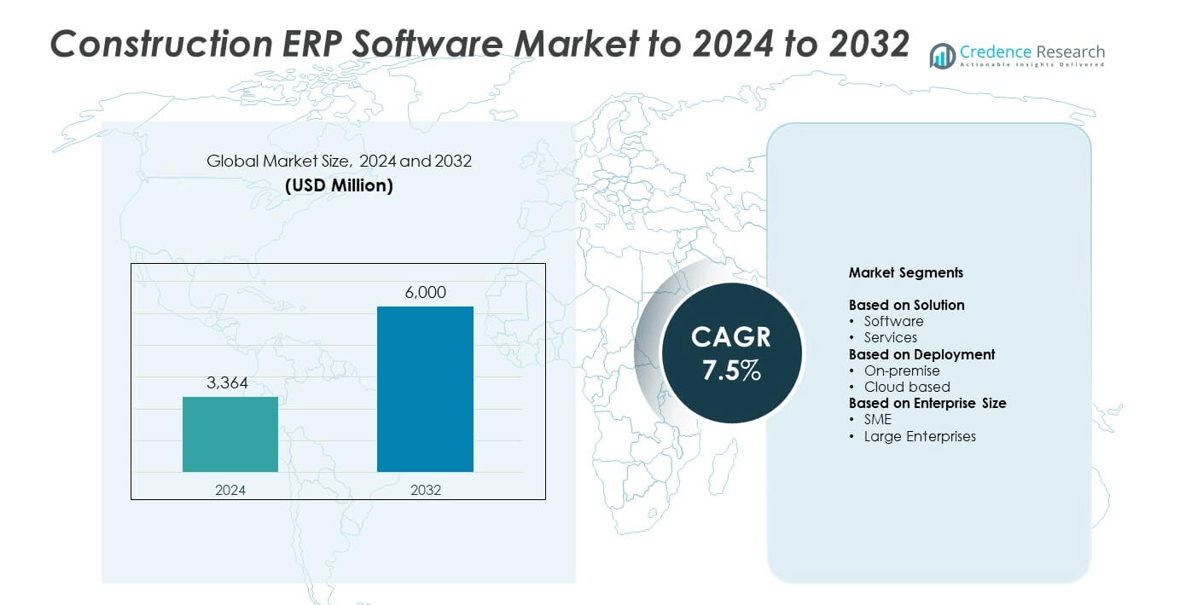
Construction ERP Software Market size was valued USD 3,364 million in 2024 and is anticipated to reach USD 6,000 million by 2032, at a CAGR of 7.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Construction ERP Software Market Size 2024 | USD 3,364 million |
| Construction ERP Software Market, CAGR | 7.5% |
| Construction ERP Software Market Size 2032 | USD 6,000 million |
The construction ERP software market is led by major players including Oracle, Procore Technologies, SAP, Microsoft, CMiC Global Inc, Autodesk, In4Velocity Systems, Deltek, Sage Group, and Viewpoint. These companies dominate through advanced cloud-based ERP solutions that integrate project management, financial planning, and analytics for construction enterprises. North America held the largest market share of 38% in 2024, driven by high digital adoption and strong presence of global ERP providers. Europe followed with 25%, supported by regulatory compliance and modernization in construction operations. Asia-Pacific, with a 22% share, emerged as the fastest-growing region due to rapid urbanization and infrastructure expansion.
Market Insights
- The construction ERP software market was valued at USD 3,364 million in 2024 and is projected to reach USD 6,000 million by 2032, growing at a CAGR of 7.5%.
- Growing demand for real-time project management, cost tracking, and resource optimization is driving ERP adoption across construction enterprises.
- Cloud-based deployment held a 57.9% share in 2024, supported by rising digitalization and the need for remote accessibility in construction operations.
- The market remains competitive, with global players focusing on AI integration, mobile accessibility, and modular ERP platforms to enhance operational efficiency.
- North America led the market with a 38% share in 2024, followed by Europe at 25% and Asia-Pacific at 22%, driven by rapid infrastructure development and government investments in smart construction initiatives.
Market Segmentation Analysis:
By Solution
The software segment dominated the construction ERP software market with a 64.7% share in 2024. Its leadership is driven by the growing use of integrated modules for project management, accounting, and supply chain operations. Software solutions help contractors manage resources, track progress, and enhance decision-making through real-time analytics. Increasing demand for centralized platforms that streamline workflows across departments supports this dominance. The services segment is expanding as enterprises seek implementation, customization, and maintenance support to improve operational efficiency and user adoption.
- For instance, Procore Technologies' unified platform supports over 17,000 customers and more than 2 million annual users globally, across more than 150 countries. As of early 2024 data, over 3 million projects have run on the Procore platform.
By Deployment
The cloud-based segment held the largest share of 57.9% in 2024. Its growth is attributed to cost efficiency, scalability, and accessibility across remote project sites. Cloud deployment enables real-time data synchronization and collaboration between field teams and management, improving project transparency. Construction firms prefer cloud platforms for lower IT infrastructure costs and faster software updates. The on-premise model continues to attract large enterprises with strict data control and security requirements, particularly in regions with limited internet reliability.
- For instance, Oracle Corporation has a large customer base for its two main cloud ERP products. The company has a community of more than 11,000 customers using Oracle Fusion Cloud ERP and over 38,000 customers using Oracle NetSuite globally, totaling over 49,000 organizations as of late 2024.
By Enterprise Size
The large enterprise segment accounted for a 62.3% share in 2024. These organizations adopt ERP solutions to manage multiple construction projects, suppliers, and subcontractors across geographies. Advanced analytics and automation tools in ERP systems enhance compliance and cost tracking for large-scale operations. Demand is also fueled by the need to integrate financial and resource planning within corporate systems. Small and medium enterprises (SMEs) are increasingly embracing cloud-based ERP platforms to improve project visibility and reduce administrative costs.
Key Growth Drivers
Increasing Demand for Real-Time Project Management
The rising complexity of large-scale infrastructure projects has created a strong need for real-time project tracking and reporting. Construction ERP software enables centralized control over budgeting, scheduling, and procurement activities. Its ability to enhance collaboration across multiple departments and locations drives faster decision-making and reduces project delays. The growing preference for digital project management platforms among contractors and developers continues to accelerate ERP adoption across global markets.
- For instance, SAP S/4HANA reported that by mid-2018 it had been implemented by approximately 8,900 customers worldwide - highlighting its appeal to large-scale organisations.
Integration of IoT and Data Analytics in Construction
The integration of IoT sensors and advanced analytics into ERP systems enhances operational visibility and predictive planning. These technologies allow construction firms to monitor equipment, labor, and material usage in real time. By leveraging data-driven insights, companies can reduce downtime and improve asset performance. The growing focus on digital transformation in construction is strengthening the adoption of ERP platforms with built-in analytics and IoT capabilities.
- For instance, Caterpillar has 1.5 million+ connected assets generating operational telemetry.
Government Initiatives and Infrastructure Investments
Ongoing public infrastructure development and smart city projects are fueling ERP software demand. Governments worldwide are investing in road, bridge, and housing projects that require efficient resource and cost management systems. ERP solutions support compliance with project standards, timelines, and budget constraints. As infrastructure spending increases, construction companies are adopting ERP tools to meet regulatory demands and enhance transparency across the project lifecycle.
Key Trends & Opportunities
Shift Toward Cloud-Based ERP Solutions
Construction companies are increasingly adopting cloud-based ERP systems to streamline project operations and reduce IT costs. Cloud deployment allows real-time collaboration between field and office teams, improving communication and data accuracy. The flexibility of subscription-based models also supports scalability for growing firms. As construction businesses prioritize agility and remote accessibility, cloud ERP adoption is becoming a major opportunity in the market.
- For instance, NetSuite ERP, a cloud-native ERP platform, currently serves more than 43,000 customers, organizations, and subsidiaries globally, across over 220 countries and dependent territories.
Rise of AI-Driven Automation and Predictive Analytics
Artificial intelligence and predictive analytics are reshaping ERP functionality in the construction sector. These technologies enable automated scheduling, risk detection, and resource optimization. Predictive models help identify cost overruns and material shortages before they occur, improving project outcomes. The increasing use of AI-powered modules is creating opportunities for vendors to offer smarter, self-learning ERP platforms tailored for construction operations.
- For instance, According to an analysis by Deloitte, AI can reduce budget and timeline deviations by 10–20% in the construction industry, a finding often referenced in the context of companies like Autodesk
Growing Demand for Mobile ERP Applications
The expansion of mobile ERP applications is enabling on-site teams to access data and update project details in real time. Mobile tools improve coordination, reduce manual paperwork, and accelerate approval workflows. As construction sites become more digital, the demand for mobile-friendly ERP interfaces continues to grow. This trend offers vendors opportunities to develop intuitive, cross-platform mobile solutions for field operations.
Key Challenges
High Implementation and Maintenance Costs
The initial investment for ERP implementation remains a key barrier for many construction firms. Costs related to customization, training, and system integration can strain smaller enterprises with limited budgets. Ongoing expenses for upgrades and technical support further add to the financial burden. These factors often delay adoption or limit the scope of ERP deployment in cost-sensitive construction businesses.
Data Security and Integration Concerns
The growing use of cloud and mobile ERP platforms raises concerns about data privacy and cybersecurity. Construction projects involve sensitive financial and contractual data that require strict protection. Poor integration between ERP systems and existing project management tools can also lead to data inconsistencies. Addressing these security and compatibility challenges is crucial to ensuring broader ERP adoption across the industry.
Regional Analysis
North America The North America market held approximately 38% share of the global construction ERP software market in 2024. The region leads due to strong infrastructure investment, high digital maturity among contractors, and the presence of major ERP software vendors headquartered in the U.S. Contractors increasingly adopt ERP systems to manage complex multi-site operations and control costs. The large enterprise segment drives demand as firms integrate project, procurement and financial modules within unified platforms across multiple geographies.
Europe
Europe accounted for about 25% of the market in 2024. Growth is supported by rising adoption of cloud-based solutions among construction firms in Western Europe and regulatory focus on transparency and efficiency in public-works contracts. Increasing retrofit and infrastructure upgrades in countries such as Germany and the UK boost demand for ERP systems tailored to resource-intensive projects. Local vendors and region-specific compliance capabilities further strengthen market uptake.
Asia-Pacific
The Asia-Pacific region captured around 22% share in 2024 and is projected as the fastest-growing region going forward. Rapid urbanisation, large government infrastructure programmes in China and India, and increasing digitalisation of the construction industry drive ERP adoption. Cloud deployment is particularly favoured in emerging markets due to cost flexibility and field mobility. As SMEs increasingly invest in ERP systems, the region’s share is expected to expand significantly.
Middle East & Africa
Middle East & Africa held roughly 8% of the market in 2024. The region benefits from major infrastructure projects in key Gulf states and rising demand for project transparency and resource optimisation. However, growth is moderated by lower overall construction IT spend and slower adoption in some parts of Africa. Country-specific regulatory and connectivity challenges create pockets of opportunity for specialised ERP vendors.
Latin America
Latin America contributed about 7% share in 2024. The region’s market growth is driven by infrastructure modernization efforts, especially in Brazil and Mexico, and increasing interest in ERP systems among medium-sized construction firms. Limited market maturity and economic volatility present adoption challenges, yet cloud-based and modular ERP offerings offer scalable entry points for local contractors and project-focused construction businesses.
Market Segmentations:
By Solution
- Software
- Services
By Deployment
- On-premise
- Cloud based
By Enterprise Size
- SME
- Large Enterprises
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The construction ERP software market features major players such as Oracle, Procore Technologies, SAP, Microsoft, CMiC Global Inc, Autodesk, In4Velocity Systems, Deltek, Sage Group, and Viewpoint. The competitive landscape is defined by continuous innovation, strategic partnerships, and product differentiation focused on project efficiency and real-time data management. Companies are enhancing their ERP platforms with AI, analytics, and mobile integration to support on-site operations and decision-making. Cloud-based deployment remains a central competitive advantage, offering flexibility and scalability to diverse construction firms. Vendors are increasingly targeting small and medium enterprises through subscription-based models and modular software designs. Continuous investment in security, user experience, and interoperability strengthens their positioning in a rapidly evolving digital construction environment. As global infrastructure development intensifies, competition is expected to deepen, driving innovation in automation, predictive analytics, and connected ecosystem solutions for end-to-end project lifecycle management.
Key Player Analysis
- Oracle
- Procore Technologies
- SAP
- Microsoft
- CMiC Global Inc
- Autodesk
- In4Velocity Systems
- Deltek
- Sage Group
- Viewpoint
Recent Developments
- In 2025, In4Velocity Systems enhanced its existing In4Suite® ERP platform by integrating artificial intelligence capabilities.
- In 2023, Procore Technologies Inc. Launched Procore Pay, a new service integrated within its construction project management platform.
- In 2023, CMiC Global Inc Formed a strategic partnership with Arcoro, a provider of cloud-based human resources and workforce management solutions for the construction industry.
Report Coverage
The research report offers an in-depth analysis based on Solution, Deployment, Enterprise Size and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The construction ERP software market will witness steady expansion driven by digital transformation in construction.
- Cloud-based ERP adoption will continue to rise as firms prioritize scalability and flexibility.
- Integration of AI and machine learning will enhance predictive analytics and project forecasting.
- Mobile ERP applications will gain traction to support real-time field operations and updates.
- Growing demand for data-driven project management will boost adoption among mid-sized contractors.
- Vendors will focus on modular and customizable ERP solutions for diverse construction workflows.
- Government infrastructure programs will create sustained demand for centralized project management tools.
- Partnerships between ERP providers and construction technology firms will strengthen innovation pipelines.
- Cybersecurity and data protection features will become key differentiators for software vendors.
- The Asia-Pacific region will emerge as the fastest-growing market due to rapid construction digitalization.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Construction ERP Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Construction ERP Software Market projected to grow between 2025 and 2032?
Which Construction ERP Software Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Construction ERP Software Market?
Who are the leading companies in the Construction ERP Software Market?
Which region commanded the largest share of the Construction ERP Software Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,364 million → 2032: USD 6,000 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Construction ERP Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Construction ERP Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Construction ERP Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Construction ERP Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Construction ERP Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Construction ERP Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Construction ERP Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Construction ERP Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,364 million → 2032: USD 6,000 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Construction ERP Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Construction ERP Software Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Construction ERP Software Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Construction ERP Software Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

