
Market Overview:
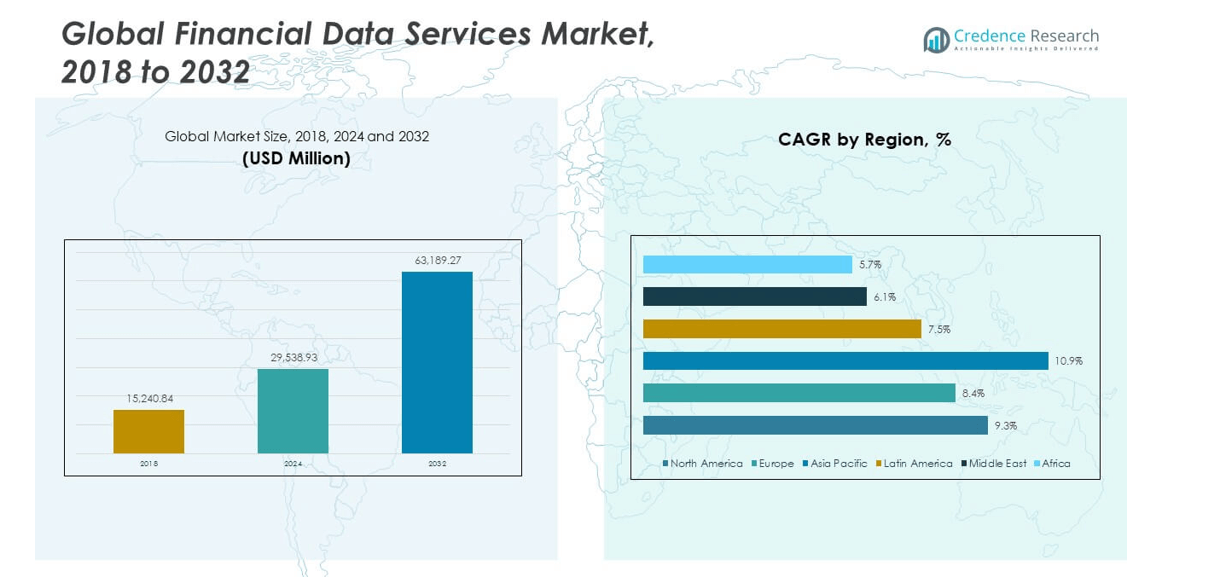
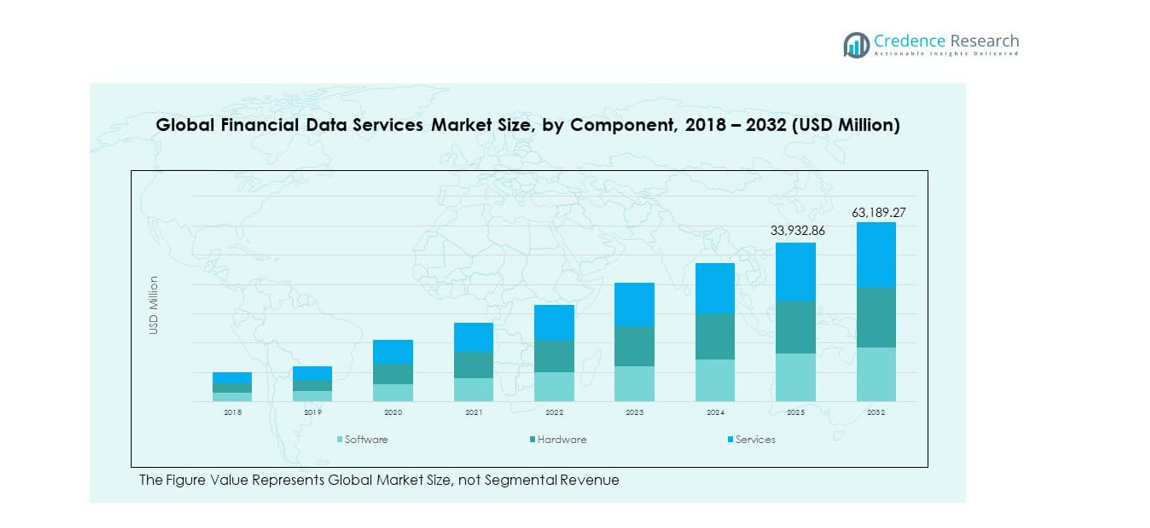
The Global Financial Data Services Market size was valued at USD 15,240.84 million in 2018 to USD 29,538.93 million in 2024 and is anticipated to reach USD 63,189.27 million by 2032, at a CAGR of 9.29% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Financial Data Services Market Size 2024 | USD 29,538.93 million |
| Financial Data Services Market, CAGR | 9.29% |
| Financial Data Services Market Size 2032 | USD 63,189.27 million |
The market is driven by increasing digital transformation in financial institutions and growing adoption of data-driven decision-making tools. Rising demand for real-time analytics, risk management systems, and regulatory compliance solutions is enhancing the value of financial data platforms. The integration of AI, machine learning, and blockchain further strengthens predictive analytics, enabling organizations to improve transparency, efficiency, and strategic planning in capital markets.
North America holds a dominant position due to its strong financial infrastructure and early adoption of advanced data technologies. Europe follows closely with growing regulatory compliance needs and fintech collaborations. Meanwhile, Asia-Pacific is emerging rapidly, driven by expanding digital banking, increasing investments in fintech startups, and rising demand for financial inclusion in developing economies such as India and Southeast Asian countries.
Market Insights:
- The Global Financial Data Services Market was valued at USD 15,240.84 million in 2018, reached USD 29,538.93 million in 2024, and is projected to attain USD 63,189.27 million by 2032, growing at a CAGR of 9.29%.
- North America led with a 44.3% share in 2024, driven by its advanced financial infrastructure and early adoption of AI-based analytics. Europe followed with 26.5% owing to strong regulatory frameworks and digital banking growth. Asia Pacific held 23.7%, supported by rising fintech adoption and digital investments.
- Asia Pacific is the fastest-growing region, expanding rapidly due to urbanization, government-backed fintech programs, and the surge in digital transactions across China, India, and Southeast Asia.
- The software segment dominated with around 55% share, fueled by demand for analytics platforms and compliance management tools across institutions.
- Services accounted for approximately 30% share, reflecting growth in integration, maintenance, and consulting support that enhance system reliability and efficiency.
Market Drivers:
Rising Demand for Data-Driven Decision Making in Financial Institutions
The Global Financial Data Services Market is expanding due to increasing reliance on real-time analytics by banks, insurance firms, and investment companies. Institutions are integrating advanced data tools to forecast trends, assess risk, and optimize portfolios. The growing complexity of financial transactions has created a strong need for accurate and timely insights. It is helping organizations improve operational efficiency while ensuring compliance with changing regulations. Data-driven strategies enable improved product development and customer personalization. Rising competition in capital markets has accelerated adoption of predictive analytics. Firms are using data to identify market gaps and improve profit margins.
- For instance, JPMorgan Chase’s Athena platform supports over 4,000 Python developers and runs billions of risk management calculations daily for its global investment bank. As of 2022, the platform used over 50 million lines of Python code and executed more than 10,000 batch jobs daily.
Integration of Artificial Intelligence and Machine Learning in Financial Platforms
AI and ML integration is transforming financial data processing, enabling automation and improved accuracy in reporting and forecasting. It is streamlining credit scoring, fraud detection, and asset management processes. Financial institutions use AI-driven models to gain insights from large datasets and reduce decision errors. Machine learning algorithms enhance pattern recognition, allowing firms to react faster to market fluctuations. These technologies support advanced customer analytics and efficient back-office operations. The use of automation minimizes manual errors and lowers operational costs. Enhanced data visualization tools are also improving the accessibility of insights across departments. The expansion of intelligent financial solutions continues to drive innovation and adoption rates.
- For instance, Mastercard's Decision Intelligence Pro model, utilizing generative AI, allows banks to achieve an average of 20% improvement in fraud detection rates, with potential improvements of up to 300% in some instances. The system is designed to process transactions in under 50 milliseconds, analyzing over one trillion data points in real-time to prevent fraud.
Growing Need for Regulatory Compliance and Risk Management Solutions
Financial institutions face increasing regulatory scrutiny across jurisdictions, driving demand for advanced compliance and risk management tools. The Global Financial Data Services Market benefits from solutions that automate regulatory reporting and monitor cross-border transactions. Financial data systems enhance audit accuracy and support anti-money laundering frameworks. Risk analytics platforms assist firms in identifying potential exposure and managing capital reserves effectively. It is enabling institutions to comply with complex standards while minimizing penalties. The shift toward proactive compliance has increased investments in secure data infrastructure. Firms are focusing on integrating compliance intelligence into core operations. This trend ensures transparency and trust among regulators and clients.
Digital Transformation and Expansion of Fintech Ecosystems Worldwide
Digitalization across the financial sector is reshaping service delivery models and promoting innovation in data analytics. Fintech platforms are accelerating financial inclusion by offering digital lending, payment, and investment solutions. The Global Financial Data Services Market benefits from partnerships between traditional banks and fintech startups that use open banking and API frameworks. It is expanding data sharing while enhancing operational flexibility. Cloud-based systems allow secure storage and faster processing of large financial datasets. The rise of mobile banking and digital trading platforms supports broader adoption of data services. Continuous innovation in fintech ecosystems ensures improved transparency, scalability, and user experience across the financial value chain.
Market Trends:
Expansion of Cloud-Based Financial Data Infrastructure Across Enterprises
The Global Financial Data Services Market is witnessing rapid cloud adoption, enabling institutions to enhance scalability and reduce IT overheads. Cloud platforms support efficient data integration, high-speed processing, and secure sharing across departments. It is improving agility in responding to fluctuating market conditions. Cloud deployment models such as hybrid and multi-cloud are offering flexibility to manage sensitive data. Financial firms benefit from improved system uptime and disaster recovery capabilities. Vendors are investing in cybersecurity and encryption tools to protect sensitive financial records. The shift toward cloud-native architectures aligns with modernization goals. This trend continues to reshape enterprise financial data management.
- For instance, Goldman Sachs partnered with AWS to launch the Financial Cloud for Data, providing institutional clients access to scalable, real-time analytics for hundreds of assets in the cloud and integrating time-series financial data with Amazon FinSpace for rapid, secure analysis.
Emergence of Real-Time Data Analytics and Predictive Intelligence Tools
Real-time analytics is becoming a key differentiator among financial institutions seeking faster decision cycles. The Global Financial Data Services Market is driven by predictive intelligence that provides actionable insights into asset performance, market volatility, and client behavior. It enables instant analysis of large financial transactions and market shifts. The adoption of advanced analytics tools improves portfolio optimization and investment forecasting accuracy. Predictive data models also strengthen fraud prevention and credit risk evaluation. Companies are embedding analytics engines into trading systems to improve decision transparency. The move toward real-time intelligence enhances competitiveness and supports faster, more informed decisions.
- For instance, Citigroup leverages Palantir’s AI-powered platform to streamline wealth and trading operations, reducing case processing time by 90%-from several days to just seconds-thanks to unified analytics across formerly disparate data systems.
Growing Role of Open Banking and API Integration in Data Ecosystems
Open banking is transforming how data flows between institutions, regulators, and third-party service providers. The Global Financial Data Services Market is benefiting from standardized APIs that facilitate secure, permission-based data sharing. It promotes innovation in digital payment systems, wealth management platforms, and financial advisory services. The use of open APIs fosters collaboration between banks and fintech companies. This interconnected system increases competition while improving consumer choice. Regulatory frameworks in Europe and Asia-Pacific are supporting the adoption of open data models. Enhanced interoperability between financial systems boosts transparency and user empowerment. These integrations are laying the foundation for data-driven financial ecosystems.
Adoption of Blockchain and Distributed Ledger Technologies for Data Integrity
Blockchain technology is increasingly being used to secure financial data and transactions. The Global Financial Data Services Market leverages distributed ledgers to ensure transparency and traceability in trade settlements. It enhances data security, reduces fraud, and eliminates intermediaries in complex financial processes. Smart contracts streamline record-keeping and compliance monitoring. Decentralized systems provide tamper-proof data verification for audits and cross-border settlements. Financial firms are adopting blockchain for identity management and asset tokenization. This innovation reduces operational risks while improving data reliability. The growing use of blockchain reinforces trust across the financial ecosystem.
Market Challenges Analysis:
Complex Regulatory Landscape and Data Privacy Concerns Across Jurisdictions
The Global Financial Data Services Market faces challenges from differing regional regulations that complicate compliance efforts. Financial institutions must adhere to multiple frameworks such as GDPR, PSD2, and Basel III, increasing administrative burdens. It requires constant updates to systems and policies to ensure data integrity. Data localization laws also limit cross-border data exchange, affecting efficiency. Firms struggle to balance transparency with client privacy obligations. The cost of compliance continues to rise due to ongoing audit and monitoring needs. Unauthorized access or data breaches can lead to financial penalties and loss of trust. Maintaining consistent compliance across borders remains a key challenge.
Integration Barriers and Legacy Infrastructure Limit Digital Transformation
Many institutions continue to rely on outdated systems that hinder data modernization and interoperability. The Global Financial Data Services Market is challenged by legacy platforms that lack compatibility with new technologies. It causes delays in automation and increases operational costs. Migrating to digital frameworks involves high investment and skill gaps among employees. Fragmented data architectures limit real-time analytics and decision accuracy. Organizations struggle to unify multiple data sources into centralized platforms. Inconsistent system performance also affects scalability. Overcoming integration challenges is essential for ensuring long-term technological progress and market competitiveness.
Market Opportunities:
Expansion of Financial Data-as-a-Service (FDaaS) Platforms for Enterprises
The Global Financial Data Services Market is gaining traction from the rise of FDaaS models that provide on-demand access to real-time financial data. It allows institutions to reduce infrastructure costs while enhancing analytics capability. Businesses can subscribe to modular data packages based on needs such as risk management, investment analysis, or compliance reporting. The scalability of these platforms supports both large enterprises and SMEs. Cloud-native architecture ensures faster deployment and flexible integration with internal systems. Growing preference for API-enabled data access is opening new revenue streams for service providers.
Rising Demand for ESG and Sustainable Finance Data Analytics Solutions
Environmental, social, and governance (ESG) analytics are becoming a major growth avenue for data service providers. The Global Financial Data Services Market benefits from the rising demand for sustainability reporting and ethical investment analysis. It encourages firms to integrate ESG metrics into portfolio evaluation and risk assessments. Financial institutions require transparent and verified data for regulatory filings and investor communication. AI-driven tools are supporting ESG data aggregation and scoring accuracy. Growing awareness of climate risks and responsible finance practices is expanding market potential across developed and emerging economies.
Market Segmentation Analysis:
By Component
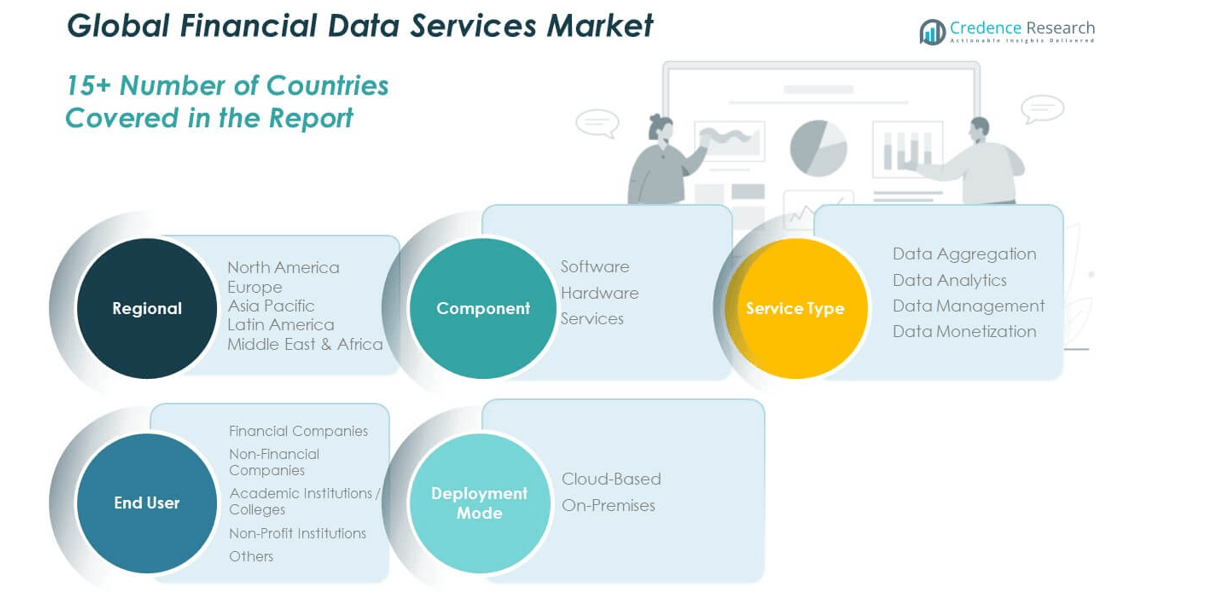
The Global Financial Data Services Market is segmented into software, hardware, and services. Software holds the dominant share, driven by increasing use of analytics platforms, risk management tools, and trading applications. It supports automation, data integration, and regulatory compliance functions across financial institutions. Hardware forms the backbone for data centers, storage, and high-speed computing infrastructure. Services such as consulting, maintenance, and system integration enhance operational efficiency and ensure seamless deployment. It continues to evolve with advancements in AI, cloud infrastructure, and cybersecurity technologies.
- For instance, IBM Cloud Pak for Data provides automated model governance and monitoring solutions, supporting scalable workflow automation and model tracking with integrated document and metric management for banks and financial organizations worldwide.
By Service Type
Key service segments include data aggregation, data analytics, data management, and data monetization. Data aggregation enables unified access to diverse financial datasets for improved decision-making. Data analytics is expanding rapidly, supporting investment forecasting and fraud detection. Data management ensures secure storage and regulatory compliance. Data monetization helps institutions generate revenue from proprietary insights. It plays a vital role in strengthening strategic and revenue-oriented decision frameworks.
- For instance, Refinitiv Tick History is a cloud-based financial data repository that maintains more than 20 petabytes of market data, enabling banks and asset managers to access full-depth, nanosecond-timestamped trading information for comprehensive analytics and portfolio management.
By End User
End users include financial companies, non-financial organizations, academic institutions, non-profits, and others. Financial firms lead adoption due to their dependence on real-time data for trading, investment, and compliance. Non-financial enterprises use data tools for budgeting and forecasting. Academic and research institutions apply financial data for market modeling and trend studies. Non-profits leverage it for funding analysis and reporting transparency.
By Deployment Mode
Deployment modes include cloud-based and on-premises solutions. Cloud deployment dominates due to scalability, cost efficiency, and ease of integration. It supports remote access and faster implementation across organizations. On-premises models remain preferred for firms with strict data security or regulatory needs. The shift toward hybrid models continues to redefine operational agility and flexibility in financial data ecosystems.
Segmentation:
- By Component
- Software
- Hardware
- Services
- By Service Type
- Data Aggregation
- Data Analytics
- Data Management
- Data Monetization
- By End User
- Financial Companies
- Non-Financial Companies
- Academic Institutions / Colleges
- Non-Profit Institutions
- Others
- By Deployment Mode
- Cloud-Based
- On-Premises
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
The North America Global Financial Data Services Market size was valued at USD 6,817.91 million in 2018 to USD 13,080.13 million in 2024 and is anticipated to reach USD 28,056.67 million by 2032, at a CAGR of 9.3% during the forecast period. North America holds the largest regional market share of around 44.3%. The region benefits from a mature financial ecosystem, strong regulatory infrastructure, and high adoption of advanced data analytics tools. It is supported by the presence of major financial institutions and leading technology providers in the U.S. and Canada. Financial organizations are investing heavily in AI-driven analytics, cloud platforms, and blockchain solutions to enhance operational efficiency. The demand for regulatory compliance and risk management systems is also fueling growth. Cross-sector collaboration between fintech firms and traditional banks continues to strengthen innovation. Rising cybersecurity investments and digital transformation across enterprises are reshaping the region’s financial data landscape.
Europe
The Europe Global Financial Data Services Market size was valued at USD 4,193.11 million in 2018 to USD 7,824.75 million in 2024 and is anticipated to reach USD 15,727.56 million by 2032, at a CAGR of 8.4% during the forecast period. Europe represents about 26.5% of the global market share. The region’s growth is driven by strong regulatory frameworks such as GDPR and PSD2, which promote transparency and data protection. It is supported by increasing adoption of open banking initiatives across the UK, Germany, and France. Financial institutions are leveraging data analytics to improve compliance and enhance customer experience. The rise of fintech hubs and digital banking models further supports market expansion. European firms are investing in scalable cloud infrastructures to handle complex financial data systems. Integration of ESG analytics and sustainable finance data platforms is also gaining importance. The focus on cross-border financial integration and digital innovation continues to accelerate the region’s growth.
Asia Pacific
The Asia Pacific Global Financial Data Services Market size was valued at USD 3,022.95 million in 2018 to USD 6,335.53 million in 2024 and is anticipated to reach USD 15,299.42 million by 2032, at a CAGR of 10.9% during the forecast period. Asia Pacific accounts for about 23.7% of the total market share and is the fastest-growing region. Expanding digital banking adoption and fintech innovation across China, India, Japan, and Southeast Asia are driving growth. It is supported by rapid urbanization, rising disposable income, and government initiatives promoting digital finance. Financial institutions are implementing AI, big data, and cloud computing to modernize operations. The growing investor base in emerging economies is increasing demand for reliable financial data platforms. Cross-border payment systems and regional partnerships enhance financial accessibility. The proliferation of mobile applications and digital wallets is transforming how users interact with financial services.
Latin America
The Latin America Global Financial Data Services Market size was valued at USD 679.13 million in 2018 to USD 1,298.91 million in 2024 and is anticipated to reach USD 2,439.91 million by 2032, at a CAGR of 7.5% during the forecast period. Latin America represents nearly 3.8% of the global market share. The region’s market growth is fueled by rising demand for financial inclusion and expanding fintech ecosystems. Countries such as Brazil and Mexico are leading digital transformation through regulatory reforms and innovation programs. It is supported by increased adoption of cloud-based financial platforms and mobile banking applications. The need for transparent credit and payment data drives the adoption of financial data solutions. Investments from global players are improving infrastructure and accessibility across local markets. The region faces challenges from economic fluctuations but continues to offer high potential for digital finance expansion.
Middle East
The Middle East Global Financial Data Services Market size was valued at USD 325.32 million in 2018 to USD 559.42 million in 2024 and is anticipated to reach USD 943.95 million by 2032, at a CAGR of 6.1% during the forecast period. The region holds approximately 1.5% of the global market share. Growth is driven by the modernization of banking infrastructure and increasing adoption of fintech across GCC countries. It is supported by government-led initiatives promoting cashless economies and digital identity systems. Financial institutions are integrating AI-based data solutions for compliance and investment tracking. The UAE and Saudi Arabia are key hubs for fintech innovation and regional data services expansion. The emergence of regulatory sandboxes and cross-border collaboration is boosting digital finance. Rising investments in cybersecurity and cloud migration are shaping the market’s evolution.
Africa
The Africa Global Financial Data Services Market size was valued at USD 202.41 million in 2018 to USD 440.19 million in 2024 and is anticipated to reach USD 721.75 million by 2032, at a CAGR of 5.7% during the forecast period. Africa accounts for nearly 1.2% of the global market share. The region’s growth is supported by expanding mobile banking adoption and financial inclusion initiatives. It is witnessing a steady increase in fintech startups, particularly in Nigeria, Kenya, and South Africa. Financial data platforms are helping streamline transactions, improve credit scoring, and support micro-lending programs. Infrastructure development and government support are creating a favorable environment for digital transformation. The market remains fragmented but shows strong potential in digital payment services. Increasing cloud-based deployments and affordable data solutions are expected to improve accessibility and growth across the continent.
Key Player Analysis:
- Bloomberg L.P.
- Thomson Reuters (Refinitiv)
- FactSet Research Systems, Inc.
- S&P Global Inc.
- Morningstar, Inc.
- IHS Markit (now part of S&P Global)
- ICE Data Services
- Moody’s Analytics
- Dow Jones (News Corp)
- MSCI Inc.
Competitive Analysis:
The Global Financial Data Services Market is highly competitive, characterized by a mix of global leaders and emerging technology providers. Major players such as Bloomberg L.P., Thomson Reuters, S&P Global, FactSet, and Morningstar dominate through advanced data platforms and analytics capabilities. It emphasizes innovation, product expansion, and AI integration to strengthen financial intelligence and decision-making accuracy. Mergers and partnerships are frequent as companies aim to expand market presence and diversify data portfolios. Continuous focus on cloud-based solutions, automation, and compliance-driven analytics sustains competition across institutional and corporate clients.
Recent Developments:
- In July 2025, Bloomberg announced a noteworthy strategic partnership with Clearwater Analytics to offer a front-to-back investment solution for asset owners and asset managers. This alliance is set to transform investment management workflows by integrating Clearwater’s accounting solutions with Bloomberg’s enterprise investment workflows, giving clients a scalable and comprehensive operational model.
- In September 2025, Thomson Reuters acquired Additive, an AI-powered specialist in tax document processing. This acquisition aims to bolster Thomson Reuters’ suite of AI-driven automation offerings, particularly in the complex arena of tax document handling, and marks a notable push toward leveraging artificial intelligence within professional services.
- In September 2025, FactSet entered a major partnership with Hebbia, an AI-driven platform for finance, through FactSet’s AI Partner Program. This collaboration brings FactSet’s trusted financial data and analytics directly into Hebbia’s AI-powered workflows, enhancing the ability of investment professionals to synthesize and analyze structured and unstructured data in real time.
Report Coverage:
The research report offers an in-depth analysis based on component, service type, end user, and deployment mode. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased integration of AI and predictive analytics in financial decision-making.
- Rising demand for ESG and sustainability-focused financial data platforms.
- Expansion of real-time data delivery across multi-cloud environments.
- Stronger partnerships between fintech firms and traditional institutions.
- Growth in open banking and API-based data sharing frameworks.
- Continued investment in cybersecurity and data privacy technologies.
- Enhanced role of blockchain for transaction verification and compliance.
- Broader financial inclusion through data-driven credit evaluation tools.
- Emergence of regional fintech hubs accelerating market competition.
- Continuous innovation in data monetization models and digital finance solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Financial Data Services Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Financial Data Services Market projected to grow between 2025 and 2032?
Which Global Financial Data Services Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Financial Data Services Market?
Who are the leading companies in the Global Financial Data Services Market?
Which region commanded the largest share of the Global Financial Data Services Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 15,240.84 million → 2032: USD 63,189.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Financial Data Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Financial Data Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Financial Data Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Financial Data Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Financial Data Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Financial Data Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Financial Data Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Financial Data Services Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 15,240.84 million → 2032: USD 63,189.27 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Financial Data Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Financial Data Services Geographic Market Outlook, 2018-2032
- 13.1 Regional Market Size and Share, 2018
- 13.2 Regional Market Forecast, 2018-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Financial Data Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2018-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Financial Data Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

