
Market Overview:
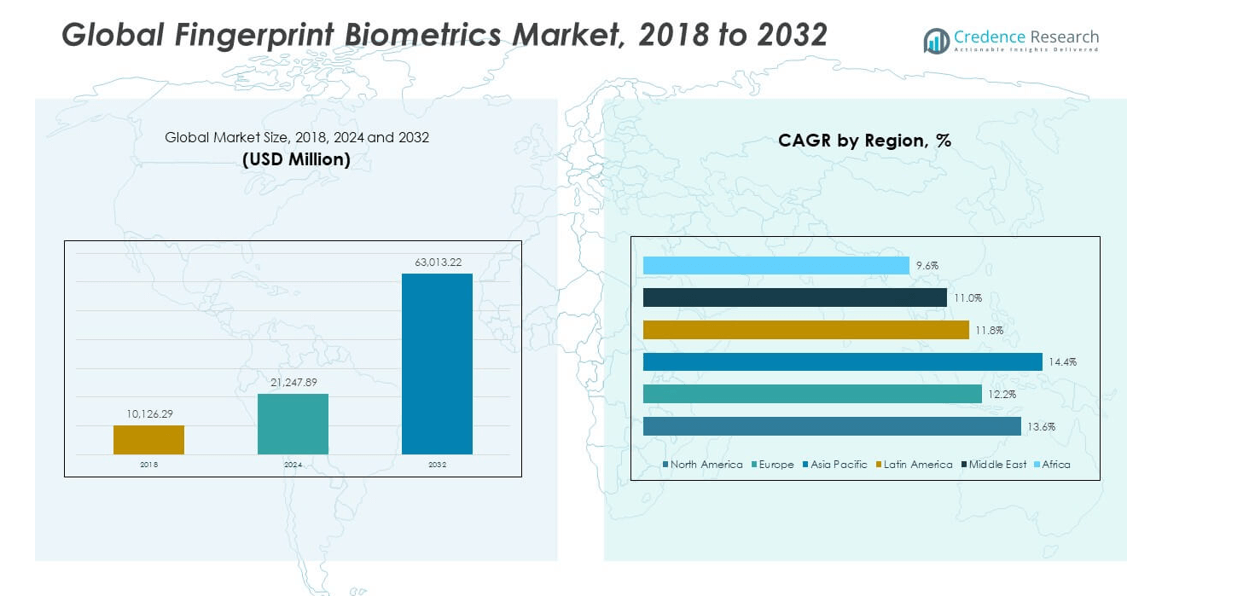
The Global Fingerprint Biometrics Market size was valued at USD 10,126.29 million in 2018, reaching USD 21,247.89 million in 2024, and is anticipated to attain USD 63,013.22 million by 2032, at a CAGR of 13.57% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fingerprint Biometrics Market Size 2024 | USD 21,247.89 million |
| Fingerprint Biometrics Market, CAGR | 13.57% |
| Fingerprint Biometrics Market Size 2032 | USD 63,013.22 million |
Market growth is driven by increasing demand for secure authentication systems across banking, government, and consumer electronics sectors. The expansion of contactless biometric solutions, rising identity theft concerns, and adoption in smartphones, smart cards, and IoT devices further accelerate market development. Additionally, advancements in sensor technology and integration with AI enhance accuracy, reliability, and speed, supporting widespread deployment in both public and private sectors.
North America leads the global market, supported by advanced security infrastructure and widespread adoption in financial and governmental applications. Europe follows, driven by strict data protection regulations and growing demand for secure digital transactions. Asia-Pacific is emerging as the fastest-growing region, fueled by expanding smartphone usage, national ID programs, and investments in biometric access control systems across China, India, and Southeast Asia.
Market Insights:
- The Global Fingerprint Biometrics Market was valued at USD 10,126.29 million in 2018, reached USD 21,247.89 million in 2024, and is projected to hit USD 63,013.22 million by 2032, expanding at a CAGR of 13.57% during the forecast period.
- Asia Pacific leads the market with around 46% share, driven by large-scale government ID programs, strong manufacturing capabilities, and widespread biometric integration in consumer electronics. North America follows with 28%, supported by early adoption across government and defense sectors, while Europe holds about 17%, led by strict data protection regulations and robust fintech adoption.
- Asia Pacific is also the fastest-growing region, propelled by smart city investments, national identity initiatives, and rising smartphone penetration across China, India, and Japan.
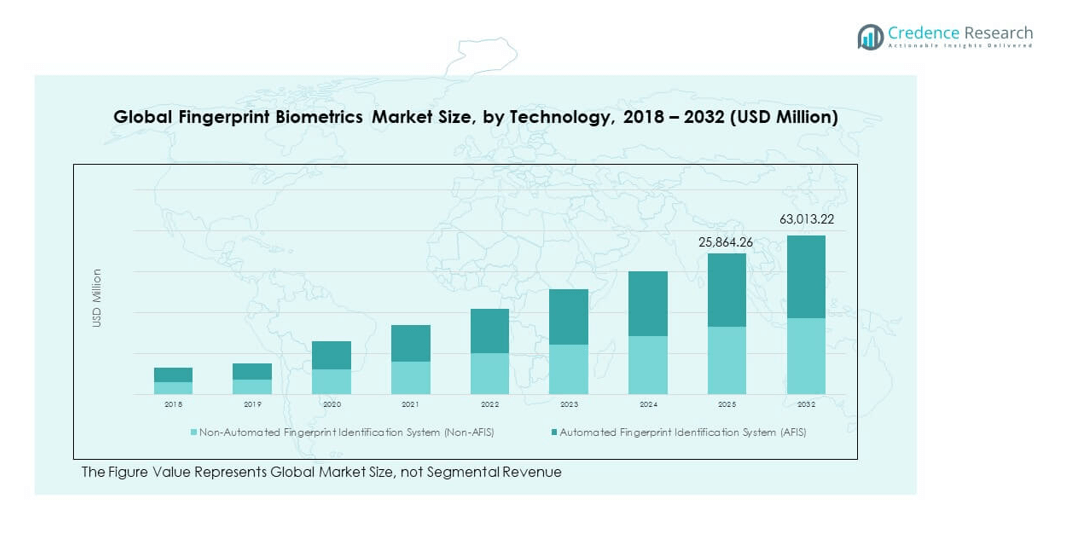
- By technology, Automated Fingerprint Identification Systems (AFIS) dominate with nearly 70% share, supported by their scalability and accuracy in high-security applications.
- Non-Automated Fingerprint Identification Systems (Non-AFIS) account for around 30%, serving smaller-scale installations such as office attendance and basic access control systems.
Market Drivers:
Growing Integration of Biometrics in Consumer Electronics
The Global Fingerprint Biometrics Market benefits from increasing adoption across smartphones, laptops, and smart wearables. Major electronics brands embed sensors in devices to enhance authentication security and ease of access. The surge in mobile payment platforms and e-banking drives reliance on biometric verification. It allows faster and more secure transactions compared to traditional PINs or passwords. Fingerprint technology offers user convenience while reducing fraud risk. Manufacturers continue developing compact and accurate sensors. This integration has become a standard feature in mid and high-end consumer devices, strengthening overall demand.
- For instance, the Samsung Galaxy S24 series features Qualcomm’s 3D Sonic Sensor Gen 2 with the BioSign 6.0 algorithm, recognized for notably enhanced fingerprint authentication speed and upgraded accuracy, as confirmed by Suprema Inc. in March 2024.
Rising Government Initiatives and Identity Verification Programs
Governments worldwide deploy fingerprint biometrics for e-passports, national ID systems, and border control applications. These initiatives promote accurate citizen identification and strengthen public security frameworks. It supports large-scale data management through advanced biometric databases. The technology ensures identity reliability, reducing forgery and impersonation incidents. Law enforcement agencies use fingerprint-based solutions for criminal identification and access monitoring. Countries in Asia and Africa are implementing national biometric registration programs. Such projects generate massive installation demand for scanners and software. The expansion of e-governance services enhances the market scope for fingerprint-based solutions.
- For instance, India’s Aadhaar program exceeded 1.4 billion biometric registrations in early 2025, as reported in TechCrunch and Biometric Update, while Nigeria’s National Identity Management Commission launched the NINAuth platform for secure real-time fingerprint authentication tied to its national database serving over 120 million enrollees as of early 2025.
Expansion in Financial and Banking Security Applications
The financial sector increasingly adopts fingerprint biometrics to safeguard sensitive transactions. Banks deploy fingerprint-enabled ATMs and mobile authentication systems to counter cyber threats. It ensures secure customer onboarding and reduces risks linked to password breaches. Fintech firms incorporate biometric verification for digital lending and e-wallet access. The shift toward biometric payment authentication strengthens security and user confidence. High penetration of digital banking in emerging economies accelerates adoption. Financial institutions value fingerprint solutions for accuracy and low maintenance. Growing compliance requirements and anti-fraud measures further support this segment’s expansion.
Advancements in Sensor Technology and AI-Driven Accuracy
Advances in sensor miniaturization and image processing significantly improve fingerprint recognition systems. The integration of AI enhances identification precision under varied environmental conditions. It enables faster recognition with reduced false acceptance rates. Manufacturers develop flexible, under-display, and optical sensors for compact devices. Machine learning algorithms enhance adaptive authentication and spoof detection. These improvements broaden use in healthcare, retail, and enterprise security. Vendors invest in multi-modal systems combining fingerprint with facial or iris recognition. Continuous innovation ensures scalable and energy-efficient solutions suitable for diverse end-use applications.
Market Trends:
Adoption of Contactless and Touchless Biometric Technologies
The Global Fingerprint Biometrics Market is witnessing a shift toward contactless solutions. Health concerns and hygiene awareness post-pandemic have increased demand for non-contact systems. Touchless sensors capture high-resolution images without physical contact, ensuring convenience and safety. It supports deployment in airports, offices, and healthcare facilities. Manufacturers design touchless modules compatible with existing infrastructure. Enterprises integrate these systems to meet health regulations and reduce contamination risks. Governments also prefer such systems for secure and hygienic identification. The transition to touchless fingerprint technology reshapes future market preferences.
- For instance, IDEMIA’s MorphoWave SP contactless terminal scans and verifies up to four fingerprints in less than one second and supports up to 10,000 user profiles-an achievement specifically cited by the manufacturer and featured in deployment guides and product brochures. NEC’s "Face Express" system at Narita International Airport uses facial biometrics for zero-touch passenger boarding and security, delivering improved checkpoint speed and safety per NEC’s April 2021 press release.
Integration of Fingerprint Biometrics with IoT and Smart Infrastructure
The growing Internet of Things ecosystem drives integration of biometric authentication into connected devices. It enhances access control and user verification in smart homes, vehicles, and industrial systems. Fingerprint sensors embedded in IoT modules strengthen data security. It allows seamless connectivity between digital and physical environments. Smart city projects deploy biometrics for surveillance, entry systems, and civic services. Manufacturers collaborate with IoT developers to build compatible frameworks. The fusion of biometrics and IoT improves convenience without compromising privacy. This convergence supports scalable and secure identity management solutions globally.
Emergence of Cloud-Based Biometric Management Systems
Cloud integration is transforming how fingerprint data is stored and managed across enterprises. Centralized databases allow real-time access control and monitoring from multiple locations. It reduces hardware costs while enhancing system scalability. Cloud solutions support automatic software updates and security patches. It simplifies compliance for regulated sectors like healthcare and finance. Vendors offer subscription-based biometric software to improve accessibility for small businesses. The model promotes remote verification for distributed workforces. Cloud-enabled biometrics accelerate digital transformation across industries seeking efficient authentication frameworks.
Increased Focus on Multimodal Authentication Solutions
Organizations combine fingerprint biometrics with other identifiers to improve verification strength. Multimodal systems integrate facial, iris, or voice recognition for layered security. It mitigates vulnerabilities associated with single-mode authentication. This trend gains traction in airports, border security, and corporate environments. Integration ensures reliability in challenging conditions such as low lighting or partial prints. Companies develop unified platforms to process multiple biometric inputs efficiently. Adoption of AI enhances decision-making accuracy in these hybrid models. The trend reflects the growing preference for comprehensive, adaptable, and fraud-resistant identity solutions.
Market Challenges Analysis:
Data Privacy Concerns and Stringent Regulatory Compliance
The Global Fingerprint Biometrics Market faces scrutiny over data handling and user consent. Regulatory frameworks such as GDPR and CCPA impose strict rules on biometric data storage. It increases compliance costs and limits data transfer flexibility for global vendors. Breaches of fingerprint databases can lead to irreversible identity theft. Companies must ensure encryption, anonymization, and secure transmission of biometric information. The absence of unified international standards creates challenges for cross-border operations. Maintaining transparency and user trust remains complex for large-scale projects. Balancing innovation with privacy protection continues to challenge industry growth.
High Implementation Costs and System Integration Complexities
Fingerprint biometric systems require significant investment in hardware, software, and maintenance. Integration into legacy infrastructure poses technical difficulties for enterprises with outdated systems. It may involve reconfiguration of existing access control or IT frameworks. Small and medium businesses often hesitate due to upfront costs. Sensor calibration, environment adaptation, and interoperability issues delay deployments. Maintenance and training expenses further add to operational burden. Vendors face challenges in providing cost-effective yet high-quality solutions. Addressing affordability without compromising performance remains a priority for widespread adoption.
Market Opportunities:
Growing Adoption in Healthcare, Education, and Retail Sectors
The Global Fingerprint Biometrics Market is expanding beyond traditional security use. Hospitals deploy biometric systems for patient verification and staff attendance tracking. Educational institutions implement fingerprint access for exams and attendance management. Retail companies adopt biometric point-of-sale systems for quick and secure transactions. It enhances customer convenience and reduces fraud at checkout points. Rising demand for digital verification tools in emerging economies supports this diversification. Vendors offering customizable solutions for these industries gain long-term opportunities. Expansion into non-traditional sectors strengthens market penetration globally.
Emerging Use in Automotive and Transportation Security Systems
Automotive manufacturers integrate fingerprint sensors for driver identification and keyless vehicle entry. The technology improves personalization, allowing automatic seat and climate adjustments. It increases theft prevention through secure user recognition. Public transportation systems also deploy biometric ticketing and access control modules. It streamlines passenger management and strengthens security checks. Integration with AI enables predictive analysis for travel patterns and safety compliance. Vendors developing durable, vibration-resistant sensors for mobility solutions hold strong prospects. Expanding transportation digitization offers significant growth avenues for biometric technology providers.
Market Segmentation Analysis:
By Technology
The Global Fingerprint Biometrics Market is categorized into Non-Automated Fingerprint Identification Systems (Non-AFIS) and Automated Fingerprint Identification Systems (AFIS). Non-AFIS solutions are widely adopted in small-scale and low-security applications, offering basic matching capabilities suitable for attendance management and access control. AFIS dominates the segment due to its precision, speed, and scalability in high-security environments such as border control, law enforcement, and banking. It allows real-time identification through large databases and advanced image processing algorithms. Growing deployment in national identity programs and forensic systems further strengthens AFIS adoption.
- For instance, NEC’s AFIS platform powers large-scale live scan identification for law enforcement agencies, supporting millions of stored fingerprint records and high-speed matching as confirmed in official company materials. Thales Group’s Cogent AFIS system has been used for real-time forensic identification processing up to one million comparisons per second for national authorities according to product brochures and security guides.
By Offering
The market is segmented into hardware, software, and services. Hardware holds a major share, driven by strong demand for fingerprint scanners, sensors, and modules across mobile devices and security systems. Software plays a crucial role in enhancing data matching, template storage, and analytics functions, with growing integration of AI improving accuracy and speed. Services, including installation, maintenance, and cloud-based management, are expanding steadily with the shift toward managed biometric solutions. It continues to attract investment from enterprises seeking scalable and secure authentication frameworks. This diversified offering base supports sustained market expansion across multiple end-user industries.
- For instance, Bio-Key International's biometric-as-a-service platform, PortalGuard, leverages Microsoft Azure to provide Identity and Access Management (IAM) software for over 40 million users globally. HID Global's Lumidigm V-Series uses multispectral imaging technology and machine-learning algorithms for liveness detection and has been a reliable authentication solution for applications like ATMs and access control systems for several years.
Segmentation:
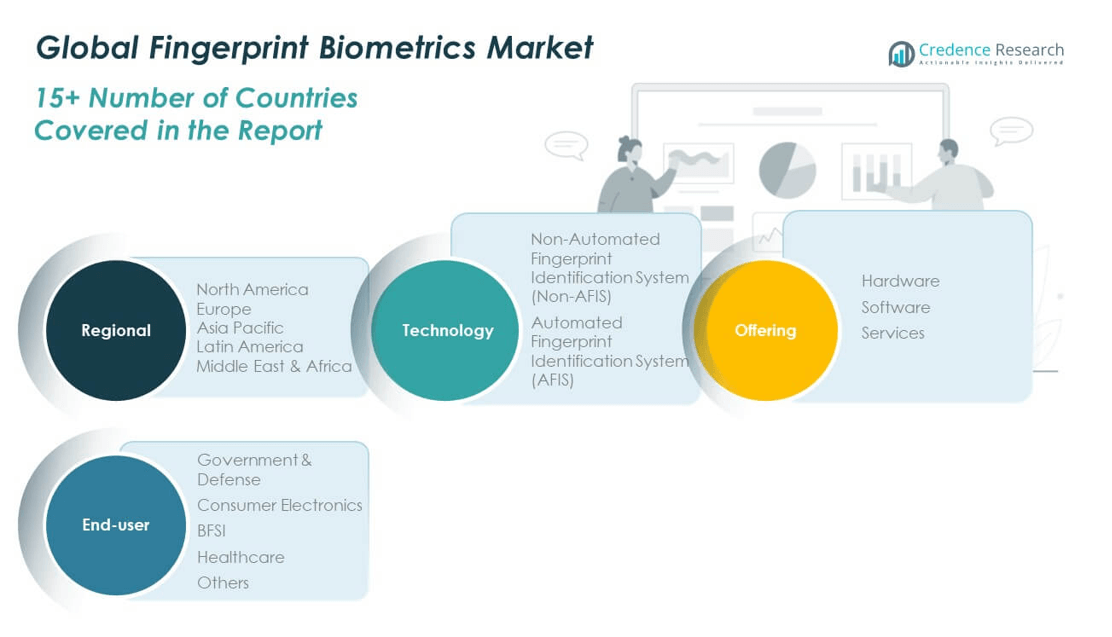
- By Technology:
- Non-Automated Fingerprint Identification System (Non-AFIS)
- Automated Fingerprint Identification System (AFIS)
- By Offering:
- Hardware
- Software
- Services
- By End-User:
- Government & Defense
- Consumer Electronics
- BFSI
- Healthcare
- Others
- By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
The North America Global Fingerprint Biometrics Market size was valued at USD 2,880.49 million in 2018, reached USD 5,947.73 million in 2024, and is anticipated to attain USD 17,714.34 million by 2032, at a CAGR of 13.6% during the forecast period. North America accounts for approximately 28% of the global market share. Strong adoption across government, defense, and corporate sectors drives regional growth. It benefits from early adoption of biometric identification in border security, law enforcement, and financial services. Widespread use in smartphones and enterprise authentication further supports expansion. The U.S. dominates the regional landscape with advanced R&D investments and digital identity initiatives. Canada focuses on integrating biometric systems into immigration and financial services. High awareness of data security and privacy compliance continues to foster steady market development.
Europe
The Europe Global Fingerprint Biometrics Market size was valued at USD 1,874.61 million in 2018, reached USD 3,716.17 million in 2024, and is anticipated to attain USD 10,012.55 million by 2032, at a CAGR of 12.2% during the forecast period. Europe holds around 17% of the global market share. It is driven by stringent regulatory standards such as GDPR and strong emphasis on secure identification frameworks. Governments across the UK, Germany, and France deploy biometric authentication in e-passports, border control, and national ID programs. The growing adoption in the BFSI sector for fraud prevention supports further expansion. Demand for biometric-based workplace access and digital verification solutions is rising. Vendors emphasize compliance-ready software and advanced encryption to meet regional security protocols. Europe’s mature technology ecosystem and cross-border security initiatives sustain consistent growth momentum.
Asia Pacific
The Asia Pacific Global Fingerprint Biometrics Market size was valued at USD 4,519.82 million in 2018, reached USD 9,826.72 million in 2024, and is anticipated to attain USD 30,884.04 million by 2032, at a CAGR of 14.4% during the forecast period. The region commands the largest share at nearly 46% of the global market. Expansion is supported by rapid digital transformation, large-scale government ID programs, and a surge in smartphone penetration. Countries like China, India, and Japan drive widespread integration across public security, banking, and healthcare. It benefits from strong manufacturing capabilities and cost-efficient biometric hardware production. Rising demand for contactless authentication post-pandemic accelerates deployment in airports and enterprises. Regional players collaborate with global firms to enhance product quality and reach. Continuous investment in smart city and fintech applications reinforces Asia Pacific’s dominant position.
Latin America
The Latin America Global Fingerprint Biometrics Market size was valued at USD 458.05 million in 2018, reached USD 948.65 million in 2024, and is anticipated to attain USD 2,475.59 million by 2032, at a CAGR of 11.8% during the forecast period. The region contributes approximately 4% of the global market share. Growth is supported by increasing adoption in border management, financial inclusion, and law enforcement programs. Brazil and Mexico lead with expanding use of fingerprint-based voter registration and social benefit verification systems. It benefits from growing deployment in public sector contracts and banking security. Local manufacturing and partnerships with global vendors improve product availability. Digital transformation initiatives in healthcare and retail further enhance adoption. Infrastructure modernization and supportive government policies sustain steady market penetration.
Middle East
The Middle East Global Fingerprint Biometrics Market size was valued at USD 265.65 million in 2018, reached USD 506.28 million in 2024, and is anticipated to attain USD 1,249.39 million by 2032, at a CAGR of 11.0% during the forecast period. The region accounts for roughly 3% of the global market share. Expansion is driven by smart government programs and adoption of biometric border control systems. Gulf Cooperation Council (GCC) countries invest in digital identity verification and airport security modernization. The UAE and Saudi Arabia lead in deploying fingerprint-based systems across financial institutions and government agencies. It gains traction in enterprise access control and healthcare authentication. Increasing smart city investments enhance regional prospects. Ongoing security digitization and diversification efforts create favorable growth conditions.
Africa
The Africa Global Fingerprint Biometrics Market size was valued at USD 127.67 million in 2018, reached USD 302.33 million in 2024, and is anticipated to attain USD 677.31 million by 2032, at a CAGR of 9.6% during the forecast period. Africa holds about 2% of the global market share. The region is developing steadily with growing government-led identification and e-governance initiatives. National biometric ID programs in Nigeria, Kenya, and South Africa drive market activity. It supports digital financial inclusion through secure verification in mobile banking and payment systems. Limited infrastructure and funding slow broader adoption, yet international partnerships improve deployment capacity. Increasing awareness of biometric advantages supports adoption in education and healthcare sectors. Expanding digital ecosystems and rising smartphone penetration continue to open new opportunities across the continent.
Key Player Analysis:
- NEC Corporation
- Safran S.A.
- Thales Group
- IDEMIA
- Cognitec Systems GmbH
- Aware, Inc.
- BIO-key International, Inc.
- Crossmatch
- Fujitsu Limited
- Gemalto
Competitive Analysis:
The Global Fingerprint Biometrics Market is highly competitive, with several global players vying for leadership through innovation and strategic partnerships. Companies emphasize rapid product launches, technological upgrades, and geographic expansion to enhance market positioning. Major vendors show strong capabilities in hardware sensor design, algorithm development, and software platforms, allowing integrated solutions. It drives differentiation around accuracy, speed, and user experience in biometric authentication systems. Mergers and acquisitions also appear frequently, enabling firms to broaden portfolios and access new customer segments. Firms collaborate with governments, financial institutions, and consumer-electronics manufacturers to penetrate various end-use sectors. Pricing pressures and evolving standards create a challenging environment but stimulate continuous improvement. The competitive landscape rewards firms that combine scale, technical expertise, and comprehensive service offerings.
Recent Developments:
- In September 2025, NEC Corporation announced a strategic partnership with HID Global, combining NEC’s advanced SmartScan biometric software with HID’s best-in-class hardware for public safety and mission-critical organizations.
- In October 2025, Thales Group launched a new Identity Verification and Account Recovery solution for enterprises and consumers, integrating technology from Badge for cryptographic binding. This solution, unveiled at the FIDO Alliance’s Authenticate 2025, uses face biometrics and liveness detection for high-assurance identity verification, enabling secure and seamless account recovery without passwords.
- In October 2025, IDEMIA Public Security successfully went live with NAFIS NextGen, a cloud-based biometric identification system in Australia, in partnership with the Australian Criminal Intelligence Commission.
Report Coverage:
The research report offers an in-depth analysis based on technology and offering segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for contactless fingerprint authentication in public and private sectors
- Integration of fingerprint biometrics with other modalities such as face and iris verification
- Growth of fingerprint solutions in IoT, smart-home, and automotive access control
- Expansion of biometric payment cards embedding fingerprint sensors
- Scaling of cloud-based biometric platforms offering fingerprint verification as a service
- Increased penetration in emerging economies through government ID and e-governance projects
- Enhancement of on-device intelligence for fingerprint recognition without server dependency
- Greater investment in anti-spoofing and liveness-detection technologies for fingerprint systems
- Shift toward subscription and managed-service models for fingerprint biometrics in enterprises
- Growing standardisation and regulatory frameworks influencing fingerprint data security and adoption

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Fingerprint Biometrics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Fingerprint Biometrics Marketprojected to grow between 2025 and 2032?
Which Global Fingerprint Biometrics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Fingerprint Biometrics Market?
Who are the leading companies in the Global Fingerprint Biometrics Market?
Which region commanded the largest share of the Global Fingerprint Biometrics Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 21,247.89 million → 2032: USD 63,013.22 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fingerprint Biometrics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fingerprint Biometrics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fingerprint Biometrics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fingerprint Biometrics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fingerprint Biometrics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fingerprint Biometrics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fingerprint Biometrics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fingerprint Biometrics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 21,247.89 million → 2032: USD 63,013.22 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fingerprint Biometrics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fingerprint Biometrics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Fingerprint Biometrics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Fingerprint Biometrics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

