
Market Overview
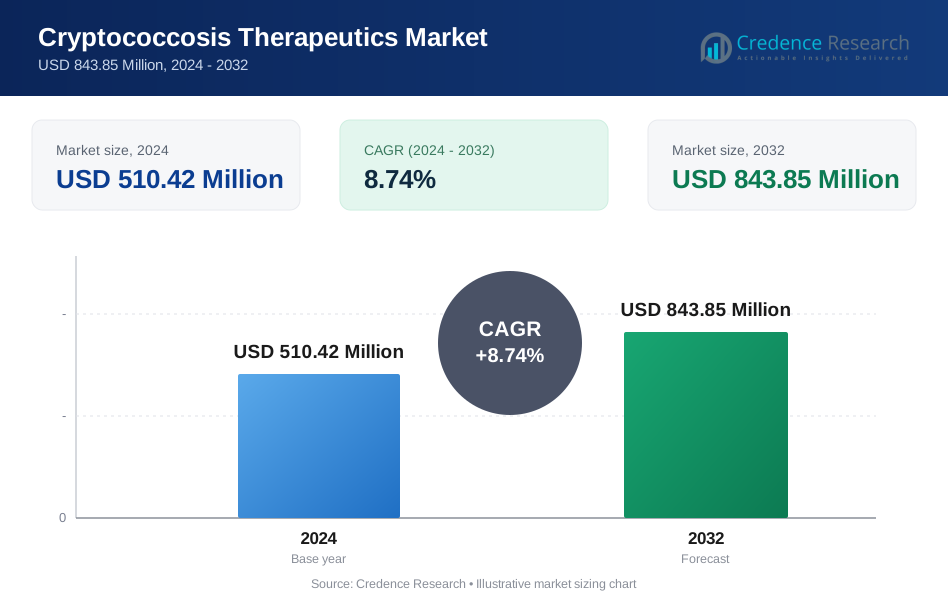
The Cryptococcosis Therapeutics Market is projected to grow from USD 510.42 Million in 2024 to an estimated USD 843.85 Million by 2032, with a CAGR of 8.74% from 2024 to 2032. Growth reflects sustained demand for antifungal treatment in immunocompromised patients, especially those with advanced HIV infection, organ transplants and hematologic malignancies. Rising adoption of guideline-based induction therapy, wider diagnosis in tertiary care settings and continued use of oral azoles for consolidation and maintenance treatment support market expansion. North America leads the market, supported by strong hospital infrastructure, higher diagnosis rates, established antifungal access and broad specialist-led management of invasive fungal infections.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period: | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cryptococcosis Therapeutics Market Market Size 2024 | USD 510.42 Million |
| Cryptococcosis Therapeutics Market CAGR | 8.74% |
| Cryptococcosis Therapeutics Market Market Size 2032 | USD 843.85 Million |
Market Insights
- North America held the leading regional position in 2024 with 34.2% of global revenue, driven by specialist hospital care, transplant volumes and broad antifungal availability.
- Antifungals dominated by drug class with an estimated 68.4% share in 2024 because they remain core therapy across induction, consolidation and maintenance treatment.
- Amphotericin B led molecule type demand with an estimated 42.1% share, supported by its central role in severe cryptococcal meningitis management.
- Pfizer, Merck & Co., Gilead Sciences, Teva and Astellas Pharma represent five major market participants with broad anti-infective reach and established institutional channels.
- Key market trend centers on greater use of liposomal amphotericin B-based induction regimens alongside low-cost oral azoles for longer-term outpatient therapy.
Market Segmentation Analysis
Antifungals held the largest share of the drug class segment at an estimated 68.4% in 2024. This dominance reflects their direct role as standard first-line treatment across acute and maintenance phases of cryptococcosis care. Hospitals continue to prioritize amphotericin B, flucytosine and azoles in defined treatment pathways, while combination therapy grows from a smaller base as clinical guidelines increasingly favor multidrug induction regimens for severe disease. Amphotericin B accounted for the largest share of the molecule type segment at an estimated 42.1% in 2024. Its leading position stems from consistent use in induction therapy for cryptococcal meningitis, especially in hospitalized and critically ill patients. Liposomal formulations also support revenue concentration because clinicians favor them when renal safety and tolerability matter, while azoles remain essential for step-down and long-term suppression. IV represented the dominant route of administration with an estimated 57.6% share in 2024. IV leadership reflects the need for rapid inpatient treatment during induction, particularly in severe central nervous system infection and high-risk immunocompromised cases. Oral therapy continues to expand through fluconazole and other azoles used after stabilization, yet hospital-driven initiation keeps IV administration in the leading position.Key Growth Drivers
Rising immunocompromised patient pool expands treated volume
Growing numbers of immunocompromised patients continue to expand the treated population for cryptococcosis therapeutics. Advanced HIV disease remains the most important clinical driver, particularly in settings where late diagnosis and treatment interruption persist. Global care programs now identify more fungal infections earlier, which increases initiation of induction, consolidation and maintenance therapy. This pattern supports recurring demand for amphotericin B, flucytosine and azoles across both hospital and outpatient settings. Cryptococcal meningitis still accounts for about 15% of AIDS-related deaths worldwide, which underscores the ongoing medical need for effective and timely antifungal intervention. As health systems strengthen HIV care pathways and referral networks, more patients enter treatment earlier, improving drug utilization across the care continuum.Hospital treatment protocols strengthen demand for induction therapy
Clinical practice increasingly favors structured hospital-led treatment pathways for cryptococcosis, which supports use of higher-value induction regimens. Severe disease often presents with central nervous system involvement, elevated intracranial pressure and urgent need for supervised inpatient care. These cases rely on IV antifungals, close laboratory monitoring and specialist infectious disease management. Updated therapeutic protocols have also improved regimen standardization, helping hospitals procure defined combinations rather than fragmented single-agent inventories. The World Health Organization recommends shorter induction approaches centered on liposomal amphotericin B with companion agents, reducing infusion burden and improving operational feasibility in treatment centers. As tertiary hospitals align formularies with these protocols, purchasing becomes more predictable and supports broader therapeutic adoption.Generic availability improves affordability and market reach
Broader availability of generic antifungals has improved affordability and widened geographic reach, especially in price-sensitive markets. Oral azoles such as fluconazole remain central to long-duration therapy, and generic competition helps providers maintain continuity after hospital discharge. Lower acquisition costs also support public procurement, donor-backed purchasing and inclusion in essential medicine programs. This cost dynamic matters because cryptococcosis treatment often extends for months and requires dependable access beyond acute care. Demand also benefits from growth in other immunosuppressed populations, including transplant and oncology patients who face elevated invasive fungal infection risk. In the United States alone, more than 46,000 organ transplants were performed in 2023, indicating a large and growing cohort that requires close fungal surveillance and timely access to antifungal therapy.Key Trends & Opportunities
Liposomal induction regimens reshape treatment practice
Clinical practice is shifting toward liposomal amphotericin B-based induction regimens that offer better tolerability and simpler administration than older prolonged infusion schedules. This trend influences hospital formularies, budget planning and physician preference in severe cryptococcal meningitis. It also raises demand for products that balance efficacy with renal safety and shorter inpatient resource use. Global guidance has accelerated this shift by endorsing single high-dose liposomal amphotericin B-based induction, which can reduce infusion days from seven to one in selected treatment protocols. That change improves feasibility for hospitals managing high patient loads and constrained nursing capacity.Oral step-down therapy gains operational importance
Oral therapy remains indispensable after initial disease control, and this is driving stronger focus on step-down and maintenance treatment pathways. Azoles continue to benefit from broad prescriber familiarity, lower administration burden and suitability for outpatient follow-up. Procurement teams increasingly evaluate total treatment continuity rather than only inpatient induction cost. This supports stable demand for reliable generic supply, patient adherence tools and discharge-linked prescribing. As more providers manage cryptococcosis through integrated infectious disease programs, oral formulations gain importance as the bridge between acute stabilization and long-term relapse prevention.Emerging markets create access-led growth potential
Significant opportunity lies in expanding access across Asia Pacific, Latin America and Africa, where disease burden remains high but treatment availability stays uneven. Public tenders, pooled procurement and local distribution partnerships can improve supply of amphotericin B, flucytosine and fluconazole in high-need settings. Manufacturers that adapt pack sizes, cold-chain planning and institutional pricing to public hospital demand can capture underpenetrated volume. Opportunities are strongest where governments and nonstate programs are improving fungal diagnostics, HIV linkage to care and essential medicine availability. Better access to full treatment regimens would support both clinical outcomes and market depth.Formulation innovation opens room for differentiation
Product innovation still offers meaningful opportunity in a market shaped by toxicity management, prolonged therapy and hospital workflow constraints. Companies can differentiate through lipid formulations, heat-stable presentations, easier reconstitution and products that fit low-resource treatment environments. There is also room for co-packaged therapy models that simplify induction and consolidation prescribing in hospital systems. Integration of rapid antigen testing with treatment initiation protocols could further increase timely therapy starts and reduce loss between diagnosis and drug administration. As clinical pathways become more standardized, suppliers with dependable quality, training support and broad distribution will be better positioned to secure long-term institutional demand.Key Challenges
Supply gaps limit full-regimen access
Access to complete cryptococcosis treatment remains uneven, especially in low-resource markets where flucytosine and liposomal amphotericin B availability can be inconsistent. Hospitals often rely on centralized tenders and imported supply, which creates risk of delay, stockouts and substitution with less optimal regimens. These constraints weaken treatment standardization and can shift demand toward lower-cost oral alternatives even when severe disease requires more intensive induction therapy.Toxicity burden and delayed diagnosis slow treatment uptake
Cryptococcosis therapy still carries meaningful clinical complexity because amphotericin B can require renal monitoring, electrolyte management and longer inpatient supervision. This increases total treatment cost and limits use in facilities with weak laboratory support. Delayed diagnosis also remains a major barrier, as many patients present late with advanced meningitis or systemic infection. Late presentation reduces treatment efficiency, complicates outcomes and constrains market development in settings where testing pathways remain fragmented.Regional Analysis
North America Cryptococcosis Therapeutics Market Market Trends
North America accounted for 34.2% of global Cryptococcosis Therapeutics Market revenue in 2024. Regional demand benefits from advanced diagnostic capacity, strong infectious disease referral networks and high treatment intensity in tertiary hospitals. Transplant centers, oncology programs and HIV specialty clinics drive steady use of amphotericin B-based induction therapy and long-course oral azoles. Hospital formularies increasingly favor lipid formulations when clinicians seek lower nephrotoxicity and shorter management complexity. Reimbursement structures support access to branded and generic antifungals, while institutional buyers emphasize supply reliability, clinical evidence and stewardship alignment. Competitive intensity remains high because multinational companies and generic suppliers both serve hospital and specialty pharmacy channels.Asia Pacific Cryptococcosis Therapeutics Market Market Trends
Asia Pacific accounted for 27.6% of global Cryptococcosis Therapeutics Market revenue in 2024. The region combines large patient pools with uneven access, creating strong volume potential but persistent pricing pressure. India, China and parts of Southeast Asia contribute demand through HIV care programs, tertiary infectious disease hospitals and rising immunosuppressed populations. Generic azoles play a major role in treatment continuity because affordability strongly influences prescribing and public procurement outcomes. IV antifungals remain concentrated in urban referral centers where severe cryptococcal meningitis is treated under specialist supervision. Local manufacturing strength in India supports regional supply, yet flucytosine access and premium lipid formulations remain less consistent across lower-income markets.Europe Cryptococcosis Therapeutics Market Market Trends
Europe accounted for 21.1% of global Cryptococcosis Therapeutics Market revenue in 2024. The market reflects structured guideline adherence, strong hospital pharmacy systems and broad availability of essential antifungal agents across major Western European countries. Demand centers on tertiary hospitals treating transplant recipients, hematology patients and complex HIV cases. Liposomal amphotericin B use is relatively well established where reimbursement supports higher-cost inpatient therapy and clinicians prioritize safety. Oral azoles maintain broad use for consolidation and maintenance, with generics supporting cost control in public systems. Western Europe shows stable premium uptake, while parts of Central and Eastern Europe rely more heavily on budget-sensitive procurement and generic supply.Latin America Cryptococcosis Therapeutics Market Market Trends
Latin America accounted for 8.4% of global Cryptococcosis Therapeutics Market revenue in 2024. Regional demand is shaped by HIV-associated cryptococcal disease, late-stage presentation and public-sector purchasing patterns. Brazil and Mexico anchor market activity through large hospital networks, reference laboratories and centralized procurement mechanisms. Generic fluconazole remains essential because treatment programs depend on affordable long-duration therapy after discharge. Amphotericin B demand stays concentrated in public hospitals and specialist centers, where supply planning and cold-chain execution affect treatment continuity. Market performance varies by country because reimbursement depth, import dependence and stock management differ widely across public health systems.Middle East & Africa Cryptococcosis Therapeutics Market Market Trends
Middle East & Africa accounted for 8.7% of global Cryptococcosis Therapeutics Market revenue in 2024. The region carries substantial clinical need, particularly in Sub-Saharan Africa, but revenue share remains constrained by access gaps and lower average treatment spending. Public hospitals and donor-supported programs drive most demand for amphotericin B and fluconazole, with procurement often tied to essential medicine budgets and tender cycles. Diagnostic expansion in HIV care is improving case finding, which supports more consistent treatment initiation in referral centers. Gulf markets contribute higher per-patient spending because hospitals have better access to premium formulations and specialist care. Competitive conditions differ sharply across the region, with local distribution capability and tender execution often determining market presence more than brand recognition alone.Market Segmentations
- By Drug Class
- Antifungals,
- Combination Therapy
- By Molecule Type
- Amphotericin B,
- Flucytosine,
- Azoles
- By Route of Administration
- IV
- Oral
- By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Competitive Landscape
The competitive landscape remains moderately fragmented, with multinational pharmaceutical companies and regional generic manufacturers competing across hospital and institutional channels. Innovation focus centers on safer amphotericin B formulations, dependable oral azole supply and treatment strategies that align with evolving cryptococcal meningitis protocols. Product strategy increasingly balances premium inpatient therapies with lower-cost maintenance medicines that support long treatment duration. Distribution strength plays a critical role because cryptococcosis care depends on tertiary hospitals, public tenders and specialist infectious disease networks. Partnerships with government buyers, nonprofit access programs and local distributors help companies improve reach in underpenetrated markets. Firms with sterile manufacturing capability, regulatory depth and broad emerging-market footprints hold an advantage in supply-sensitive settings. Competitive intensity is rising as generic suppliers expand in amphotericin B and azole categories. Price competition remains strongest in oral therapy, while hospital preference and formulation differentiation matter more in IV treatment segments.Key Player Analysis
- Pfizer
- Merck & Co.
- Gilead Sciences
- Teva
- Mylan
- Astellas Pharma
- Cipla
- Dr. Reddy’s
- Sun Pharma
- Glenmark
Recent Developments
- In February 2025, Gilead Sciences expanded access-focused supply initiatives for liposomal amphotericin B in high-burden markets, reinforcing public-hospital availability for cryptococcal meningitis induction therapy.
- In August 2025, Cipla broadened institutional distribution of key antifungal generics across selected African and Asian markets, supporting continuity of oral maintenance treatment in resource-constrained settings.
- In January 2026, Sun Pharma introduced additional azole antifungal presentations in emerging markets, increasing competitive pressure in outpatient and hospital step-down therapy channels.
Report Attribute Details
Details
Historical Period
-
Base Year
2024
Forecast Period
2024–2032
Cryptococcosis Therapeutics Size 2024
USD 510.42 Million
Cryptococcosis Therapeutics CAGR
8.74%
Cryptococcosis Therapeutics Size 2032
USD 843.85 Million
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
Q: What is the size of the Cryptococcosis Therapeutics Market in 2024?
A: The market is valued at USD 510.42 Million in 2024.
Q: What is the size of the Cryptococcosis Therapeutics Market in 2024?
A: The market is projected to reach USD 843.85 Million by 2032.
Q: What factors drive growth in the Cryptococcosis Therapeutics Market?
A: Growth is driven by rising immunocompromised patient populations, stronger hospital treatment protocols and wider generic antifungal access.
Q: What key trend is shaping the Cryptococcosis Therapeutics Market?
A: Increasing use of liposomal amphotericin B-based induction therapy with oral azole step-down treatment is shaping current demand.
Q: Who are the top players in the Cryptococcosis Therapeutics Market?
A: Leading companies include Pfizer, Merck & Co., Gilead Sciences, Teva and Astellas Pharma.
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 510.42 Million → 2032: USD 843.85 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cryptococcosis Therapeutics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cryptococcosis Therapeutics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cryptococcosis Therapeutics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cryptococcosis Therapeutics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cryptococcosis Therapeutics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cryptococcosis Therapeutics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cryptococcosis Therapeutics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cryptococcosis Therapeutics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 510.42 Million → 2032: USD 843.85 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cryptococcosis Therapeutics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cryptococcosis Therapeutics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cryptococcosis Therapeutics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cryptococcosis Therapeutics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

