
Wound Filler Market Overview:
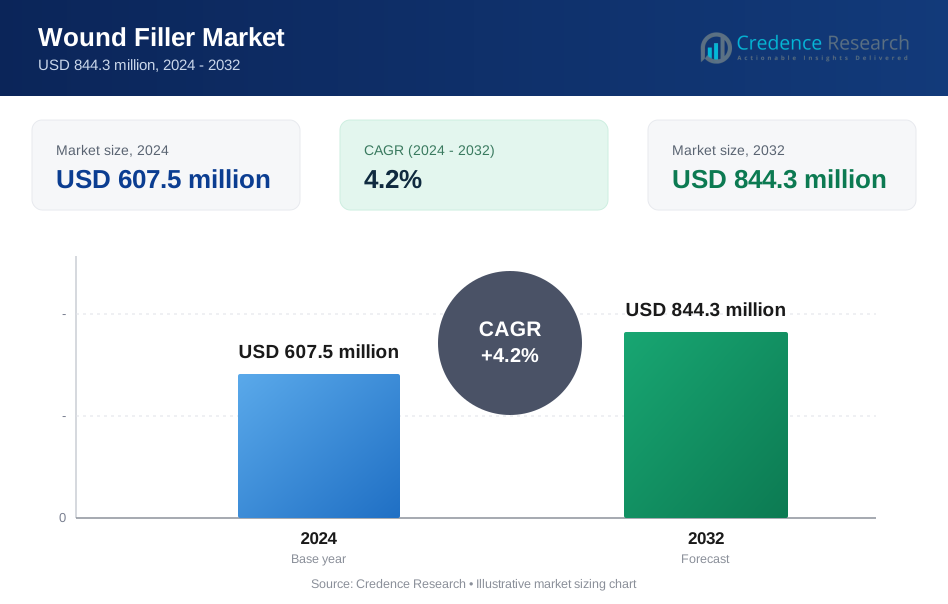
The wound filler market was valued at USD 607.5 million in 2024 and is expected to reach USD 844.3 million by 2032, growing at a CAGR of 4.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wound Filler Market Size 2024 | USD 607.5 million |
| Wound Filler Market, CAGR | 4.2% |
| Wound Filler Market Size 2032 | USD 844.3 million |
Wound Filler Market Insights
- Rising chronic wound incidence, especially diabetic foot ulcers and pressure ulcers, drives demand, with chronic wounds holding a 44% segment share due to longer treatment duration.
- Adoption of advanced wound management solutions is a key trend, with alginate wound fillers leading product segmentation at a 38% share due to high absorbency and clinical reliability.
- Competition remains strong among global players focusing on innovation, portfolio expansion, and hospital partnerships, while pricing pressure limits rapid margin expansion.
- North America leads with a 38% regional share, followed by Europe at 27%, Asia Pacific at 25%, and Rest of the World at 10%, reflecting healthcare infrastructure strength and awareness levels.

Wound Filler Market Segmentation Analysis:
By Product Type
By product type, alginate wound fillers dominate the wound filler market, accounting for nearly 38% of total revenue share. Alginate products lead due to strong absorbency, rapid gel formation, and effective exudate management. These features make alginates suitable for moderate to heavily exuding wounds. Rising use in chronic wound care and post-surgical management supports demand. Collagen wound fillers hold the second-largest share, driven by their ability to promote tissue regeneration. Hydrogel and foam-based wound fillers show steady adoption, supported by moisture balance and cushioning benefits in sensitive wound cases.
- For instance, many general alginate dressings absorb many times their weight in fluid, while specific products like Smith & Nephew's ALGISITE M are specified to absorb a significant, but lesser, amount. Conversely, hydrofiber dressings such as Aquacel Extra absorb a considerably greater amount of fluid compared to most alginate options.
By Wound Type
By wound type, chronic wounds represent the dominant sub-segment, contributing nearly 44% of overall market share. The high prevalence of diabetic foot ulcers, pressure ulcers, and venous leg ulcers drives sustained demand. Longer healing duration and frequent dressing replacement increase wound filler consumption. Aging populations and rising diabetes incidence further support dominance. Acute wounds account for a significant share due to trauma and injury cases. Surgical wounds continue to gain traction, supported by rising surgical volumes globally. Traumatic wounds show stable demand, particularly in emergency care and accident-related treatments.
- For instance, ConvaTec Group plc supplies an extensive volume of advanced wound care dressings to patients worldwide, maintaining a significant global market share through its specialized chronic wound management portfolios.
By End User
By end user, hospitals lead the wound filler market with a share of approximately 41%. Hospitals dominate due to high patient inflow, advanced wound management protocols, and access to skilled healthcare professionals. Complex chronic and surgical wounds are primarily treated in hospital settings. Specialty clinics follow, driven by focused wound care services and outpatient treatment models. Ambulatory surgical centers expand adoption due to shorter procedure stays and cost efficiency. Home healthcare settings register rising demand, supported by aging populations, preference for home-based care, and improved availability of easy-to-use wound filler products.
Key Growth Drivers
Rising Prevalence of Chronic Wounds
The growing burden of chronic wounds strongly drives the wound filler market. Conditions such as diabetic foot ulcers and pressure ulcers continue to increase. Aging populations and lifestyle-related diseases raise long-term wound care demand. Chronic wounds need frequent dressing changes and advanced healing support. Wound fillers manage exudate and support tissue regeneration. Hospitals and clinics rely on fillers for consistent outcomes. Longer healing timelines increase product usage. Demand remains stable across regions. This driver sustains recurring consumption and supports long-term growth.
- For instance, Mölnlycke Health Care validated alginate and foam dressings across more than 1,200 chronic wound patients in clinical use programs.
Growth in Surgical Procedures Worldwide
Rising surgical volumes fuel demand for wound fillers across care settings. Elective surgeries and trauma cases continue to expand globally. Post-operative care requires effective fillers to reduce complications. Surgeons prefer products that control moisture and lower infection risk. Wound fillers support faster recovery and better outcomes. Expanding healthcare infrastructure boosts surgical capacity. Medical tourism adds further procedure volume. This driver supports adoption in hospitals and ambulatory centers. Surgical growth ensures steady and predictable demand.
- For instance, 3M Company has documented the clinical use of its advanced surgical wound dressings across numerous hospital systems to help clinicians protect surgical sites and improve patient outcomes.
Advancements in Wound Care Technologies
Technology progress remains a key growth driver for wound fillers. Manufacturers introduce materials with higher absorbency and biocompatibility. Improved performance enhances healing outcomes and safety. Advanced fillers reduce dressing frequency and labor needs. Clinicians favor innovative solutions over basic dressings. Product differentiation strengthens supplier positioning. Regulatory approvals support wider clinical use. Continued R&D improves formulation reliability. These advances increase clinician confidence and patient acceptance.
Key Trends & Opportunities
Shift Toward Advanced Wound Management Solutions
Healthcare providers increasingly adopt advanced wound management practices. Wound fillers replace basic gauze in many protocols. Advanced solutions shorten healing time and reduce complications. Hospitals seek products that improve workflow efficiency. Standardized care pathways support routine filler use. Ease of application drives clinician preference. This trend creates opportunities for premium offerings. Suppliers benefit from higher-value adoption. Training programs further support clinical uptake.
- For instance, B. Braun Melsungen AG has implemented the clinical deployment of advanced wound fillers and dressings across numerous healthcare facilities by utilizing standardized wound care frameworks, such as the TIME concept, to improve patient outcomes.
Expansion of Home Healthcare and Outpatient Care
Home healthcare growth creates strong opportunities for wound filler suppliers. Patients prefer home-based care for chronic wound treatment. Shorter hospital stays increase outpatient reliance. Easy-to-use fillers support self-care and caregiver use. Aging populations drive demand for home solutions. Portability and safety influence purchasing decisions. Suppliers adapt packaging for home settings. Distribution expands beyond hospitals. This opportunity diversifies end-user demand and channels.
- For instance, Coloplast A/S documented distribution of wound care products to more than 900,000 home-care patients through outpatient and home delivery programs.
Key Challenges
High Cost of Advanced Wound Fillers
High costs remain a major challenge for the wound filler market. Advanced products cost more than traditional dressings. Budget limits restrict adoption in price-sensitive regions. Public healthcare systems face reimbursement pressure. Cost concerns affect hospital procurement choices. Smaller clinics choose lower-cost options. Price competition limits margin expansion. Limited reimbursement slows advanced uptake. Affordability remains critical for wider adoption.
Limited Awareness in Developing Regions
Low awareness limits wound filler adoption in developing regions. Many providers rely on traditional wound care methods. Limited training restricts advanced product use. Rural facilities face resource constraints. Awareness gaps slow technology penetration. Inconsistent guidelines reduce standardized adoption. Education programs need time and funding. Distribution remains uneven. These barriers delay market expansion and demand realization.
Regional Analysis
North America
North America leads the wound filler market with a market share of 38%. High chronic wound prevalence drives sustained product demand. Strong hospital infrastructure supports advanced wound management adoption. Diabetes and obesity rates increase long-term wound care needs. Favorable reimbursement policies support product penetration. Hospitals dominate end-user demand across the region. Strong presence of established manufacturers ensures product availability. Continuous innovation supports clinician preference for advanced fillers. Home healthcare adoption also expands steadily. These factors maintain North America’s leadership position.
Europe
Europe holds a market share of 27% in the wound filler market. Aging populations increase chronic wound incidence across key countries. Strong public healthcare systems support standardized wound care protocols. Hospitals and specialty clinics drive consistent product demand. Government focus on patient safety supports advanced dressing adoption. Rising surgical volumes further strengthen usage. Regional manufacturers invest in product innovation and compliance. Increasing outpatient care supports broader adoption. Stable healthcare funding sustains long-term market growth across Europe.
Asia Pacific
Asia Pacific accounts for a market share of 25% in the wound filler market. Large patient populations drive rising wound care demand. Increasing diabetes prevalence supports chronic wound treatment needs. Expanding healthcare infrastructure improves access to advanced products. Hospital capacity growth supports higher adoption rates. Medical tourism increases surgical wound management demand. Government healthcare investments strengthen regional supply chains. Awareness of advanced wound care continues to improve. This region shows strong growth momentum across emerging economies.
Rest of the World
Rest of the World holds a market share of 10% in the wound filler market. Latin America and the Middle East drive regional demand growth. Rising healthcare investment improves access to wound care products. Chronic disease prevalence supports steady usage. Hospitals remain the primary end users across these regions. Limited reimbursement restricts advanced product penetration. Gradual awareness improvement supports adoption trends. Private healthcare expansion drives demand in urban areas. Market growth remains stable but uneven across countries.
Wound Filler Market Segmentations:
By Product Type
- Alginate wound fillers
- Collagen wound fillers
- Hydrogel wound fillers
- Foam-based wound fillers
By Wound Type
- Chronic wounds
- Acute wounds
- Surgical wounds
- Traumatic wounds
By End User
- Hospitals
- Specialty clinics
- Ambulatory surgical centers
- Home healthcare settings
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights strong competition among Smith & Nephew, Mölnlycke Health Care, 3M Company, Convatec Group plc, and Coloplast A/S. These players focus on broad product portfolios and strong clinical validation. Companies invest in material innovation to improve absorbency and healing outcomes. Product differentiation remains a core competitive strategy. Global distribution networks support consistent market presence. Strategic acquisitions strengthen wound care portfolios. Partnerships with hospitals improve product adoption. Regulatory compliance ensures trust and long-term use. Pricing strategies balance premium products with cost control. Emerging players focus on niche applications and regional expansion. Overall competition remains innovation driven and clinically focused.
Key Player Analysis
- Smith & Nephew
- Mölnlycke Health Care
- 3M Company
- Convatec Group plc
- Coloplast A/S
- Braun Melsungen AG
- Medtronic plc
- Cardinal Health, Inc.
- Paul Hartmann AG
- Integra LifeSciences
Recent Developments
- In July 2025, Convatec Group plc secured regulatory clearance for AQUACEL ConvaFiber.
- In May 2025, Smith & Nephew won a DoD contract for RENASYS TOUCH NPWT systems.
- In September 2024, 3M Company (via Solventum) launched the V.A.C. Peel and Place Dressing.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Wound Type, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for wound fillers will rise due to growing chronic disease prevalence.
- Advanced wound care adoption will expand across hospitals and outpatient settings.
- Home healthcare will increase product usage for long-term wound management.
- Product innovation will focus on higher absorbency and faster healing outcomes.
- Manufacturers will invest in biocompatible and skin-friendly materials.
- Emerging markets will show stronger adoption with healthcare infrastructure growth.
- Strategic partnerships will support wider clinical acceptance and distribution.
- Cost-effective product development will improve access in price-sensitive regions.
- Training programs will improve clinician awareness and standardized usage.
- Regulatory approvals will support broader application across wound types.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Wound Filler market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wound Filler market projected to grow between 2024 and 2032?
Which Wound Filler market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wound Filler market?
Who are the leading companies in the Wound Filler market?
Which region commanded the largest share of the Wound Filler market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Wound Filler Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Wound Filler Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 607.5 million → 2032: USD 844.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Wound Filler Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Wound Filler Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Wound Filler Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Wound Filler Market Drivers
- 3.3 Wound Filler Market Restraints & Challenges
- 3.4 Wound Filler Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Wound Filler Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Wound Filler Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Wound Filler category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Wound Filler Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Wound Filler Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Wound Filler market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Wound Filler Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Wound Filler Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Wound Filler Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Wound Filler (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Wound Filler Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Wound Filler Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Wound Filler Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Wound Filler Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Wound Filler Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Wound Filler Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Wound Filler Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Wound Filler Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Wound Filler Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
