
Smart Wheelchair Market Overview:
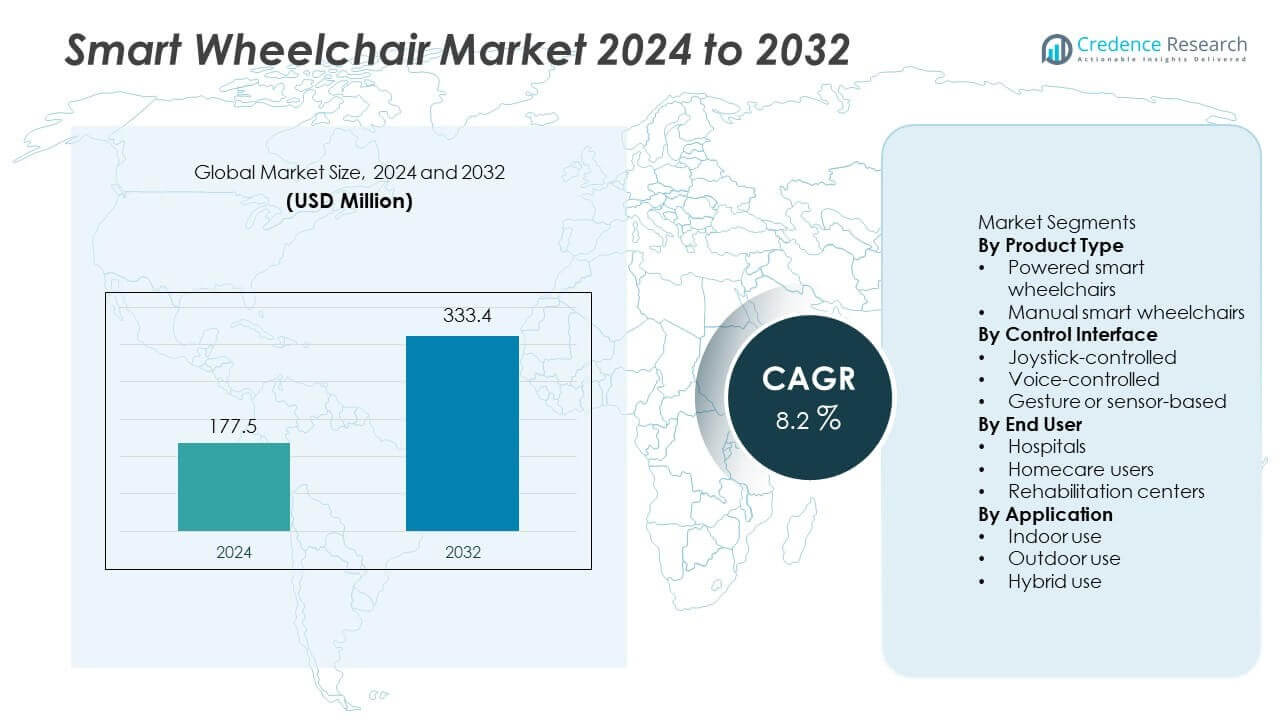
The Smart Wheelchair market was valued at USD 177.5 million in 2024 and is anticipated to reach USD 333.4 million by 2032, growing at a CAGR of 8.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Wheelchair Market Size 2024 | USD 177.5 million |
| Smart Wheelchair Market, CAGR | 8.2% |
| Smart Wheelchair Market Size 2032 | USD 333.4 million |
Smart Wheelchair Market Insights
- Aging populations, rising disability prevalence, and preference for independent living act as key growth drivers, with powered smart wheelchairs leading the product segment with a market share of 64.3%.
- Technological innovation is a major trend, as joystick-controlled systems dominate the control interface segment with a market share of 52.7% due to ease of use and reliability.
- Competitive intensity remains moderate, with leading players focusing on AI-enabled navigation and safety features, while high product costs and limited reimbursement act as key market restraints.
- Regionally, North America leads with a market share of 37.8%, followed by Europe at 29.4% and Asia Pacific at 21.6%, supported by healthcare infrastructure, aging demographics, and growing homecare adoption.
Smart Wheelchair Market Segmentation Analysis:
By Product Type
By product type, powered smart wheelchairs dominate the Smart Wheelchair market with a market share of 64.3%. Strong demand comes from users with severe mobility limitations who require motorized assistance for daily movement. Powered models offer advanced features such as obstacle detection, automated navigation, and connectivity with smart devices. Aging populations and rising disability prevalence support adoption. Healthcare providers prefer powered wheelchairs for improved patient independence and safety. Manual smart wheelchairs hold the remaining share, driven by lower costs and suitability for users with partial mobility. However, limited automation capabilities keep powered smart wheelchairs in the leading position.
- For instance, Invacare integrates LiNX control systems with real-time diagnostics supporting numerous programmable seating and drive parameters per chair.
By Control Interface
By control interface, joystick-controlled smart wheelchairs lead the market with a market share of 52.7%. Joystick systems offer reliability, ease of use, and precise maneuverability, making them widely accepted across age groups. Hospitals and homecare users favor joystick controls due to minimal training requirements. Voice-controlled interfaces follow, supported by advances in speech recognition and AI. Gesture or sensor-based controls show steady growth, driven by demand from users with limited hand function. Despite innovation in alternative interfaces, joystick-controlled systems remain dominant due to affordability, accuracy, and broad compatibility with existing wheelchair platforms.
- For instance, WHILL Inc. deploys dual-motor joystick control delivering a turning radius of 760 millimeters and obstacle clearance up to 50 millimeters.
By End User
By end user, homecare users hold the largest share at 46.9% in the Smart Wheelchair market. Rising preference for independent living and home-based care drives demand. Smart wheelchairs enable mobility, safety, and remote monitoring within residential environments. Growing elderly populations and caregiver shortages support homecare adoption. Hospitals account for the second-largest share, driven by patient mobility needs during treatment and recovery. Rehabilitation centers follow, using smart wheelchairs for therapy and training purposes. Homecare leadership reflects strong demand for personalized mobility solutions and increased focus on quality of life outside clinical settings.
Key Growth Drivers
Rising Aging Population and Disability Prevalence
The global rise in the elderly population increases long-term mobility challenges. Chronic illnesses and physical disabilities drive demand for advanced mobility solutions. Smart wheelchairs support independent movement and daily activities. Families seek solutions that reduce caregiver dependency. Healthcare systems promote assistive devices to improve quality of life. Smart navigation and safety features enhance user confidence. Urban living conditions increase the need for compact and intelligent mobility aids. Public healthcare initiatives support assistive technology adoption. This driver sustains steady demand across homecare and clinical environments.
- For instance, Ottobock SE & Co. KGaA integrates sensor technology within its powered wheelchair platforms to facilitate intelligent speed control and automated safety adjustments based on the driving environment.
Growing Focus on Independent Living and Homecare
Healthcare systems increasingly shift toward home-based care models. Patients prefer recovery and long-term care at home. Smart wheelchairs enable safe and autonomous indoor mobility. Remote monitoring features support caregivers and clinicians. Automation reduces continuous physical assistance needs. Smart alerts improve fall prevention and safety outcomes. Aging-in-place policies support adoption of assistive devices. Cost pressures favor homecare over institutional care. This driver significantly accelerates smart wheelchair adoption among elderly and disabled users.
- For instance, Invacare Corporation equips its power wheelchair systems with intelligent drive technology that supports extended daily use on a single battery cycle. Its advanced control platforms incorporate gyroscopic stabilization and wireless monitoring apps to enhance user safety and performance.
Technological Advancements in Sensors and AI
Advances in sensors improve obstacle detection and navigation accuracy. AI-driven controls enhance route planning and safety. Connectivity enables personalization and adaptive control settings. Battery improvements extend daily operating time. Compact motors improve maneuverability in tight spaces. Software updates add continuous feature enhancements. Integration with smart home systems increases usability. Predictive maintenance improves device reliability. This driver strengthens product differentiation and long-term market growth.
Key Trends & Opportunities
Adoption of Voice and Sensor-Based Interfaces
Hands-free control interfaces improve accessibility for users with limited motor function. Voice recognition accuracy improves with AI learning. Sensor-based inputs support complex mobility needs. Custom profiles enhance comfort and ease of use. Clinical validation supports usability improvements. Accessibility regulations encourage innovation. These interfaces expand the addressable user base. Premium features create differentiation opportunities. This trend opens new growth avenues for manufacturers.
- For instance, Sunrise Medical integrates voice control modules capable of recognizing several distinct command inputs with low response latency.
Integration with Digital Health Platforms
Smart wheelchairs increasingly connect with digital health ecosystems. Data sharing supports coordinated care delivery. Clinicians monitor usage and mobility patterns remotely. Real-time alerts improve patient safety. Cloud connectivity enables software upgrades. Interoperability increases system value. Partnerships with health technology firms expand offerings. Subscription-based services create recurring revenue. This opportunity supports long-term ecosystem development.
- For instance, Panasonic Holdings Corporation supports assistive mobility through products like the Resyone robotic bed, which integrates wheelchair functionality with automated systems to enhance caregiver efficiency and user independence.
Key Challenges
High Initial Costs and Limited Reimbursement
Smart wheelchairs involve high upfront investment. Advanced electronics and sensors raise production costs. Reimbursement policies vary widely by region. Limited insurance coverage restricts affordability. Budget constraints slow adoption in emerging markets. Financing options remain uneven. Public funding support is limited in many regions. Cost sensitivity affects purchasing decisions. This challenge restricts broader market penetration.
Technical Complexity and Maintenance Requirements
Smart wheelchairs require regular technical maintenance. Software failures can disrupt daily use. Skilled service availability remains limited in some regions. Battery replacement increases ownership costs. User training needs increase onboarding time. Reliability concerns affect long-term trust. Rural areas face service access challenges. Manufacturers must strengthen support networks. This challenge impacts scalability and user satisfaction.
Regional Analysis
North America
North America leads the Smart Wheelchair market with a market share of 37.8%. Strong healthcare infrastructure and high adoption of assistive technologies support regional dominance. Rising aging population and favorable reimbursement policies drive demand. Homecare users increasingly adopt smart wheelchairs to support independent living. Hospitals and rehabilitation centers invest in advanced mobility solutions to improve patient outcomes. Technological innovation and early adoption of AI-based controls strengthen market growth. Strong presence of leading manufacturers ensures product availability. Government programs supporting disability care further reinforce sustained demand across the region.
Europe
Europe holds a market share of 29.4% in the Smart Wheelchair market. Aging demographics and rising disability prevalence drive adoption across countries. Public healthcare systems support access to advanced mobility aids. Rehabilitation centers play a major role in smart wheelchair deployment. Strong focus on accessibility and inclusion policies supports market expansion. Technological innovation and safety standards enhance product reliability. Western Europe leads adoption due to higher healthcare spending, while Eastern Europe shows gradual growth. Government-backed assistive device funding and rising homecare preference sustain regional demand.
Asia Pacific
Asia Pacific accounts for a market share of 21.6%, driven by a growing elderly population and expanding healthcare access. Rising awareness of assistive mobility solutions supports adoption. Urbanization increases demand for compact and intelligent wheelchairs. Homecare users show growing preference for smart mobility devices. Improving healthcare infrastructure and rising disposable incomes support market growth. Domestic manufacturing reduces costs and improves availability. Government initiatives focused on elderly care and disability support further encourage adoption. Asia Pacific remains a high-growth region with expanding unmet mobility needs.
Latin America
Latin America represents a market share of 6.8% in the Smart Wheelchair market. Demand is driven by growing awareness of assistive technologies. Public hospitals and rehabilitation centers remain key end users. Aging populations increase long-term mobility requirements. Limited reimbursement coverage constrains faster adoption. Cost sensitivity affects purchasing decisions. Urban areas show higher adoption due to better healthcare access. Government disability programs support gradual market expansion. Improving healthcare infrastructure and rising homecare demand contribute to steady regional growth.
Middle East & Africa
The Middle East and Africa region holds a market share of 4.4%. Demand is supported by rising investments in healthcare infrastructure. Government-funded hospitals drive smart wheelchair adoption. Growing focus on elderly and disability care supports market activity. Advanced healthcare facilities in the Middle East adopt smart mobility solutions. Limited access and affordability challenges persist in parts of Africa. Import dependence affects product availability. Awareness programs and urban healthcare expansion support gradual adoption. Long-term investments in healthcare systems sustain moderate regional growth.
Smart Wheelchair Market Segmentations:
By Product Type
- Powered smart wheelchairs
- Manual smart wheelchairs
By Control Interface
- Joystick-controlled
- Voice-controlled
- Gesture or sensor-based
By End User
- Hospitals
- Homecare users
- Rehabilitation centers
By Application
- Indoor use
- Outdoor use
- Hybrid use
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights active competition among Permobil AB, Invacare Corporation, Sunrise Medical, Ottobock SE & Co. KGaA, and WHILL Inc.. The Smart Wheelchair market shows moderate to high entry barriers due to technology complexity and regulatory requirements. Leading players focus on powered models with advanced navigation, safety sensors, and connectivity features. Product innovation centers on user comfort, battery efficiency, and intelligent control interfaces. Companies invest in R&D to integrate AI, IoT, and digital health capabilities. Strategic partnerships with healthcare providers and rehabilitation centers strengthen market access. Expansion into homecare applications remains a key growth strategy. After-sales service quality and customization options influence purchasing decisions. Competitive positioning depends on technology leadership, pricing strategy, and strong distribution networks across developed and emerging regions.
Key Player Analysis
- Permobil AB
- Invacare Corporation
- Sunrise Medical
- Ottobock SE & Co. KGaA
- WHILL Inc.
- Pride Mobility Products Corp.
- Panasonic Holdings Corporation
- Toyota Motor Corporation
- Hoveround Corporation
- Drive DeVilbiss Healthcare
Recent Developments
- In August 2025, Permobil expanded a voluntary recall of the SpeedControl Dial for the SmartDrive MX2+ power assist device due to intermittent connection concerns, affecting control options and emphasizing safety review.
- In August 2025, Permobil partnered with munevo to offer intuitive, hands-free wheelchair control via smartglass technology, boosting mobility independence.
- In June 2025, Invacare unveiled the limited edition Küschall Element wheelchair at Autonomic Paris, showcasing innovations in materials and design for enhanced mobility user experience.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Control Interface, End User, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Aging Population and Disability Prevalence
The increasing global elderly population and higher rates of chronic illness and physical disabilities are driving demand for advanced mobility solutions like smart wheelchairs. These devices support independent movement and daily activities, reducing caregiver dependency and improving quality of life.
Growing Focus on Independent Living and Homecare
Healthcare systems are shifting toward home-based care, with patients preferring to recover and live independently at home. Smart wheelchairs enable safe, autonomous indoor mobility and remote monitoring, supporting the trend toward aging-in-place and reducing the need for institutional care.
Technological Advancements in Sensors and AI
Innovations in sensors, AI-driven controls, and connectivity are enhancing obstacle detection, navigation, and personalization in smart wheelchairs. These advancements improve safety, maneuverability, and user experience, making smart wheelchairs more attractive to both users and healthcare providers.
Adoption of Voice and Sensor-Based Interfaces
The development of hands-free control interfaces, such as voice and sensor-based systems, is expanding accessibility for users with limited motor function. Improved usability and regulatory support for accessibility are broadening the addressable market and creating new growth opportunities.
Integration with Digital Health Platforms
Smart wheelchairs are increasingly being integrated with digital health ecosystems, enabling remote monitoring, real-time alerts, and coordinated care. This connectivity enhances patient safety, supports clinical decision-making, and adds value for both users and healthcare providers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Smart Wheelchair market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Smart Wheelchair market projected to grow between 2024 and 2032?
Which Smart Wheelchair market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Smart Wheelchair market?
Who are the leading companies in the Smart Wheelchair market?
Which region commanded the largest share of the Smart Wheelchair market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Homecare users
- 1.2.3 Rehabilitation centers
- 1.3 By Application
- 1.3.1 Indoor use
- 1.3.2 Outdoor use
- 1.3.3 Hybrid use
- 1.4 By Product Type
- 1.4.1 Powered smart wheelchairs
- 1.4.2 Manual smart wheelchairs
- 1.5 By Control Interface
- 1.5.1 Joystick-controlled
- 1.5.2 Voice-controlled
- 1.5.3 Gesture or sensor-based
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 177.5 million → 2032: USD 333.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Wheelchair Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Wheelchair Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Wheelchair Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Wheelchair Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Wheelchair Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Wheelchair Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Wheelchair Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Wheelchair Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 177.5 million → 2032: USD 333.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Wheelchair Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Homecare users
- 12.3.7.3 Rehabilitation centers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Indoor use
- 12.4.7.2 Outdoor use
- 12.4.7.3 Hybrid use
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Powered smart wheelchairs
- 12.5.7.2 Manual smart wheelchairs
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Control Interface - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Joystick-controlled
- 12.6.7.2 Voice-controlled
- 12.6.7.3 Gesture or sensor-based
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Wheelchair End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Wheelchair Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Wheelchair Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Wheelchair Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Permobil AB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Invacare Corporation
- 18.4 Sunrise Medical
- 18.5 Ottobock SE & Co. KGaA
- 18.6 WHILL Inc.
- 18.7 Pride Mobility Products Corp.
- 18.8 Panasonic Holdings Corporation
- 18.9 Toyota Motor Corporation
- 18.10 Hoveround Corporation
- 18.11 Drive DeVilbiss Healthcare
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

