
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Customer Advocacy Software Market Size 2024 | USD 724 Million |
| Customer Advocacy Software Market, CAGR | 9.1% |
| Customer Advocacy Software Market Size 2032 | USD 1,453.23 Million |
Market Overview
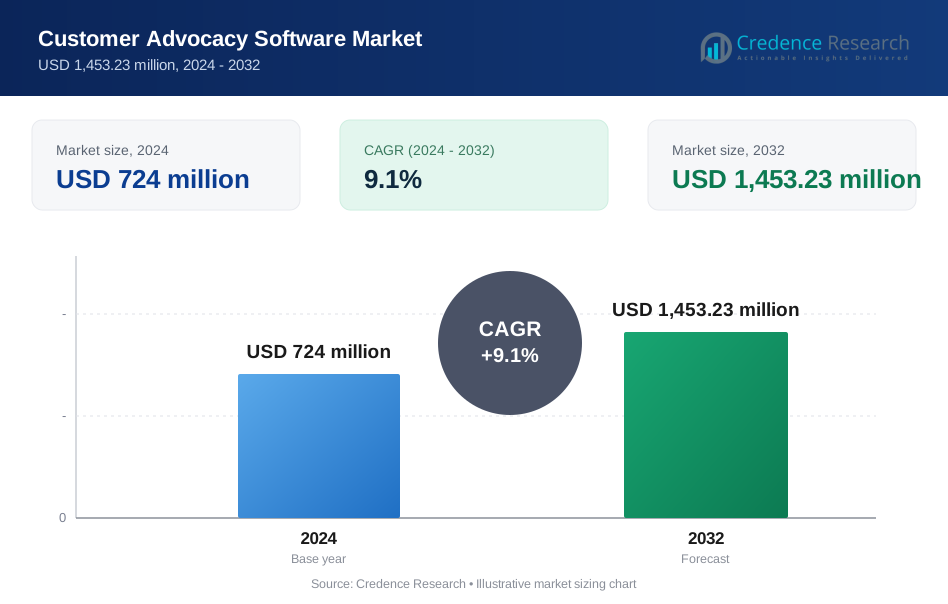
The Customer Advocacy Software Market is projected to grow from USD 724 million in 2024 to USD 1,453.23 million by 2032, with a compound annual growth rate (CAGR) of 9.1%.
The Customer Advocacy Software Market is driven by the increasing importance of customer-centric strategies and the growing recognition of brand advocacy as a powerful tool for driving organic growth. As businesses prioritize enhancing customer experiences and fostering loyalty, customer advocacy platforms are becoming essential for managing referral programs, reviews, and testimonials. The rise of social media and digital platforms amplifies the influence of customer advocates, further fueling demand for these solutions. Additionally, the trend of leveraging data analytics to measure advocacy success and improve marketing strategies is gaining traction. Integration of AI and automation technologies is another trend, helping companies streamline engagement processes and personalize interactions. The adoption of cloud-based solutions is also expanding due to their scalability and flexibility, contributing to market growth.
The Customer Advocacy Software Market exhibits varying growth across regions, with North America holding the largest market share at 38% in 2024, driven by advanced technology adoption and customer-centric strategies. Europe follows closely with a 25% share, supported by strong demand for cloud-based solutions and stringent data protection regulations. Asia-Pacific is the fastest-growing region, expected to account for 20% of the market share in 2024, fueled by the rise of digital economies and e-commerce. Latin America and the Middle East & Africa represent smaller markets, together making up 17%, but are seeing gradual adoption as digitalization expands. Key players, including Influitive, Advocately, Crowdly, Zuberance, Ambassify, PostBeyond, Bambu by Sprout Social, Customer Advocacy, GaggleAMP, and Sociabble, are focusing on region-specific solutions to capitalize on growth opportunities in these diverse markets.
Market Insights
- The Customer Advocacy Software Market is projected to grow from USD 724 million in 2024 to USD 1,453.23 million by 2032, with a CAGR of 9.1%.
- Increasing importance of customer-centric strategies is driving the demand for customer advocacy platforms to manage referrals, reviews, and testimonials.
- Social media influence continues to grow, with customer advocacy software amplifying the reach of customer advocates on digital platforms.
- The integration of AI and automation technologies is enhancing personalization, streamlining engagement, and improving customer satisfaction.
- Cloud-based solutions are gaining traction due to their flexibility, scalability, and cost-effectiveness for businesses of all sizes.
- North America holds the largest market share at 38% in 2024, supported by technology adoption and a focus on customer experience.
- Asia-Pacific is the fastest-growing region with a 20% market share in 2024, driven by the digital economy, e-commerce, and increasing use of cloud-based solutions.
Market Drivers
Growing Focus on Customer-Centric Strategies
The shift toward customer-centric strategies is a key driver in the Customer Advocacy Software Market. Businesses today are prioritizing customer satisfaction, loyalty, and long-term engagement over traditional marketing methods. For instance, Influitive provides customer advocacy software that allows businesses to effectively manage and leverage customer testimonials, reviews, and referrals, enhancing the overall customer experience and brand loyalty. As consumers become more empowered through digital channels, their voices hold significant influence over purchasing decisions.
Increasing Influence of Social Media
Social media platforms have become a dominant force in shaping consumer perceptions and behaviors. The growing reliance on social media for product recommendations and reviews has made customer advocates more valuable than ever. For instance, Ambassador offers customer advocacy software that helps companies tap into the power of social media by amplifying the reach of their advocates. These platforms enable businesses to identify key advocates, manage social media interactions, and track the effectiveness of advocacy campaigns, making them indispensable in today's digital age.
Adoption of AI and Automation Technologies
The integration of artificial intelligence (AI) and automation technologies is transforming the customer advocacy landscape. Companies are increasingly using AI-driven tools to streamline processes such as customer engagement, sentiment analysis, and campaign management. For instance, Zinrelo provides automation features within its customer advocacy software that help businesses personalize interactions and deliver timely responses, ultimately improving customer satisfaction. AI also provides valuable insights into customer behaviors, enabling businesses to optimize their advocacy programs and improve overall marketing effectiveness.
Growing Demand for Cloud-Based Solutions
Cloud-based customer advocacy software is gaining widespread adoption due to its flexibility, scalability, and cost-effectiveness. For instance, Advocately offers cloud solutions that facilitate remote access and collaboration, making it easier for teams to manage advocacy programs across multiple locations. As businesses look for solutions that can easily adapt to their growing needs, cloud-based platforms offer the ability to scale operations without the need for significant infrastructure investments.
Market Trends
Rise of Data-Driven Advocacy Programs
A key trend in the Customer Advocacy Software Market is the growing emphasis on data-driven advocacy programs. Companies are increasingly relying on analytics to measure the success of their advocacy initiatives, track customer sentiment, and identify their most influential advocates. For instance, Influitive offers advanced analytics tools that enable companies to make informed decisions and improve overall program effectiveness. By leveraging advanced analytics, businesses can optimize their advocacy strategies, tailor campaigns to specific customer segments, and drive higher engagement rates.
Integration of Artificial Intelligence and Machine Learning
The integration of artificial intelligence (AI) and machine learning (ML) into customer advocacy platforms is transforming how businesses manage and enhance their advocacy programs. AI and ML tools enable companies to automate key processes such as sentiment analysis, advocate identification, and engagement tracking. For instance, Zinrelo integrates AI and ML tools to help businesses personalize interactions, ensuring that customers receive tailored content and offers based on their preferences and behaviors. This trend is helping businesses achieve more efficient and impactful advocacy efforts, while also improving customer satisfaction.
Expansion of Social Media Advocacy
As social media continues to dominate consumer interactions, businesses are increasingly focusing on social media advocacy to amplify their brand presence. For instance, Ambassador offers solutions that allow businesses to expand their advocacy efforts and reach a broader audience, driving brand awareness and fostering deeper customer relationships. Customer advocacy software platforms are evolving to offer seamless integration with social media channels, enabling companies to monitor and engage with their advocates across multiple platforms.
Growth in Cloud-Based Solutions
The demand for cloud-based customer advocacy software solutions is on the rise due to their scalability, flexibility, and ease of deployment. Cloud-based platforms enable companies to manage their advocacy programs remotely and collaborate with teams across various locations. For instance, Advocately provides cloud-based solutions that facilitate remote access and collaboration, making it easier for teams to manage advocacy programs across multiple locations. The trend toward cloud adoption is also driven by the need for cost-effective solutions that can scale with business growth, making it an attractive option for enterprises of all sizes.
Market Challenges Analysis
High Implementation Costs and Complexity
One of the significant challenges facing the Customer Advocacy Software Market is the high implementation costs and the complexity involved in integrating these platforms into existing business systems. For many organizations, especially small and medium-sized enterprises (SMEs), the financial investment required to adopt customer advocacy software can be prohibitive. The initial setup, customization, and ongoing maintenance of the software may involve substantial expenses. Furthermore, the complexity of integrating customer advocacy platforms with other systems such as customer relationship management (CRM), marketing automation, and social media management tools can pose additional technical challenges. Businesses may require specialized expertise to ensure seamless integration, adding to the overall cost and time commitment. These factors may deter smaller companies from adopting these solutions or lead to underutilization of their full capabilities, limiting the market's overall growth potential. Additionally, the continuous updates required to keep the software aligned with changing customer behaviors and technologies can further increase operational burdens for businesses.
Difficulty in Measuring ROI and Advocacy Impact
Another challenge in the Customer Advocacy Software Market is the difficulty businesses face in accurately measuring the return on investment (ROI) and the overall impact of their advocacy programs. While customer advocacy is recognized as a powerful tool for driving organic growth, quantifying its direct influence on revenue and customer acquisition can be challenging. Unlike traditional marketing channels with clear metrics, such as click-through rates or conversion rates, the outcomes of advocacy programs are often less tangible. This can make it difficult for businesses to justify the investment in customer advocacy software, especially in industries with long sales cycles or complex purchasing decisions. Additionally, tracking the long-term impact of advocacy efforts, such as customer retention or lifetime value, requires sophisticated analytics tools and comprehensive data collection, which some companies may lack. Without clear and measurable outcomes, businesses may struggle to fully embrace customer advocacy platforms, slowing market adoption and growth. Overcoming this challenge requires both improved measurement capabilities and clear strategies for aligning advocacy initiatives with broader business goals.
Market Opportunities
The increasing prevalence of digital channels and the growing influence of social media present significant opportunities in the Customer Advocacy Software Market. As more consumers engage with brands online and seek peer recommendations, companies can leverage customer advocacy software to amplify the voices of satisfied customers across multiple digital platforms. Social media, in particular, offers a powerful avenue for brands to connect with potential advocates and foster stronger customer relationships. By capitalizing on the visibility and reach that digital channels provide, businesses can tap into new audiences, enhance brand reputation, and drive organic growth through authentic customer testimonials and referrals. This growing trend towards digital engagement is creating fertile ground for the expansion of customer advocacy solutions, particularly in sectors such as e-commerce, retail, and technology.
Another promising opportunity lies in the integration of artificial intelligence (AI) and machine learning to drive personalized customer advocacy experiences. With the ability to analyze customer behaviors, preferences, and past interactions, AI-powered advocacy platforms can deliver tailored content and recommendations, increasing customer satisfaction and loyalty. Businesses can use this data-driven approach to identify key advocates and customize their engagement strategies, ultimately enhancing advocacy effectiveness. Additionally, AI-driven insights allow companies to optimize their marketing campaigns and identify areas for improvement, creating a more personalized and impactful customer advocacy experience. This growing trend of AI adoption opens doors for innovation and differentiation in the customer advocacy software market, allowing businesses to scale and enhance their advocacy programs.
Market Segmentation Analysis:
By Component
The Customer Advocacy Software Market is segmented into software and services. The software segment dominates, driven by the rising demand for advanced platforms that enable businesses to manage customer referrals, reviews, and advocacy campaigns. The services segment, including consulting, implementation, and support, also plays a key role in ensuring successful adoption and optimization of advocacy programs.
By Deployment
Deployment models are divided into cloud-based and on-premise solutions. Cloud-based deployment leads the market due to its scalability, flexibility, and lower upfront costs, making it appealing to businesses of all sizes. On-premise solutions, though less popular, are favored by organizations requiring greater control over data security and compliance, particularly in regulated industries.
By Organization Size
The market is further segmented by organization size into small and medium-sized enterprises (SMEs) and large enterprises. Large enterprises dominate due to their substantial resources and complex customer advocacy needs, while SMEs are increasingly adopting customer advocacy software to enhance customer loyalty and drive growth, thanks to affordable cloud-based solutions.
Segments:
Based on Component
- Software
- Services
Based on Deployment
- On-Premises
- Cloud
Based on Organization Size
- Small and Medium Enterprises
- Large Enterprises
Based on End-User
- Retail
- BFSI
- Healthcare
- IT and Telecommunications
- Manufacturing
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America is expected to hold the largest market share in the Customer Advocacy Software Market, accounting for 38% in 2024. The region’s dominance is driven by the early adoption of advanced technologies, a strong focus on customer experience, and the presence of leading customer advocacy software providers. In the United States and Canada, businesses across various industries, including retail, e-commerce, and technology, are increasingly investing in customer advocacy solutions to enhance customer loyalty and brand recognition. The growing use of social media and digital platforms in this region also supports the demand for advocacy software, as companies seek to harness the power of customer referrals and reviews. Moreover, North America's high digital literacy and sophisticated IT infrastructure contribute to the rapid growth of cloud-based advocacy solutions.
Europe
Europe is expected to capture 25% of the market share in 2024, driven by the increasing focus on customer-centric strategies across industries. Countries such as the United Kingdom, Germany, and France are leading the adoption of customer advocacy software as businesses prioritize improving customer satisfaction and fostering loyalty. The European market is witnessing a strong demand for cloud-based advocacy platforms due to their flexibility and cost-effectiveness. Additionally, the region's strict data protection regulations, such as the General Data Protection Regulation (GDPR), are prompting businesses to adopt more secure and compliant customer advocacy solutions. As companies in Europe continue to invest in customer experience management, the market for advocacy software is expected to grow steadily.
Asia-Pacific
Asia-Pacific is projected to witness the fastest growth in the Customer Advocacy Software Market, with an estimated market share of 20% in 2024. The region’s growth is driven by the expanding digital economy and the increasing adoption of cloud-based solutions. Countries such as China, India, and Japan are experiencing a surge in e-commerce and retail sectors, where customer advocacy is becoming crucial for driving brand loyalty and customer engagement. The growing number of small and medium-sized enterprises (SMEs) in Asia-Pacific is also contributing to the demand for affordable and scalable advocacy platforms. Additionally, the rising influence of social media and mobile commerce in the region is encouraging businesses to adopt customer advocacy software to capitalize on the growing consumer base.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa (MEA) are expected to account for a smaller market share, collectively capturing around 17% in 2024. In Latin America, countries like Brazil and Mexico are increasingly adopting customer advocacy solutions as businesses recognize the importance of customer loyalty and brand advocacy in driving sales. Meanwhile, the MEA region is seeing gradual adoption, driven by growing digitalization and the expansion of retail and e-commerce sectors. However, challenges such as limited technological infrastructure and lower digital adoption rates may hinder faster growth in these regions. Nevertheless, as digital transformation continues to unfold, the Customer Advocacy Software Market in these regions is expected to expand over time.
Key Player Analysis
- Bambu by Sprout Social
- Zuberance
- Customer Advocacy
- GaggleAMP
- Crowdly
- Sociabble
- Ambassify
- Advocately
- PostBeyond
- Influitive
Competitive Analysis
The Customer Advocacy Software Market is highly competitive, with leading players continuously innovating to gain market share. Companies such as Influitive, Advocately, Crowdly, Zuberance, Ambassify, PostBeyond, Bambu by Sprout Social, Customer Advocacy, GaggleAMP, and Sociabble are at the forefront, offering robust solutions designed to enhance customer engagement, loyalty, and brand advocacy. These companies differentiate themselves by integrating AI and data analytics to personalize customer interactions, streamline advocacy processes, and improve ROI measurement. Cloud-based platforms are also a significant focus, as they offer scalability and flexibility for businesses of all sizes. For instance, Advocately provides cloud-based solutions that enable companies to scale operations and collaborate remotely. To stay competitive, these players are enhancing their features with social media integrations, gamification elements, and enhanced reporting capabilities, making it easier for organizations to track and measure advocacy success. The market is expected to continue evolving with technological advancements and increasing demand for more personalized, data-driven advocacy solutions.
Recent Developments
- In June 2023, Champion, a platform focused on second-order revenue, launched to transform enterprise customer advocacy. The platform utilizes artificial intelligence to identify, activate, and track customer champions, enabling companies to unlock growth by leveraging the power of their most loyal advocates and power users.
- In December 2023, IZEA Worldwide, Inc. acquired Zuberance, a pioneering advocate marketing software platform. This acquisition strengthens IZEA’s suite of software solutions by incorporating user-generated content and performance-based creator compensation capabilities.
- In March 2024, aDolus Technology Inc., a global leader in software intelligence for critical infrastructure, partnered with Exiger, the market-leading supply chain and third-party risk AI company. The partnership aims to provide extensive visibility into risks within the software supply chain.
- In January 2024, Quorum, a leading provider of public affairs software, launched an updated version of its grassroots advocacy platform, Quorum Grassroots. The new version introduces intuitive workflows and AI-powered features designed to enhance the advocate experience and drive greater engagement, allowing public affairs professionals to amplify the issues they care about.
- In June 2023, Champion also unveiled Venture Studio High Alpha, a platform that helps companies identify, activate, and track their strongest advocates and power users. This initiative enables businesses to drive growth, shorten sales cycles, and generate second-order revenue-new sales powered by their existing users.
Market Concentration & Characteristics
The Customer Advocacy Software Market is moderately concentrated, with a mix of established players and emerging companies. While a few major players dominate the market, there is significant room for innovation, especially from newer entrants offering niche solutions or region-specific offerings. The market is characterized by rapid technological advancements, such as the integration of AI, automation, and cloud-based platforms, which are driving competition and expanding opportunities for businesses to enhance customer engagement and loyalty. Leading companies focus on delivering personalized customer experiences through advanced data analytics and social media integrations. As customer-centric strategies continue to gain importance, the market is expected to witness further consolidation, with larger companies acquiring smaller firms to enhance their capabilities and broaden their market presence. Overall, the Customer Advocacy Software Market is dynamic, evolving to meet the increasing demand for efficient, scalable, and data-driven advocacy solutions.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment, Organization Size, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Customer Advocacy Software Market is expected to experience significant growth, reaching over USD 1.45 billion by 2032.
- Increasing reliance on customer-centric strategies will continue to drive the demand for advocacy software across industries.
- The integration of AI and machine learning technologies will enhance personalization, automate processes, and improve engagement.
- Cloud-based solutions will dominate the market due to their scalability, cost-effectiveness, and flexibility.
- Social media’s influence on customer purchasing decisions will increase the need for platforms that amplify the voices of advocates.
- Small and medium-sized enterprises (SMEs) will increasingly adopt customer advocacy software as solutions become more affordable and scalable.
- The rising importance of data analytics will push companies to invest in tools that measure and optimize the impact of advocacy programs.
- North America will remain the largest market, but the Asia-Pacific region will witness the fastest growth due to expanding digital economies.
- Growing regulatory concerns, such as GDPR, will drive demand for secure, compliant customer advocacy platforms.
- The market will see further consolidation, with major players acquiring smaller firms to expand capabilities and market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Customer Advocacy Software Market?
What factors are driving the growth of the Customer Advocacy Software Market?
What are the key segments within the Customer Advocacy Software Market?
What are some challenges faced by the Customer Advocacy Software Market?
Who are the major players in the Customer Advocacy Software Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Customer Advocacy Software Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Customer Advocacy Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 724 million → 2032: USD 1,453.23 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Customer Advocacy Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Customer Advocacy Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Customer Advocacy Software Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Customer Advocacy Software Market Drivers
- 3.3 Customer Advocacy Software Market Restraints & Challenges
- 3.4 Customer Advocacy Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Customer Advocacy Software Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Customer Advocacy Software Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Customer Advocacy Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Customer Advocacy Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Customer Advocacy Software Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Customer Advocacy Software. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Customer Advocacy Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Customer Advocacy Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Customer Advocacy Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Customer Advocacy Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Customer Advocacy Software
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Customer Advocacy Software Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Customer Advocacy Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Customer Advocacy Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Customer Advocacy Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Customer Advocacy Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Customer Advocacy Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Customer Advocacy Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Customer Advocacy Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
