
Market Overview:
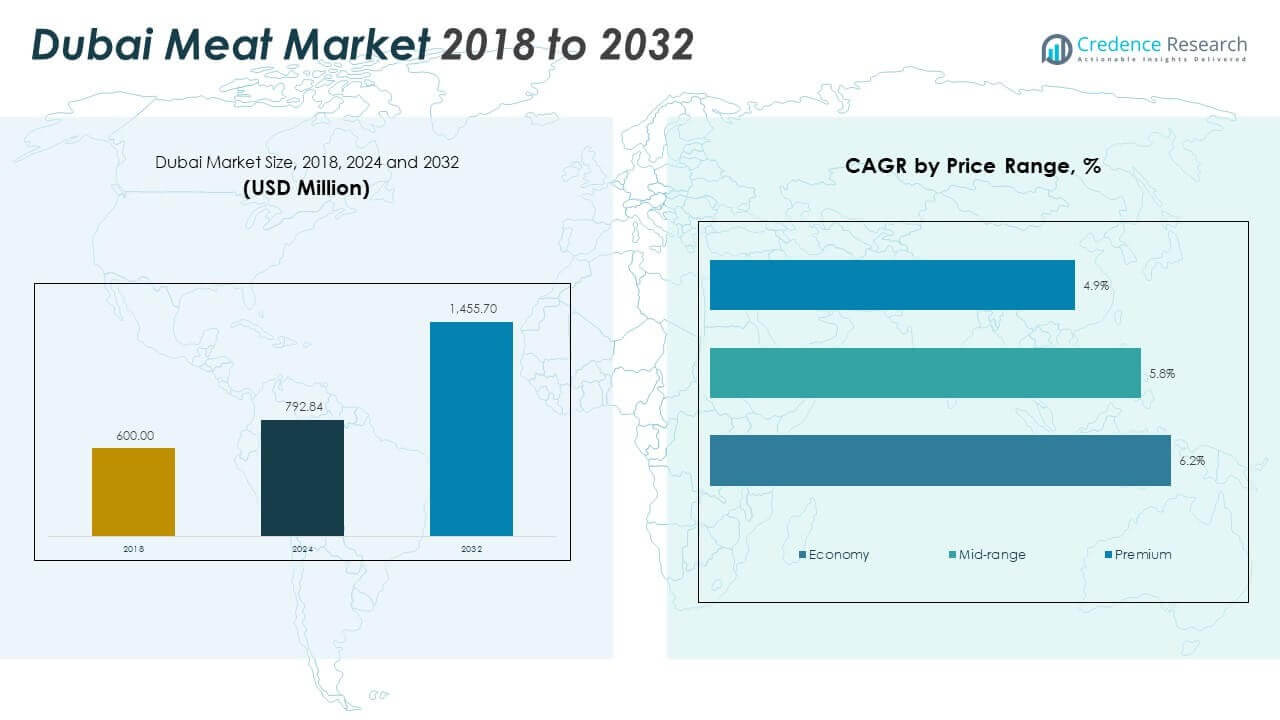
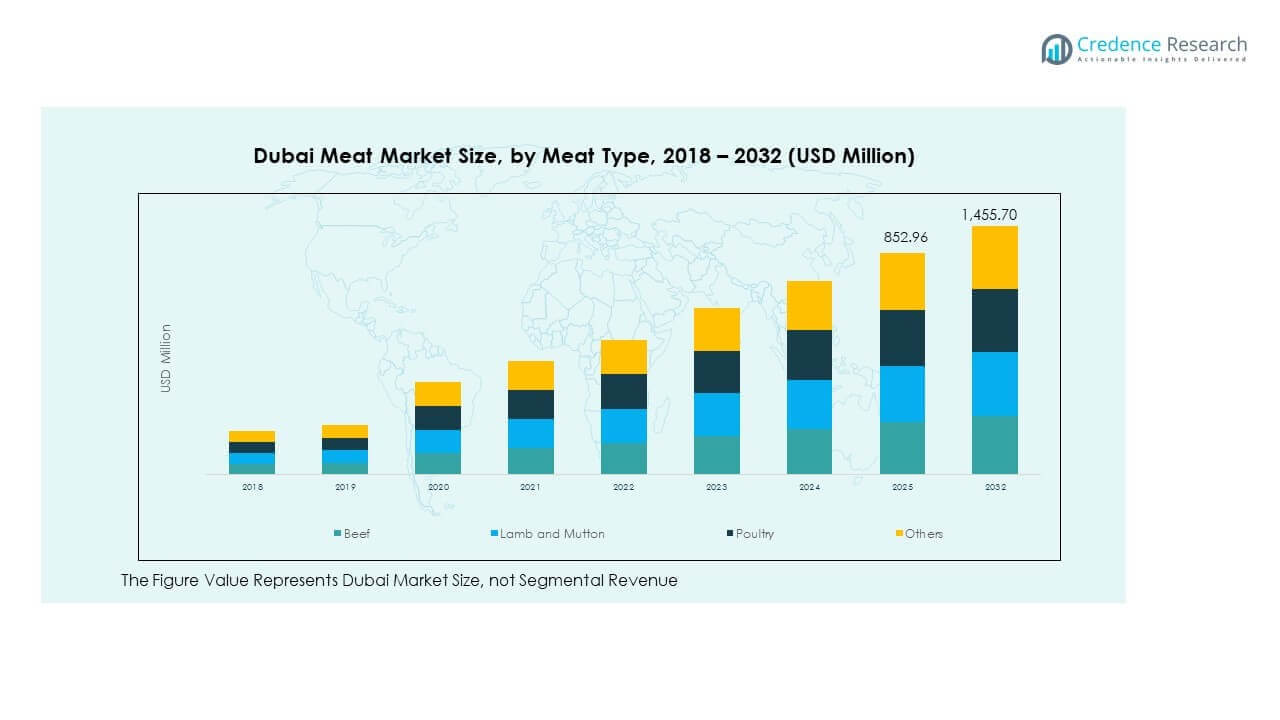
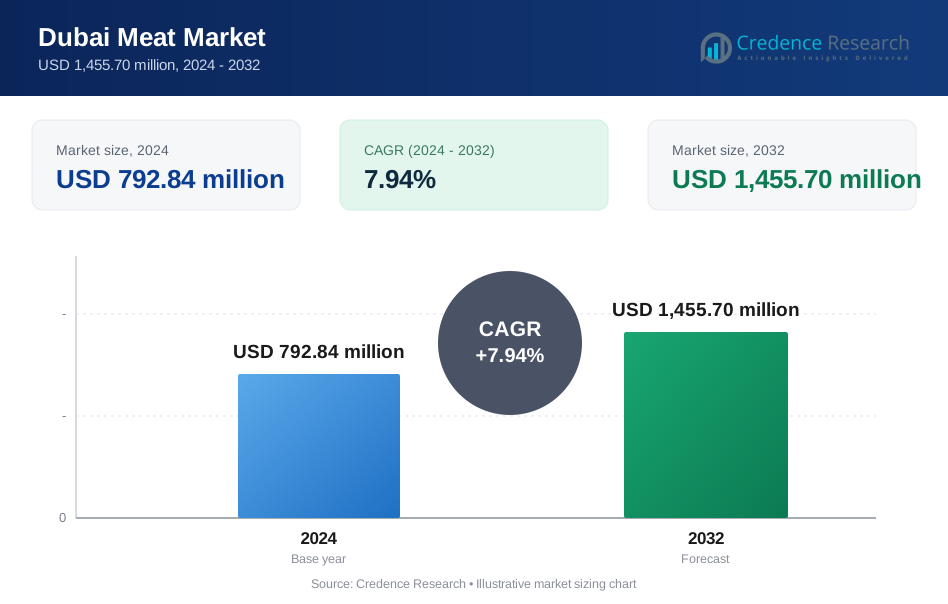
The Dubai Meat Market size was valued at USD 600.00 million in 2018 to USD 792.84 million in 2024 and is anticipated to reach USD 1,455.70 million by 2032, at a CAGR of 7.94% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dubai Meat Market Size 2024 | USD 792.84 Million |
| Dubai Meat Market, CAGR | 7.80% |
| Dubai Meat Market Size 2032 | USD 1,455.70 Million |
Strong population growth, a robust tourism sector, and high per capita meat consumption are major demand drivers. The market thrives on rising preference for halal-certified and traceable meat products among diverse expatriate communities. Demand from restaurants, hotels, and fast-food chains has increased significantly. Retail expansion and digital ordering platforms have improved access to fresh and frozen meat. Government-led food security strategies and import diversification have stabilized supply chains. Premium and organic meat segments are also gaining traction. Dubai’s central role in GCC meat trade continues to attract global suppliers. The market benefits from a balanced mix of domestic demand and re-export potential.
Dubai city holds the largest market share due to its population density, high-income households, and retail infrastructure. Coastal districts and central business zones drive demand through hospitality and foodservice channels. Northern areas, including Deira and Al Qusais, support value and mid-range consumption through traditional retail. Emerging areas like Dubai South and surrounding suburbs show increasing household and institutional demand. Neighboring emirates such as Sharjah and Ajman are gradually contributing to interlinked meat supply activity. The city’s logistics and import ecosystem helps maintain stable distribution to all subregions.
Market Insights
- The Dubai Meat Market size increased from USD 600.00 million in 2018 to USD 792.84 million in 2024 and is projected to reach USD 1,455.70 million by 2032, growing at a CAGR of 7.94%.
- Dubai City holds the largest share at 58% due to high-income households, foodservice density, and retail infrastructure, followed by Northern Dubai at 24% driven by working-class demand and traditional retail, and emerging suburbs contributing 18% with rising residential activity.
- Suburban districts like Dubai South and Silicon Oasis are the fastest-growing regions, supported by population shifts, new housing, and expanding retail distribution networks.
- Among price segments, premium meat holds the fastest CAGR at 6.2%, driven by tourism, high-end retail, and specialty cuts favored in fine dining.
- Mid-range meat follows with a 5.8% CAGR, supported by urban professionals and dual-income households demanding both affordability and quality.
Market Drivers
Rising Demand for Halal-Certified Meat Among Local and Expat Communities
Dubai hosts a diverse population with strong preferences for halal-certified meat. Consumers from South Asia, the Middle East, and North Africa prioritize halal standards. The government enforces strict halal compliance to build buyer trust. Dubai Meat Market benefits from these regulations and cultural preferences. Leading suppliers focus on halal traceability across the supply chain. Hotels and restaurants demand high-quality cuts that meet halal norms. This segment supports both retail and foodservice channels. Certification programs build brand value for importers. Product variety expands in frozen, fresh, and processed halal formats. It positions Dubai as a trusted halal meat destination.
Increasing Meat Consumption Driven by Tourism and Hospitality Growth
Dubai’s strong tourism sector fuels year-round demand for red and white meat. Hotels, restaurants, and catering firms purchase bulk quantities of beef, lamb, and poultry. Tourists from Europe and Asia boost seasonal consumption trends. The Dubai Meat Market captures this volume through foodservice partnerships. Events and festivals raise short-term demand for premium cuts. Culinary tourism has pushed demand for exotic and imported meats. Meat suppliers align with hotel chains to secure recurring orders. Menu diversification across cuisines creates opportunities for niche meat products. It benefits from steady growth in travel and food service recovery. Meat imports remain essential for volume support.
- For example, in 2023, JBS S.A. expanded its technology initiatives with advanced meat processing systems at select global facilities, supporting quality control and export operations that serve key markets including the Middle East.
Expanding Retail Infrastructure and Supermarket Chains Stimulating Volume Uptake
Modern retail formats such as Carrefour, Lulu, and Spinneys scale meat accessibility. These supermarkets offer fresh, chilled, and ready-to-cook meat formats. In-store butcheries allow consumers to request specific cuts and packaging. The Dubai Meat Market sees value growth through this organized channel. Promotions, discounts, and loyalty programs encourage frequent purchases. Cold chain logistics maintain product quality across the supply chain. Retail expansion into residential areas drives consumption at the household level. Domestic consumption increases due to lifestyle changes and rising affluence. It benefits from year-round availability of diverse product options.
- For example, Lulu Hypermarket enhanced its retail operations with advanced inventory technologies across key stores, improving real‑time tracking of chilled meat and other perishable categories by 2024.
Government Food Security Strategy Supporting Meat Supply Diversification
Dubai's authorities have prioritized food security to reduce external dependency. Public-private partnerships enhance domestic livestock production, albeit on a small scale. Strategic meat reserves help stabilize prices during disruptions. The Dubai Meat Market aligns with these initiatives to ensure reliable supply. Import diversification mitigates risks tied to one or two major source countries. Regulatory clarity attracts international meat exporters to the UAE. Licensing and inspection processes maintain safety and hygiene standards. Subsidy support and investment zones enable smoother imports and distribution. It supports long-term stability in the meat value chain.
Market Trends
Rising Popularity of Organic and Antibiotic-Free Meat Products Among Health-Focused Consumers
Urban consumers in Dubai increasingly choose clean-label meat products. Health awareness drives demand for hormone-free, antibiotic-free, and organic-certified meat. The Dubai Meat Market adapts by sourcing premium-grade items from certified farms. Retailers dedicate shelves to wellness-focused protein choices. High-income groups show interest in animal welfare and traceability. Digital labeling helps validate product origin and rearing methods. Butchers and gourmet stores respond to this trend with curated offerings. Imports from Europe and Australia fulfill these standards. It gains traction among younger and educated buyers.
- For example, Al Jazira Poultry Farms is one of the UAE’s leading egg producers and operates under HACCP-certified food safety systems. The company supplies fresh eggs across Dubai and follows regulated hygiene and production standards in its local facilities.
Digital Meat Delivery Platforms Expanding Urban Consumer Access and Convenience
Online grocery platforms offer fresh meat delivery with precise cut and weight options. Consumers prefer digital ordering for doorstep convenience and time savings. The Dubai Meat Market adapts by integrating with e-commerce grocery partners. Players like Kibsons, Noon, and Talabat promote chilled and frozen selections. Meat-specific platforms offer subscription-based or one-time purchase options. Cold chain integrity is maintained through real-time logistics tracking. Discounts and combo packs increase buyer retention. Working professionals rely on mobile apps to schedule meat deliveries. It opens access beyond traditional retail zones.
Surge in Value-Added and Processed Meat Products Across Retail and Horeca Channels
Ready-to-cook meat products gain popularity due to fast-paced lifestyles. Marinated, pre-sliced, and seasoned options attract younger consumers. Foodservice brands rely on processed meats for consistency and efficiency. The Dubai Meat Market supports value addition with packaging and flavor innovations. Retailers introduce sausages, kebabs, and burger patties in ready packs. Frozen processed meat also penetrates institutional catering and airlines. Time-saving features drive repeat purchases in modern households. Local processors experiment with Middle Eastern and international flavor blends. It diversifies supply and builds brand stickiness.
Ethnic and Gourmet Meat Cuts Seeing Higher Uptake Among Culinary Enthusiasts
Ethnic cuisines boost demand for specific meat parts and cuts. Filipino, Indian, and Levantine cuisines shape consumer preferences. The Dubai Meat Market reflects this diversity with expanded butcher offerings. Gourmet restaurants introduce imported game meats and rare cuts. Home chefs experiment with brisket, short ribs, and wagyu steaks. Retailers import specialty meats from Argentina, South Africa, and New Zealand. Butchers personalize cuts to suit unique cooking styles. Awareness through cooking shows and food blogs boosts uptake. It widens product variety in both premium and ethnic meat sections.
- For example, Al Ain Farms Group distributes premium meat cuts and specialty imports to major Dubai retailers, supporting demand for gourmet and ethnic products through its established supply network.
Market Challenges Analysis
Heavy Dependence on Imports Creates Volatility in Cost and Supply Stability
Dubai lacks large-scale domestic meat production due to climate and space constraints. The Dubai Meat Market depends heavily on imports from Australia, Brazil, and India. Any disruption in global supply chains or export bans directly affects availability. Currency fluctuations and freight charges cause pricing instability. Import documentation, port delays, and geopolitical tensions increase uncertainty. It also exposes the market to sanitary regulation shifts in supplier nations. Local players face challenges in forecasting and inventory control. Maintaining consistent quality across batches remains complex. High dependency makes long-term planning more difficult for small retailers.
Shifting Consumer Preferences Demand Rapid Adaptation From Traditional Suppliers
New buyer segments prefer plant-based proteins and flexitarian diets. Traditional meat suppliers must rebrand to remain relevant in evolving demand cycles. The Dubai Meat Market faces margin pressures as health-focused alternatives increase. Premiumization demands raise costs for traceable and ethically sourced meats. Retailers must manage diverse inventory without wastage. Digital buyers expect seamless ordering and real-time stock updates. Butchers face labor shortages with skills required for customization. Training and digitization need upfront investment for modernization. It forces suppliers to revamp sourcing, marketing, and delivery strategies.
Market Opportunities
Expansion into Specialty and Gourmet Meat Segments Offers Higher Margins
Premium cuts, grass-fed beef, and exotic meats attract high-income groups and tourists. The Dubai Meat Market can expand revenue through curated offerings. Partnerships with gourmet stores and fine-dining outlets support brand elevation. Custom butchery and aged meats provide differentiation in a saturated space. Process innovation in packaging and marination unlocks value-added sales. It opens access to affluent segments seeking exclusivity.
Regional Export and Re-Export Potential Strengthens Dubai’s Role as a Trade Hub
Dubai's port and logistics infrastructure support meat re-export to GCC and Africa. The Dubai Meat Market can leverage Jebel Ali’s efficiency to boost cross-border sales. Demand in neighboring regions gives scope for volume scale-up. Export compliance and halal standards ensure smooth access to Islamic countries. It creates long-term opportunities for local distributors and global brands.
Market Segmentation Analysis
Meat Type Segment Overview
The Dubai Meat Market offers a broad range of meat products, with poultry leading due to its affordability and widespread use in quick-service and home meals. Beef holds a strong position across hotels and gourmet food chains, with premium cuts driving value. Lamb and mutton remain essential in traditional and festive cuisine, especially among South Asian and Middle Eastern communities. Other meats, including turkey and duck, cater to niche international segments and high-end dining. The market relies heavily on imports to meet demand across all categories. It continues to support variety to serve diverse resident and tourist preferences.
- For example, Al‑Ghurair Foods is developing a large‑scale poultry production facility in Khalifa Economic Zones Abu Dhabi (KEZAD), aimed at expanding capacity and supporting UAE protein supply chains. The project reflects ongoing investment in modern infrastructure to meet rising demand for locally produced poultry products.
Application Segment Insights
Applications in the Dubai Meat Market span across both residential and commercial sectors. Household consumption accounts for regular, retail-level demand across income groups. Restaurants and foodservice operators drive bulk purchases and maintain high turnover, especially in central Dubai. Fast food chains depend on standardized poultry and processed cuts, supporting volume-based imports. Institutional food services, including schools and hospitals, focus on safety and nutrition standards. Tourist and hospitality industries demand a mix of premium and specialty meat to cater to global palates. It enables strong market performance across both everyday and occasion-driven meat consumption.
Price Range Analysis
The Dubai Meat Market is segmented into economy, mid-range, and premium meat categories. Economy meat appeals to price-conscious shoppers and bulk institutional buyers. Mid-range meat sees growing traction among middle-income residents seeking a balance of quality and price. Premium meat caters to affluent consumers, tourists, and fine dining establishments. This segment includes grass-fed beef, organic poultry, and aged lamb. Specialty offerings with origin certifications gain preference in high-end retail and gourmet restaurants. It allows the market to tap into multiple consumption tiers while maintaining diversity in pricing and quality.
Distribution Channel Dynamics
Modern retail formats drive the largest share of meat distribution in Dubai. Supermarkets and hypermarkets dominate due to convenience, cold-chain infrastructure, and wide assortment. Online platforms are gaining traction through home delivery and product customization features. Butcher shops retain loyal customers seeking fresh cuts and ethnic meat preferences. Convenience stores serve quick and last-minute purchases but remain limited in meat variety. Other channels include hotels, caterers, and institutional buyers operating through wholesale partnerships. The Dubai Meat Market leverages this multi-channel approach to reach consumers efficiently across different touchpoints.
- For example, Cold‑chain improvements in the UAE help maintain quality and safety for both local meat production and imported supplies throughout distribution. These logistics upgrades support broader availability of fresh and frozen meat across retail and foodservice channels in 2025.
Segmentation
By Meat Type
- Beef
- Lamb and Mutton
- Poultry
- Others
By Application
- Household Consumption
- Restaurants and Foodservice
- Fast Food Chains
- Institutional Food Service
- Tourist and Hospitality Industry
By Price Range
- Economy Meat
- Mid-Range Meat
- Premium Meat
By Distribution Channel
- Online
- Supermarket/Hypermarket
- Convenience Stores
- Butcher Shops
- Others
Regional Analysis
Dubai City – Core Commercial and Residential Demand Hub (Approx. 58% Market Share)
Dubai city remains the primary consumption hub in the Dubai Meat Market, contributing nearly 58% of total market revenue. The central and southern districts, including Business Bay, Al Barsha, and Downtown, exhibit high meat consumption across households, restaurants, and hotels. Retail chains operate dense store networks in these zones, ensuring strong distribution efficiency. Tourist-heavy zones such as Jumeirah and Marina further drive premium and gourmet meat demand. Foodservice operators maintain bulk procurement for dine-in, catering, and delivery formats. It benefits from the city's large population density, diversified cuisine landscape, and rising middle-income spending power.
Northern Dubai and Industrial Zones – Mid-Range and Institutional Demand (Approx. 24% Market Share)
Northern Dubai, including areas like Deira and Al Qusais, holds nearly 24% market share, supported by working-class residents and small-scale restaurants. The region shows steady demand for mid-range and economy meat products. Industrial zones and labor accommodations also contribute to institutional foodservice requirements. Wholesalers and butcher shops are more active in these areas, especially near traditional wet markets. Distribution focuses on frozen and bulk-format meats to control cost. The Dubai Meat Market supports this segment through import volume and price-efficient supply chains. It sees stable year-round demand with lower fluctuations.
Emerging Suburbs and Outer Emirates – Growth-Driven Peripheral Demand (Approx. 18% Market Share)
Suburban districts such as Dubai South, Silicon Oasis, and new residential developments contribute around 18% of the market. Demand in these areas is expanding due to ongoing housing projects and population migration. Supermarkets and e-commerce platforms are increasing coverage in these localities. The Dubai Meat Market sees opportunity in scaling distribution for mid-income groups moving to these zones. Adjacent emirates like Sharjah and Ajman also show meat market linkages via inter-emirate trade. It creates room for regional logistics hubs and last-mile cold chain expansion to serve these emerging territories.
Key Player Analysis
- JBS S.A. (Brazil)
- Tyson Foods (USA)
- Cargill Meat Solutions (USA / Global)
- NH Foods (Japan)
- Teys Australia (Australia)
- Hormel Foods Corporation (United States)
- Danish Crown A/S (Denmark)
- Minerva Foods (Brazil)
- Thomas Foods International (Australia)
- Marfrig Global Foods (Brazil)
- Alliance Group Ltd. (New Zealand)
- Silver Fern Farms (New Zealand)
- ANZCO Foods (New Zealand)
- JBS Australia (Australia)
- BRF S.A. (Brazil)
- Pilgrim’s Pride Corporation (U.S.)
- Charoen Pokphand Foods (CPF) (Thailand)
- Al Islami Foods (UAE)
- Al Kabeer Group (UAE)
- Midfield Group (Australia)
Competitive Analysis
The Dubai Meat Market is highly competitive, with strong participation from multinational importers, domestic distributors, and specialized butchery brands. Leading players focus on product variety, halal certification, and freshness to gain retail shelf space. Supermarket chains collaborate with international exporters from Brazil, Australia, and India to ensure regular supply. Premium brands compete on organic, grass-fed, and traceable meat offerings. Fast food and foodservice channels maintain long-term contracts with bulk suppliers for consistency and cost efficiency. Digital-first players also gain ground by offering doorstep delivery and customizable cuts. Local butcher shops retain market share through personal service and ethnic product alignment. Branding, logistics strength, and cold chain reliability determine competitive advantage. The Dubai Meat Market encourages new entrants through import facilitation, but compliance with food safety laws remains stringent. It drives companies to invest in storage, packaging, and certification infrastructure to meet regulatory benchmarks. Competitive dynamics continue to evolve with rising consumer expectations and retail consolidation.
Recent Developments
- In August 2025, The Organic Meat Company Limited qualified to supply Carrefour retail networks across the UAE, expanding its distribution of frozen boneless beef into major supermarket chains in Dubai and strengthening meat product availability in the region.
- In July 2025, a strategic partnership was announced between leading UAE meat importers and African meat producers to open new export channels, enabling premium African meat products to enter the Dubai market and diversify supply sources.
Report Coverage
The research report offers an in-depth analysis based on Meat Type, Application, Price Range and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising demand for premium halal-certified meat will shape product portfolios across retail and foodservice sectors.
- Tourism recovery and ongoing hotel expansion will increase meat consumption in hospitality and catering channels.
- E-commerce meat delivery platforms are expected to capture higher market share with growing digital adoption.
- Investment in cold chain logistics will improve product quality, shelf life, and geographic penetration.
- Demand for organic, antibiotic-free, and clean-label meat products will expand among health-conscious buyers.
- Processed and ready-to-cook meat formats will gain traction with urban households and busy professionals.
- Fast food and quick-service restaurant chains will remain major buyers of poultry and processed meat items.
- Government initiatives on food security and import diversification will reduce supply chain dependency risks.
- Suburban and emerging districts will drive new demand due to residential and infrastructure development.
- Strategic partnerships between importers and retail giants will strengthen distribution efficiency and product availability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Dubai Meat Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Dubai Meat Market projected to grow between 2024 and 2032?
Which Dubai Meat Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dubai Meat Market?
Who are the leading companies in the Dubai Meat Market?
Which region commanded the largest share of the Dubai Meat Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Dubai Meat Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Dubai Meat Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 792.84 million → 2032: USD 1,455.70 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Dubai Meat Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Dubai Meat Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Dubai Meat Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Dubai Meat Market Drivers
- 3.3 Dubai Meat Market Restraints & Challenges
- 3.4 Dubai Meat Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Dubai Meat Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Dubai Meat Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Dubai Meat category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Dubai Meat Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Dubai Meat Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Dubai Meat market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Dubai Meat Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Dubai Meat Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Dubai Meat Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Dubai Meat (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Dubai Meat Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Dubai Meat Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Dubai Meat Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Dubai Meat Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Dubai Meat Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Dubai Meat Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Dubai Meat Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Dubai Meat Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Dubai Meat Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
