
Market Overview
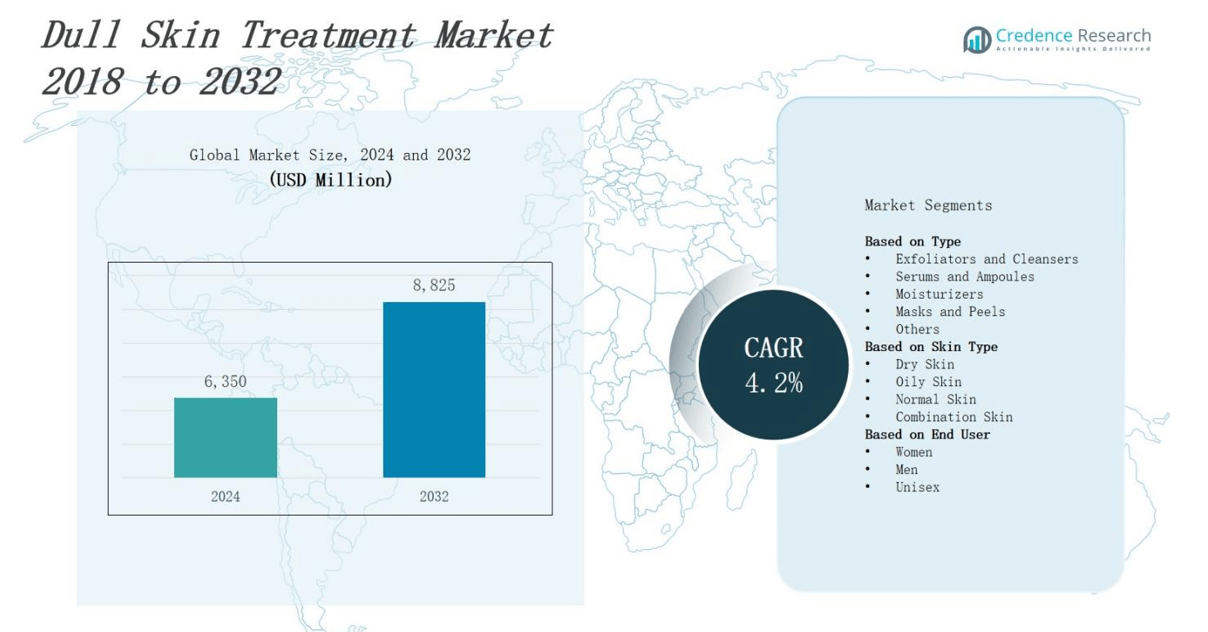
The dull skin treatment market is projected to expand from USD 6,350 million in 2024 to USD 8,825 million by 2032, at a CAGR of 4.2%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dull Skin Treatment Market Size 2024 | USD 6,350 million |
| Dull Skin Treatment Market, CAGR | 4.2% |
| Dull Skin Treatment Market Size 2032 | USD 8,825 million |
Rising consumer awareness of skin health and growing demand for radiant complexions drive the global dull skin treatment market. Social media and influencer endorsements propel adoption of exfoliating products, brightening serums, and professional therapies. Advancements in active ingredients such as vitamin C, alpha hydroxy acids, and plant‑derived antioxidants enhance efficacy. Rapid expansion of e‑commerce platforms and direct‑to‑consumer models increases accessibility. Consumers favor personalized regimens guided by AI‑powered skin analysis tools. Demand for noninvasive, at‑home devices like LED masks and microdermabrasion kits continues to grow. Natural and clean‑label formulations gain traction as sustainability concerns influence purchasing decisions and support market growth.
Geographical analysis of the dull skin treatment market highlights regional performance and players. North America drives 35% share, dominated by L’Oréal S.A. and Procter & Gamble Co. Europe holds 30%, anchored by Unilever PLC and Estée Lauder Companies Inc. Asia‑Pacific captures 20% with Shiseido Company Limited and Kao Corporation leading demand. Latin America accounts for 10% through Beiersdorf AG and Avon Products Inc. Middle East & Africa claims 5% as Amway Corporation, Johnson & Johnson, Revlon Inc., Coty Inc., and Clarins Group expand distribution. It adapts strategies to preferences and regulations.
Market Insights
- The market will grow from USD 6,350 million in 2024 to USD 8,825 million by 2032 at 4.2% CAGR.
- Consumer demand for radiant complexions drives exfoliators, brightening serums, and professional therapies.
- AI‑powered skin analysis and virtual consultations personalize regimens and boost adoption rates.
- E‑commerce platforms and subscription models expand global accessibility and repeat purchases.
- LED masks, microdermabrasion kits, and at‑home devices deliver noninvasive treatment convenience.
- Natural extracts, clean‑label formulations, and eco‑friendly packaging align with sustainability goals.
- North America leads with 35% share, followed by Europe 30%, Asia‑Pacific 20%, Latin America 10%, and MEA 5%.
Market Drivers
Heightened Consumer Focus on Skin Radiance and Health
Growing consumer demand for evening tone and vibrant complexions fuels product expansion. It targets dullness by promoting exfoliating cleansers and vitamin C serums. The dull skin treatment market innovates with combinations of antioxidants and mild acids. Social media advocates demonstrate benefits and teach regimen steps. Dermatologists prescribe chemical peels and microdermabrasion for visible improvements. It integrates AI-based skin assessments to refine recommendations.
- For instance, L’Oréal’s SkinConsult AI uses deep learning algorithms on millions of facial images to analyze skin conditions like pigmentation and recommend personalized antioxidant and mild acid-based treatments.
Technological Innovation Enhances Treatment Efficacy and Access
Advances in ingredient science support formulation of stable vitamin C derivatives and plant-derived antioxidants. It incorporates microencapsulation techniques to preserve potency until application. The dull skin treatment market leverages LED devices and microcurrent tools for at-home use. Brands deploy AI-driven diagnostics to customize regimen selection. E‑commerce platforms expand reach through virtual consultations and subscriptions. Manufacturers invest in research validating efficacy through clinical studies.
- For instance, companies like BASF have expanded production capacity for microencapsulated ingredients such as omega-3 powders used in functional skin/nutritional products, ensuring consistent supply and quality for advanced formulations.
Demand for Clean‑Label Formulations and Sustainability
Heightened consumer focus on ingredient transparency prompts brands to use natural extracts and minimal preservatives. It sources plant-derived actives and avoids synthetic dyes. The dull skin treatment market adopts eco-friendly packaging and cruelty‑free testing standards. Retailers showcase certifications like organic and vegan to build trust. Brands conduct audits to confirm chain integrity. Consumers reward companies that demonstrate responsibility. It aligns with sustainability initiatives globally.
Expansion of Professional Services and Regulatory Support
Dermatology clinics extend service offerings with combination therapies and consultations. It secures approvals for innovative actives through regulatory pathways. The dull skin treatment market benefits from simplified compliance with cosmetic safety standards in key regions. Manufacturers partner with medical professionals to validate product claims and deliver training. Retail chains integrate in-store skin analysis stations. It invests in professional education to support practitioner adoption.
Market Trends
Implementation of AI‑Driven Skin Analysis Platforms
Brands deploy AI diagnostics to tailor treatment plans based on individual skin metrics. It combines image recognition with data analytics to recommend exfoliants and serums. The dull skin treatment market witnesses growth of digital consultation services hosted by specialized platforms. Clinicians use machine learning models to identify pigmentation patterns and track progress. Companies partner with tech firms to refine algorithms and improve accuracy. Consumers experience more precise solutions that reduce guesswork in regimen selection.
- For instance, Perfect Corp's AI skin analysis tool, integrated by Cetaphil, allows consumers to upload selfies and receive detailed skin assessments along with tailored product recommendations for sensitive skin.
Expansion of At‑Home Device Adoption and Wearable Tech
It leverages handheld LED masks and microcurrent devices for use beyond clinical settings. Manufacturers integrate Bluetooth connectivity to sync devices with smartphone apps. Consumers use wearable patches infused with active ingredients to maintain glow throughout day. The dull skin treatment market sees increased demand for portable tools that deliver salon‑grade performance. Retailers bundle devices with curated product kits to enhance user convenience. It encourages consistent treatment routines by offering user feedback and progress tracking.
- For instance, BonPatch offers wearable patches infused with active ingredients like GHK-Cu, pomegranate extract, and green tea extract that support collagen production and skin hydration for up to 24 hours of continuous use.
Rise of Clean‑Label Formulations and Sustainable Practices
Consumers favor formulations that feature botanical extracts and free from synthetic dyes. It prioritizes transparency by listing full ingredient profiles on packaging and online. The dull skin treatment market adapts by sourcing fair‑trade and organic actives. Brands implement biodegradable containers and minimalistic design to reduce environmental impact. Certification by third‑party bodies boosts credibility for vegan and cruelty‑free claims. It builds loyalty by aligning brand values with consumer ethics and sustainability goals.
Growth of Omnichannel Sales and Subscription Models
E‑commerce platforms integrate virtual try‑on tools and personalized product recommendations. It shortens purchase cycles through curated subscription boxes that deliver treatments monthly. The dull skin treatment market experiences higher repeat purchases thanks to auto‑reorder options. Beauty retailers blend in‑store diagnostics with online follow‑ups to boost customer engagement. Brands launch DTC websites that offer exclusive bundles and loyalty rewards. It leverages data from sales channels to optimize inventory and tailor marketing strategies.
Market Challenges Analysis
Stringent Regulatory Compliance and Ingredient Stability Concerns
Brands must navigate diverse cosmetic and drug regulations across regions, complicating product launches. It conducts extensive safety and efficacy testing to meet varying requirements. The dull skin treatment market encounters inconsistent guidelines for active concentrations and claims. It allocates significant budgets to stability studies and preservative efficacy assessments. Regulatory bodies request clinical data to support brightening claims and ingredient tolerability. It labels formulations with full ingredient disclosures to maintain transparency. Manufacturers must update dossiers when authorities revise safety standards. It manages cross‑border labeling translation and adjusts packaging to satisfy local language and hazard communication standards. It negotiates with suppliers to secure high‑quality actives under new compliance frameworks. It monitors global policy shifts to anticipate deadlines and avoid market delays.
Intense Market Fragmentation and Consumer Skepticism
Thousands of brands flood online and brick‑and‑mortar channels, driving fierce competition on price and novelty. It struggles to differentiate genuine innovation from fleeting trends. The dull skin treatment market faces skepticism due to exaggerated claims and inconsistent results. It counters misinformation by partnering with dermatologists and publishing peer‑reviewed studies. Retailers train staff to recommend evidence‑backed solutions and manage expectations. It invests in consumer education campaigns that demonstrate product benefits through before‑and‑after data. It evaluates influencers and clinical endorsements to ensure credibility and guard against misrepresentation. It leverages targeted marketing to build trust and gather consumer feedback that refines product positioning.
Market Opportunities
Expansion into Emerging Regional Markets and Personalized Care Demand
Emerging markets in Asia‑Pacific and Latin America show rising demand for specialized skincare solutions. It leverages growing middle‑class spending power and digital adoption to introduce region‑specific formulations. The [dull skin treatment market] can tailor products to local skin types and climate conditions to improve efficacy. Brands extend distribution through cross‑border e‑commerce and local partnerships to drive penetration. Companies refine pricing strategies to balance affordability and margins. It taps into wellness tourism to offer treatment packages in medical spas. Dermatology clinics can form alliances with beauty retailers to expand service portfolios.
Integration of Biotech Innovations and Collaborative Partnerships
Biotechnology advances in peptide delivery and enzyme‑based exfoliation promise new product lines. It applies microencapsulation to stabilize sensitive actives until application. The [dull skin treatment market] benefits from academic‑industry collaborations that accelerate R&D cycles. Firms negotiate licensing agreements with biotech startups to gain access to novel compounds. They develop co‑branded offerings with dermatologists and influencers to enhance credibility. It invests in pilot studies to generate clinical evidence that supports premium positioning. Strategic alliances with device manufacturers can combine topical formulations with at‑home treatment tools.
Market Segmentation Analysis:
By Type
The dull skin treatment market divides by product type into exfoliators and cleansers, serums and ampoules, moisturizers, masks and peels, and others. Exfoliators and cleansers hold leading share by delivering immediate removal of dead cells. It innovates with new mild acids and botanical scrubs. Serums and ampoules follow by offering targeted brightening. Moisturizers maintain glow through hydrating actives. Masks and peels deliver periodic intensive therapy. Other products address niche concerns.
- For instance, Murad's AHA/BHA Exfoliating Cleanser combines chemical acids with physical exfoliants to gently reveal smoother, glowing skin and balance oil for oily and combination skin types.
By Skin Type
The dull skin treatment market segments by skin type into dry skin, oily skin, normal skin, and combination skin. Dry skin category attracts robust demand for hydrating brightening formulas. It emphasizes ceramide blends and vitamin C boosters. Oily skin segment offers lightweight gel cleansers and mattifying serums. Normal skin category sees balanced product launches. Combination skin segment drives dual‑formula solutions that target both oily and dry areas with precision.
- For instance, Dr. Sheth’s Ceramide & Vitamin C Daily Brightening & Repair Cream is designed for dry skin; it features a 1% Ceramide Complex and 5% Vitamin C to deeply moisturize, restore the skin barrier, and reduce discoloration, targeting dullness effectively.
By End User
The dull skin treatment market classifies end users into women, men, and unisex categories. Women segment holds dominant share by adopting multi‑step regimens and high‑strength actives. It integrates targeted marketing and influencer collaborations to drive loyalty. Men segment gains momentum with male‑focused cleansers and quick‑absorb serums. Unisex category expands reach by formulating neutral scents and universal textures. Brands deploy demographic insights to tailor communications. It enhances retention through subscription programs and personalized offers.
Segments:
Based on Type
- Exfoliators and Cleansers
- Serums and Ampoules
- Moisturizers
- Masks and Peels
- Others
Based on Skin Type
- Dry Skin
- Oily Skin
- Normal Skin
- Combination Skin
Based on End User
- Women
- Men
- Unisex
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America captures 35% share of the dull skin treatment market. It drives growth through robust retail networks and advanced R&D investments. Leading skincare brands fund clinical trials and adopt cutting‑edge technologies. Strong consumer spending motivates frequent product adoption and premium pricing strategies. Distribution spans specialty stores, e‑commerce platforms, and professional clinics. It shapes global trends and influences regulatory standards. Market share distribution includes Europe at 30%, Asia‑Pacific at 20%, Latin America at 10%, and Middle East & Africa at 5%.
Europe
Europe controls 30% share of the dull skin treatment market. It benefits from well‑established dermatology infrastructure and heritage cosmetic brands. Consumers demand clinical‑grade formulations backed by safety data. E‑commerce growth and cross‑border trade expand product availability. It aligns new launches with EU Cosmetic Regulation to ensure compliance. Retailers combine in‑store diagnostics with online consultations to drive sales. Regional share distribution includes North America at 35%, Asia‑Pacific at 20%, Latin America at 10%, and Middle East & Africa at 5%.
Asia‑Pacific
Asia‑Pacific holds 20% share of the dull skin treatment market. It experiences rapid urbanization and increasing disposable incomes. Local players introduce tailor‑made formulations for varied skin types. Mobile commerce channels accelerate reach into tier‑2 and tier‑3 cities. It collaborates with influencers to educate and engage consumers. Market share distribution includes North America at 35%, Europe at 30%, Latin America at 10%, and Middle East & Africa at 5%. Harmonized regulations will streamline future approvals and boost market entry.
Key Player Analysis
- Procter & Gamble Co.
- Estée Lauder Companies Inc.
- Clarins Group
- Beiersdorf AG
- Amway Corporation
- Unilever PLC
- Revlon Inc.
- L’Oréal S.A
- Shiseido Company Limited
- Avon Products Inc.
- Johnson & Johnson
- Coty Inc.
- Kao Corporation
Competitive Analysis
The dull skin treatment market features intense rivalry among global players. L’Oréal S.A. leverages advanced R&D to launch stable vitamin C derivatives. Procter & Gamble Co. integrates AI diagnostics in e‑commerce platforms. Unilever PLC drives sales through sustainable sourcing and clean‑label formulas. Estée Lauder Companies Inc. focuses on high‑end serums with patented peptides. Johnson & Johnson expands clinical‑grade peels through dermatology channels. Shiseido Company Limited tailors offerings to Asian skin types and climate patterns. Avon Products Inc. uses direct‑selling networks to boost trial. Amway Corporation offers multistep regimens backed by nutritional supplements. Kao Corporation collaborates with biotech firms to commercialize novel actives. Coty Inc. differentiates based on fragrance‑infused masks. Revlon Inc. emphasizes affordability in mass‑market cleansers. Clarins Group combines plant extracts with microencapsulation. It monitors performance metrics and consumer feedback to refine portfolio. Companies compete on efficacy data, branding, and distribution strategies to secure leadership.
Recent Developments
- In 2023, Vaseline launched a new premium skincare range specifically targeting dull skin, with unique ingredients to revitalize and brighten the complexion.
- In January 2023, Bulldog Skincare introduced an AI Skin Advisor on its UK website through a partnership with Revieve, offering AI-powered selfie analysis aimed at improving skincare journeys for men, including dull skin concerns.
- In April 2025, Clarins achieved B Corp certification for both its flagship and MyBlend brands, affirming its commitment to rigorous social and environmental standards .
- In July 2025, PDO Max launched its LúmEnvy Skincare brand featuring a Brightening Facial enriched with papaya enzymes, vitamin E, and hyaluronic acid to revitalize dull complexions.
Market Concentration & Characteristics
The dull skin treatment market exhibits moderate concentration, with a handful of global leaders commanding significant share through diversified portfolios and extensive distribution networks. L’Oréal S.A., Procter & Gamble Co., Unilever PLC and Estée Lauder Companies Inc. drive innovation by funding clinical trials and launching patented brightening serums. It balances premium and mass‑market segments by offering high‑end peels in professional clinics alongside affordable exfoliating cleansers in retail chains. Regional champions adapt formulations to local preferences in Asia‑Pacific and Latin America, while North American and European brands leverage established e‑commerce platforms to maintain leadership. It uses targeted marketing campaigns and influencer partnerships to reinforce brand equity and capture repeat purchases through subscription models. Competitive dynamics hinge on efficacy data, sustainability credentials and regulatory compliance, which together shape product claims and launch timelines across key markets.
Report Coverage
The research report offers an in-depth analysis based on Type, Skin Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The dull skin treatment market will personalize regimens through AI-driven analysis integrated into direct‑to‑consumer platforms.
- It will combine topical brightening agents with advanced at‑home devices to deliver professional‑grade treatment effectiveness.
- It will launch subscriptions ensuring seamless repeat delivery of customized product kits and skincare content.
- It will partner with startups to access innovative brightening actives, accelerate research through licensing agreements.
- It will adopt sustainable materials, biodegradable packaging to reduce environmental impact and attract eco‑conscious consumers.
- It will deploy virtual try‑on features and matching algorithms to boost online confidence and conversion.
- It will publish clinical data in peer‑reviewed journals to substantiate efficacy claims and enhance credibility.
- It will engage dermatologists and influencers for credible treatment education, driving trust, guiding consumer expectations.
- It will develop bundles pairing topical serums with at‑home devices to maximize efficacy and convenience.
- It will optimize supply chains via analytics and cross‑border logistics to ensure timely product availability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Heightened Consumer Focus on Skin Radiance and Health
Consumers are increasingly seeking products that deliver brighter, more even complexions, fueling demand for exfoliators, vitamin C serums, and professional therapies that target dullness and uneven skin tone.
Technological Innovation and AI-Powered Personalization
Advancements in ingredient science, such as stable vitamin C derivatives and microencapsulation, along with AI-driven skin analysis tools, are enhancing treatment efficacy and enabling highly personalized skincare regimens.
Expansion of E-Commerce and Direct-to-Consumer Models
The rapid growth of e-commerce platforms and subscription services is making dull skin treatments more accessible globally, supporting repeat purchases and enabling brands to reach new customer segments efficiently.
Demand for Clean-Label and Sustainable Formulations
Rising consumer preference for natural, clean-label ingredients and eco-friendly packaging is driving brands to innovate with plant-derived actives and sustainable practices, aligning with broader environmental and ethical concerns.
Growth of At-Home Devices and Noninvasive Solutions
Consumers are increasingly adopting at-home devices like LED masks and microdermabrasion kits, which offer convenient, noninvasive alternatives to professional treatments and support ongoing skin maintenance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the dull skin treatment market?
What are the key segments within the dull skin treatment market?
What are some challenges faced by the dull skin treatment market?
Who are the major players in the dull skin treatment market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Exfoliators and Cleansers
- 1.2.2 Serums and Ampoules
- 1.2.3 Moisturizers
- 1.2.4 Masks and Peels
- 1.2.5 Others
- 1.3 By End User
- 1.3.1 Women
- 1.3.2 Men
- 1.3.3 Unisex
- 1.4 By Skin Type
- 1.4.1 Dry Skin
- 1.4.2 Oily Skin
- 1.4.3 Normal Skin
- 1.4.4 Combination Skin
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,540.63 million → 2032: USD 6,874.34 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dull Skin Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dull Skin Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dull Skin Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dull Skin Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dull Skin Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dull Skin Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dull Skin Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dull Skin Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,540.63 million → 2032: USD 6,874.34 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dull Skin Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Exfoliators and Cleansers
- 12.3.7.2 Serums and Ampoules
- 12.3.7.3 Moisturizers
- 12.3.7.4 Masks and Peels
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Women
- 12.4.7.2 Men
- 12.4.7.3 Unisex
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Skin Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Dry Skin
- 12.5.7.2 Oily Skin
- 12.5.7.3 Normal Skin
- 12.5.7.4 Combination Skin
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dull Skin Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dull Skin Treatment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dull Skin Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dull Skin Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 L’Oréal S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Procter & Gamble Co.
- 18.4 Unilever PLC
- 18.5 Estée Lauder Companies Inc.
- 18.6 Johnson & Johnson
- 18.7 Shiseido Company Limited
- 18.8 Kao Corporation
- 18.9 Beiersdorf AG
- 18.10 Clarins Group
- 18.11 Avon Products Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

