
Market Overview:
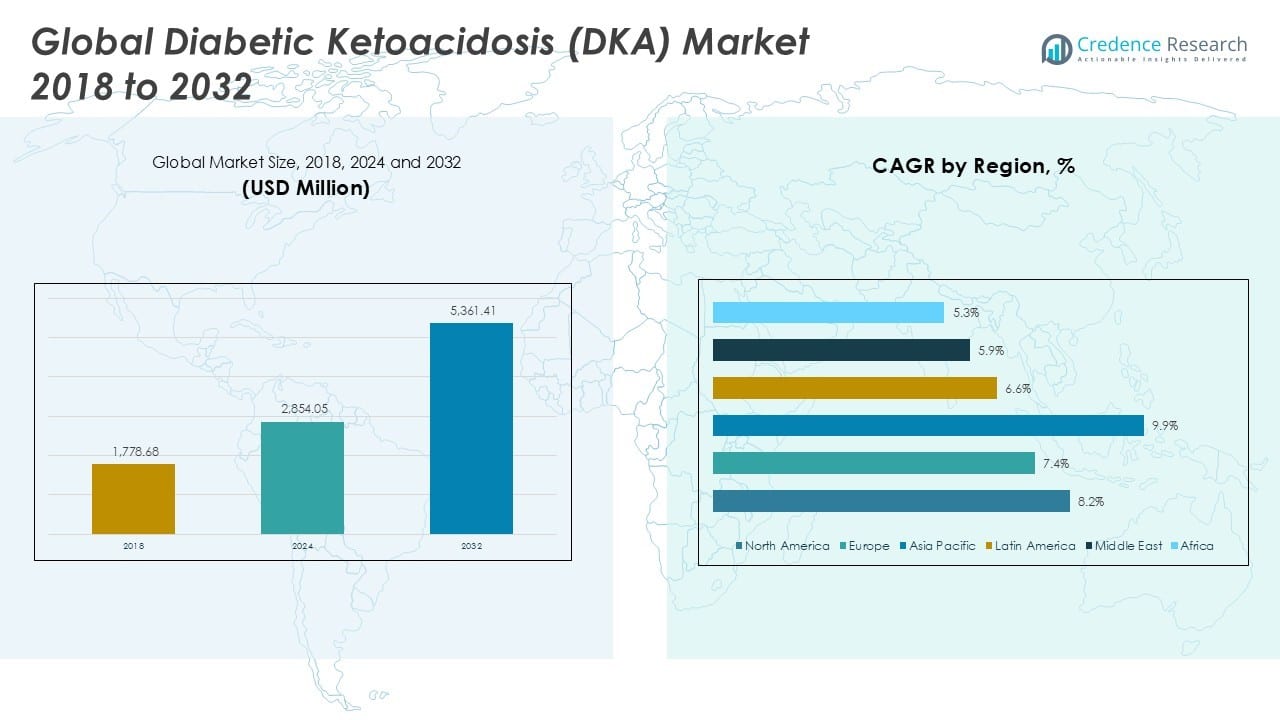
The Diabetic Ketoacidosis Treatment Market size was valued at USD 1,778.68 million in 2018 to USD 2,854.05 million in 2024 and is anticipated to reach USD 5,361.41 million by 2032, at a CAGR of 8.20% during the forecast period
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Diabetic Ketoacidosis Treatment Market Size 2024 | USD 2,854.05 Million |
| Diabetic Ketoacidosis Treatment Market, CAGR | 8.20% |
| Diabetic Ketoacidosis Treatment Market Size 2032 | USD 5,361.41 Million |
Key drivers propelling the market include the growing diabetic population, which significantly contributes to the rise in DKA cases. As diabetes becomes more prevalent globally, there is a heightened need for effective management solutions for diabetic emergencies such as DKA. Additionally, advancements in medical technology, including continuous glucose monitoring (CGM) devices and insulin pumps, have improved the management of DKA. The availability of innovative drugs and treatment options that target the root causes of DKA also contributes to market growth. Furthermore, increasing awareness of DKA among healthcare professionals and patients has facilitated early diagnosis and improved patient outcomes.
Regionally, North America holds the largest share of the Global DKA Market due to the high prevalence of diabetes, advanced healthcare infrastructure, and strong adoption of innovative medical technologies. The market in Europe is also significant, with rising awareness and improved healthcare access. The Asia Pacific region is expected to witness the fastest growth due to the rising incidence of diabetes, improving healthcare infrastructure, and growing patient awareness in emerging economies such as India and China.
Market Insights:
- The Global Diabetic Ketoacidosis Treatment Market was valued at USD 1,778.68 million in 2018, projected to reach USD 5,361.41 million by 2032, growing at a CAGR of 8.20% during the forecast period.
- The growing global diabetic population significantly drives the demand for DKA management solutions, leading to an increase in related products and services.
- Advancements in medical technologies, like continuous glucose monitoring (CGM) devices and insulin pumps, have greatly improved DKA management.
- Rising awareness about DKA among healthcare professionals and the public has resulted in earlier diagnoses and better patient outcomes.
- The availability of innovative treatment options, such as advanced insulin therapies and intravenous fluids, is enhancing patient care and market growth.
- High treatment costs and limited healthcare access in certain regions remain challenges for broader DKA management adoption.
- North America dominates the market, owing to high diabetes prevalence, advanced healthcare systems, and early adoption of medical technologies.
Market Drivers:
Growing Diabetic Population Driving Market Demand
The increasing global prevalence of diabetes plays a critical role in expanding the Global Diabetic Ketoacidosis (DKA) Market. As diabetes rates continue to rise, especially in regions such as North America, Europe, and Asia Pacific, there is an increased likelihood of complications such as DKA. More individuals with diabetes are at risk for this serious condition, necessitating effective management strategies. Healthcare providers are focusing on improving emergency treatment protocols and enhancing overall management of diabetic crises like DKA. The expansion of diabetic populations directly drives demand for DKA-related products and services, including drugs, medical devices, and diagnostic tools.
- For instance, Baxter’s Plasma-Lyte solution has been shown to resolve DKA in adult ICU patients in a median time of 49 hours, which is 6 hours faster compared to sodium chloride treatment, as demonstrated in a randomized trial involving 90 patients.
Technological Advancements in Diabetes Management
Technological innovations are pivotal in the growth of the Global Diabetic Ketoacidosis (DKA) Market. Continuous glucose monitoring (CGM) devices and insulin pumps have revolutionized diabetes management, offering real-time glucose level tracking and insulin delivery. These advancements reduce the risk of DKA by helping individuals maintain stable blood glucose levels. Such devices have become essential in improving the management of diabetes and preventing severe complications. As these technologies continue to evolve, they provide better control, minimize DKA occurrences, and are becoming integral components of diabetes treatment plans.
- For instance, the Medtronic MiniMed 780G insulin pump system automatically adjusts insulin delivery every 5 minutes, for a total of 288 automated adjustments daily to maintain optimal glucose levels.
Rising Awareness and Improved Early Diagnosis
Raising awareness of DKA among both healthcare professionals and the general public has contributed to more timely diagnoses and interventions. Medical professionals now have a better understanding of the symptoms and early signs of DKA, which allows for more efficient diagnosis and treatment. Early detection reduces complications and mortality rates associated with DKA. Public awareness campaigns about the risks of diabetes-related complications are further encouraging patients to seek help sooner. This increased awareness leads to earlier interventions and more effective management, contributing to market growth.
Expanding Availability of Treatment Options
The availability of new and more effective treatment options for DKA is another key driver of the Global Diabetic Ketoacidosis (DKA) Market. Innovative drugs and therapies that target the underlying causes of DKA, such as insulin therapy and intravenous fluids, are becoming more widely accessible. These treatments, coupled with advances in supportive care, have improved patient outcomes and reduced hospitalization times. The ongoing development of new medications and clinical approaches to managing DKA ensures that healthcare providers have a broader range of tools at their disposal, which is expected to continue fueling market growth.
Market Trends:
Increasing Adoption of Personalized Treatment Approaches
A significant trend in the Global Diabetic Ketoacidosis (DKA) Market is the shift toward personalized treatment strategies. With advancements in healthcare, diabetes management is becoming more tailored to individual needs, focusing on specific metabolic responses and risk factors. Personalized medicine allows for more effective treatment of DKA by considering factors like age, comorbidities, and lifestyle. This approach enhances the precision of drug therapies and insulin regimens, improving patient outcomes. Healthcare providers are adopting advanced diagnostic tools to better understand each patient's condition, enabling customized intervention plans. Such strategies are becoming integral in reducing DKA incidence and optimizing overall care for diabetic patients.
- For instance, Dr. James Thrasher presented U.S. data on MiniMed™ 780G involving 7,499 users, where the system demonstrated sustained safe glucose levels and stable automated insulin dosing, verified in clinical conference reports.
Growth of Home-Based Care Solutions
Home-based care solutions are emerging as a notable trend in the Global Diabetic Ketoacidosis (DKA) Market. With the increasing demand for more flexible and convenient healthcare options, home care solutions such as remote monitoring devices and telemedicine consultations are gaining traction. These technologies allow patients to manage their diabetes more effectively at home, reducing hospital visits and the risk of DKA-related complications. Remote patient monitoring tools, including CGM devices, insulin pumps, and glucose tracking apps, empower patients to track their health and receive real-time feedback from healthcare providers. The growing acceptance of home-based care solutions is helping mitigate DKA risks and expanding market opportunities for providers of these technologies.
- For instance, Dexcom’s G7 continuous glucose monitoring system, cleared by the FDA in December 2022, provides a real-time glucose value every 5 minutes and each sensor operates continuously for up to 10 days.
Market Challenges Analysis:
High Treatment Costs and Limited Accessibility
One of the primary challenges in the Global Diabetic Ketoacidosis (DKA) Market is the high cost associated with DKA treatment. The cost of advanced diagnostic tools, insulin therapies, and hospitalizations can be a significant burden for both patients and healthcare systems, particularly in developing regions. This financial barrier often limits access to timely and appropriate care for individuals at risk of DKA. In addition, not all healthcare facilities, especially in low-income countries, have access to the necessary infrastructure to manage severe cases of DKA, leading to disparities in patient outcomes. Addressing these cost and accessibility challenges is crucial for broadening the reach of effective DKA management.
Lack of Awareness in Underserved Regions
A major challenge facing the Global Diabetic Ketoacidosis (DKA) Market is the lack of awareness in underserved regions. While DKA is a well-recognized complication in developed countries, many areas still struggle with limited knowledge of its risks and management. This gap in awareness among healthcare providers and patients results in delayed diagnoses and inadequate treatment, which can worsen patient outcomes. Education and training for healthcare workers, especially in rural and low-resource settings, are essential to overcoming this challenge. Increasing public awareness and professional education will be key to improving early detection and reducing the incidence of DKA.
Market Opportunities:
Expansion of Telemedicine and Remote Monitoring Solutions
The Global Diabetic Ketoacidosis (DKA) Market presents significant opportunities with the growing expansion of telemedicine and remote monitoring solutions. The adoption of digital health tools, including remote patient monitoring devices and mobile health applications, has made diabetes management more accessible, especially in rural and underserved regions. Telemedicine services can facilitate timely consultations and continuous monitoring, reducing the need for frequent hospital visits. These technologies empower patients to manage their condition proactively, potentially reducing the occurrence of DKA. The rise of telemedicine also offers opportunities for healthcare providers to expand their reach and improve patient outcomes at a lower cost.
Rising Demand for Preventive Care and Early Intervention
There is an increasing focus on preventive care and early intervention in the Global Diabetic Ketoacidosis (DKA) Market, providing a valuable opportunity for market growth. With the rising prevalence of diabetes, healthcare systems are prioritizing preventive strategies to reduce the incidence of complications like DKA. Early detection and management of diabetes through regular screening, advanced diagnostic tools, and personalized treatment plans can significantly decrease the occurrence of DKA. The emphasis on prevention creates a growing demand for innovative solutions such as continuous glucose monitors, insulin pumps, and personalized therapies, presenting new opportunities for companies operating in the market.
Market Segmentation Analysis:
By Type
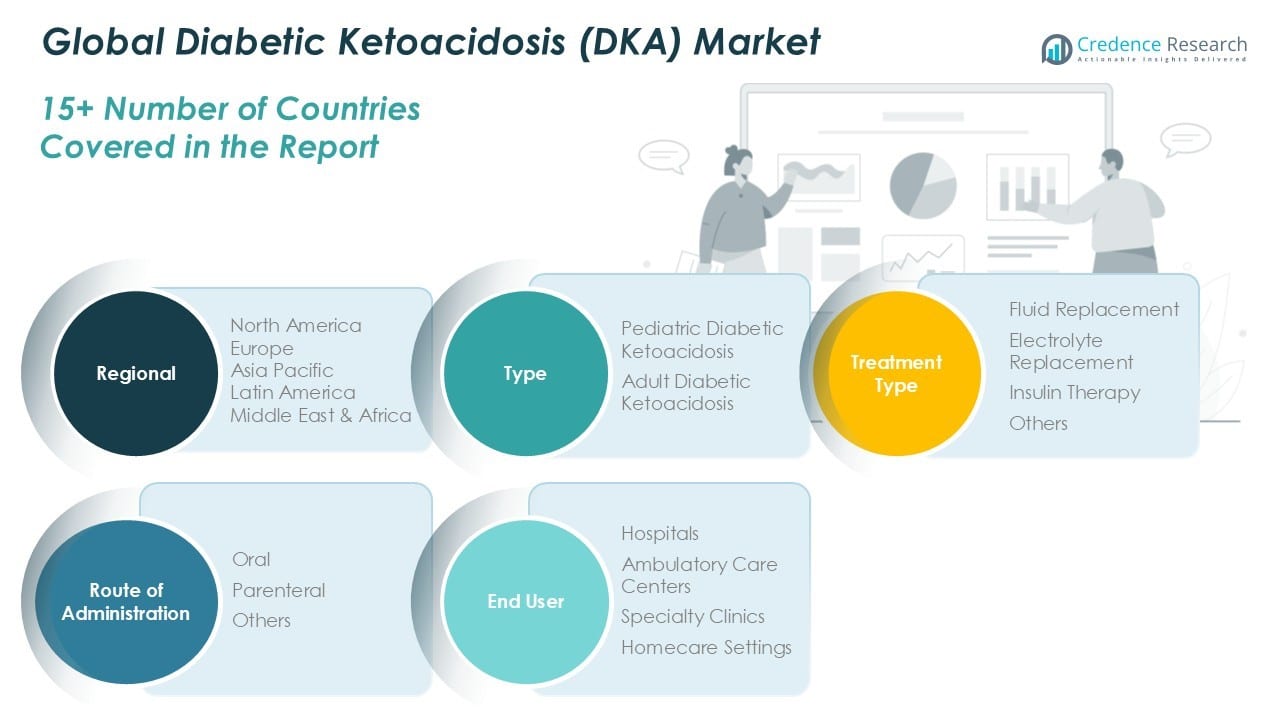
The Global Diabetic Ketoacidosis (DKA) Market is categorized into pediatric and adult diabetic ketoacidosis. Pediatric cases require specialized care to manage the complexities of younger patients, while adult cases often necessitate more intensive treatment, contributing to a larger share of the market.
By Treatment Type
The market offers treatment options such as fluid replacement, electrolyte replacement, insulin therapy, and others. Fluid and electrolyte replacement therapies help stabilize patients, while insulin therapy is crucial for regulating blood glucose levels. Each treatment method addresses specific needs and promotes recovery, driving the demand for advanced therapeutic solutions.
- For instance, Nuwellis received U.S. Patent No. 12,357,734 for its blood filtering technology that precisely accounts for fluid densities during continuous renal replacement therapy, enhancing volumetric flow accuracy in CRRT systems for over 1,000 clinical machines used globally.
By Route of Administration
The route of administration is divided into oral, parenteral, and other methods. Parenteral administration is typically preferred for more severe DKA cases due to its faster and more direct impact on the patient. Oral treatments remain less common but are used in milder cases. The choice of administration method plays a key role in the speed and effectiveness of treatment.
- For instance, Novo Nordisk’s insulin aspart demonstrated the highest utilization among parenteral insulins worldwide, with a measured increase in its Defined Daily Doses (DDD) per 1,000 inhabitants per day for the last decade, confirming strong adoption of pen-type injectable technologies.
Segmentations:
By Type- Pediatric Diabetic Ketoacidosis
- Adult Diabetic Ketoacidosis
- Fluid Replacement
- Electrolyte Replacement
- Insulin Therapy
- Others
- Oral
- Parenteral
- Others
- Hospitals
- Ambulatory Care Centers
- Specialty Clinics
- Homecare Settings
By Region
- North America
- Europe
- Aisa- Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America
The North America Global Diabetic Ketoacidosis (DKA) market size was valued at USD 758.32 million in 2018, projected to reach USD 1,203.85 million in 2024, and is anticipated to grow to USD 2,267.90 million by 2032, at a CAGR of 8.2% during the forecast period. North America holds the largest market share due to the high prevalence of diabetes, well-established healthcare infrastructure, and advanced diagnostic and treatment technologies. The U.S. dominates the market, driven by widespread awareness about diabetes-related complications and the adoption of continuous glucose monitoring (CGM) devices and insulin pumps. The region also benefits from robust government support for diabetes management programs and extensive healthcare research. Increasing investments in healthcare technology and the growing focus on preventive care further contribute to market growth. The region’s market share remains dominant due to these factors, with a consistent demand for DKA management solutions.
Europe
The Europe Global Diabetic Ketoacidosis (DKA) market size was valued at USD 526.91 million in 2018, projected to reach USD 816.28 million in 2024, and is anticipated to grow to USD 1,447.62 million by 2032, at a CAGR of 7.4% during the forecast period. Europe is the second-largest market for DKA, driven by the rising incidence of diabetes and the increasing adoption of advanced diabetes management technologies. The market is supported by strong healthcare systems in countries like Germany, France, and the UK, where diabetes management is a priority. Increased government initiatives and insurance coverage for diabetes-related treatments also enhance market growth. Rising awareness about DKA and its risks among both healthcare providers and patients is another key factor driving demand. The adoption of home-based care solutions is also growing, contributing to market expansion.
Asia Pacific
The Asia Pacific Global Diabetic Ketoacidosis (DKA) market size was valued at USD 329.46 million in 2018, projected to reach USD 574.71 million in 2024, and is anticipated to grow to USD 1,227.79 million by 2032, at a CAGR of 9.9% during the forecast period. This region is expected to witness the fastest market growth due to the rising prevalence of diabetes, particularly in countries like China and India. Improved healthcare infrastructure and increasing patient awareness are key drivers of the market. The growing adoption of modern healthcare technologies, such as CGMs and insulin pumps, is also boosting the demand for DKA management. The large diabetic population, coupled with improving access to healthcare services in emerging economies, creates a significant opportunity for growth in the Asia Pacific region.
Latin America
The Latin America Global Diabetic Ketoacidosis (DKA) market size was valued at USD 84.20 million in 2018, projected to reach USD 133.43 million in 2024, and is anticipated to grow to USD 221.92 million by 2032, at a CAGR of 6.6% during the forecast period. The Latin American market is growing steadily, primarily driven by the increasing prevalence of diabetes and expanding healthcare access. Rising awareness about diabetes and its complications, including DKA, is fueling the demand for advanced treatment options. The region benefits from improving healthcare infrastructure and greater availability of diabetes-related technologies. However, challenges such as high treatment costs and disparities in healthcare access may hinder market growth in some areas. Despite these challenges, the market is poised for growth due to ongoing healthcare initiatives and technological adoption.
Middle East
The Middle East Global Diabetic Ketoacidosis (DKA) market size was valued at USD 50.22 million in 2018, projected to reach USD 73.71 million in 2024, and is anticipated to grow to USD 117.03 million by 2032, at a CAGR of 5.9% during the forecast period. The market in the Middle East is expanding gradually due to the rising diabetes prevalence, particularly in countries such as Saudi Arabia and the UAE. The region is investing heavily in healthcare infrastructure, leading to improved access to treatment for DKA. The increasing availability of advanced diabetes management technologies is another factor contributing to market growth. However, challenges such as high treatment costs and varying healthcare standards across the region may slow growth. Nonetheless, efforts to improve healthcare delivery and increase awareness are expected to drive the market forward.
Africa
The Africa Global Diabetic Ketoacidosis (DKA) market size was valued at USD 29.57 million in 2018, projected to reach USD 52.07 million in 2024, and is anticipated to grow to USD 79.15 million by 2032, at a CAGR of 5.3% during the forecast period. The African market is characterized by a growing diabetic population and rising awareness about the risks of DKA. However, challenges such as limited healthcare infrastructure, high treatment costs, and insufficient public awareness hinder the market's potential. Despite these obstacles, ongoing efforts by governments and healthcare organizations to improve access to diabetes care are expected to drive market growth. The increasing adoption of mobile health technologies and telemedicine solutions is further enhancing the management of DKA in the region.
Key Player Analysis:
- Novo Nordisk A/S
- Eli Lilly and Company
- Sanofi S.A.
- Merck & Co., Inc.
- Biocon Limited
- Bristol-Myers Squibb
- AstraZeneca
- Pfizer Inc.
- Novartis AG
- Roche Holding AG
- GlaxoSmithKline plc
- Boehringer Ingelheim International GmbH
Competitive Analysis:
The Global Diabetic Ketoacidosis (DKA) Market is highly competitive, with major pharmaceutical and healthcare companies leading the development of advanced treatment solutions. Key players such as Novo Nordisk, Eli Lilly, and Sanofi focus on enhancing insulin therapies and expanding their portfolios in the DKA space. These companies leverage their extensive research and development capabilities to introduce innovative products that address both pediatric and adult DKA cases. Competition is also fueled by the growing demand for effective fluid and electrolyte replacement treatments. Companies are investing in improving the speed and efficiency of their therapies, particularly through parenteral routes of administration. The market is witnessing strategic partnerships and collaborations aimed at improving product offerings and expanding geographic reach. Companies that continue to innovate and improve patient outcomes through personalized treatment approaches are expected to maintain a competitive edge in this dynamic market.
Recent Developments:
- In June 2025, Novo Nordisk launched its weight-loss drug Wegovy as a once-weekly injection in India, officially entering the market with its highly anticipated obesity treatment.
- In June 2025, The U.S. FDA approved Merck’s ENFLONSIA™ (clesrovimab-cfor) for the prevention of RSV lower respiratory tract disease in neonates and infants, with distribution starting ahead of the RSV season.
- In February 2025, Biocon Biologics launched YESINTEK™ (ustekinumab-kfce), a Stelara biosimilar for Crohn’s disease, ulcerative colitis, plaque psoriasis, and psoriatic arthritis, making it one of the first such biosimilars available in the U.S.
- In February 2025, Biocon Limited announced the launch of liraglutide, a GLP-1 peptide therapy, in the United Kingdom for diabetes and chronic weight management, following approval by the U.K. Medicines and Healthcare Products Regulatory Agency.
Market Concentration & Characteristics:
The Global Diabetic Ketoacidosis (DKA) Market exhibits moderate to high concentration, with key players such as Novo Nordisk, Eli Lilly, and Sanofi holding significant market shares. These leading companies dominate the market through their strong product portfolios, extensive research and development, and widespread distribution networks. The market is characterized by the continuous introduction of innovative therapies, particularly in insulin treatments and fluid replacement solutions, to meet the diverse needs of pediatric and adult DKA patients. While major players control a large portion of the market, there is still room for emerging companies to innovate, particularly in niche treatment areas. Competitive dynamics are shaped by advancements in treatment effectiveness, patient accessibility, and strategic partnerships aimed at expanding regional presence.
Report Coverage:
The research report offers an in-depth analysis based on Type, Treatment Type, Route of Administration, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Diabetic Ketoacidosis (DKA) Market is expected to continue growing, with North America maintaining its leadership due to high diabetes prevalence and advanced healthcare infrastructure.
- Asia-Pacific will likely emerge as the fastest-growing region, driven by rising diabetes cases and improving medical facilities.
- The insulin therapy segment is projected to hold the largest market share, with rapid-acting insulins playing a pivotal role in DKA treatment.
- Fluid and electrolyte replacement therapies are expected to grow significantly, reflecting their essential role in DKA management.
- Parenteral administration methods will remain dominant, as they provide faster and more effective treatment options for patients.
- Hospitals will continue to be the primary end-users, contributing the most to market revenue due to their extensive DKA care requirements.
- Homecare settings are projected to grow at a notable rate, driven by advancements in remote monitoring technologies and patient education.
- Technological innovations, such as continuous glucose and ketone monitoring systems, will enhance early detection and facilitate personalized treatment strategies.
- The integration of artificial intelligence in diabetes care is expected to improve treatment outcomes and optimize patient management.
- Increased awareness and education about DKA are likely to contribute to better prevention, diagnosis, and treatment adherence, supporting overall market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Diabetic Ketoacidosis Treatment market?
What factors are driving the growth of the Diabetic Ketoacidosis Treatment market?
What are the key segments within the Diabetic Ketoacidosis Treatment market?
What are some challenges faced by the Diabetic Ketoacidosis Treatment market?
Who are the major players in the Diabetic Ketoacidosis Treatment market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Diabetic Ketoacidosis Treatment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Diabetic Ketoacidosis Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 1,778.68 million → 2032: USD 5,361.41 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Diabetic Ketoacidosis Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Diabetic Ketoacidosis Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Diabetic Ketoacidosis Treatment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Diabetic Ketoacidosis Treatment Market Drivers
- 3.3 Diabetic Ketoacidosis Treatment Market Restraints & Challenges
- 3.4 Diabetic Ketoacidosis Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Diabetic Ketoacidosis Treatment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Diabetic Ketoacidosis Treatment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Diabetic Ketoacidosis Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Diabetic Ketoacidosis Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Diabetic Ketoacidosis Treatment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Diabetic Ketoacidosis Treatment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Diabetic Ketoacidosis Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2018
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Diabetic Ketoacidosis Treatment Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2018)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Diabetic Ketoacidosis Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Diabetic Ketoacidosis Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Diabetic Ketoacidosis Treatment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Diabetic Ketoacidosis Treatment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Diabetic Ketoacidosis Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Diabetic Ketoacidosis Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Diabetic Ketoacidosis Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Diabetic Ketoacidosis Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Diabetic Ketoacidosis Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Diabetic Ketoacidosis Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Diabetic Ketoacidosis Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
