
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Household Appliances Market Size 2024 | USD 173,519 Million |
| Electric Household Appliances Market, CAGR | 10.2% |
| Electric Household Appliances Market Size 2032 | USD 377,398.17 Million |
Market Overview:
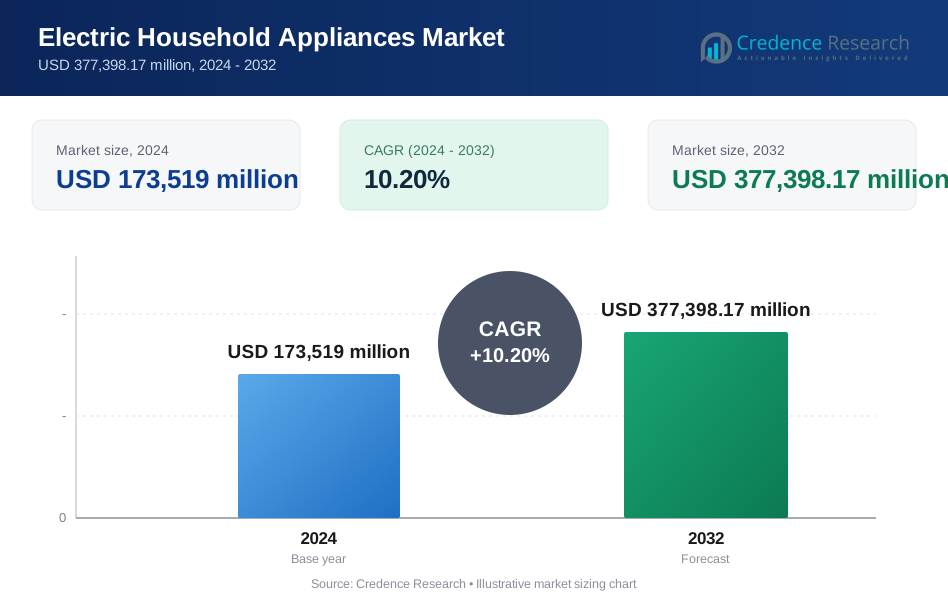
The Electric Household Appliances Market is projected to grow from USD 173,519 million in 2024 to USD 377,398.17 million by 2032, with a compound annual growth rate (CAGR) of 10.2%.
The Electric Household Appliances Market is driven by factors such as increasing consumer demand for convenience, energy-efficient solutions, and advanced technology integration. The growing adoption of smart home systems, including IoT-enabled appliances, is significantly influencing market growth. Additionally, rising disposable incomes and urbanization are encouraging consumers to invest in modern household appliances. Technological innovations, such as AI-driven devices, energy-efficient solutions, and customizable designs, are becoming key trends, appealing to eco-conscious and tech-savvy consumers. Moreover, the increasing focus on sustainability, with appliances designed to reduce power consumption and carbon footprints, is boosting the market. Furthermore, the shift towards online retail channels and digital marketing is enhancing product accessibility and customer engagement, leading to a broader market reach. The ongoing expansion of smart kitchens and home automation further reinforces the demand for electric household appliances, with companies increasingly investing in R&D to meet evolving consumer expectations.
The Electric Household Appliances Market exhibits diverse growth across regions, with North America holding a significant share, driven by high demand for smart and energy-efficient appliances. Europe follows closely, where sustainability and energy regulations are pushing innovation. The Asia Pacific region leads in growth, accounting for the largest share, fueled by rapid urbanization and increasing disposable incomes, particularly in China, India, and Japan. Latin America is expanding steadily, with Brazil and Mexico at the forefront, while the Middle East and Africa show growth driven by rising urbanization and the demand for cooling appliances. Key players such as Whirlpool Corporation, Samsung Electronics, Haier, Bajaj Electricals, Philips, and Panasonic are strengthening their presence in these regions, leveraging local demand for energy-efficient, technologically advanced products to expand their market share and cater to diverse consumer needs.
Market Insights:
- The Electric Household Appliances Market is projected to grow from USD 173,519 million in 2024 to USD 377,398.17 million by 2032, at a CAGR of 10.2%.
- Consumer demand for convenience, energy-efficient solutions, and advanced technology integration, including IoT-enabled appliances, is driving market growth.
- Technological innovations such as AI-driven devices, energy-efficient solutions, and customizable designs are becoming key trends, appealing to eco-conscious and tech-savvy consumers.
- Rising disposable incomes, urbanization, and the adoption of smart home systems are further boosting the demand for modern household appliances.
- The shift toward online retail channels and digital marketing is enhancing product accessibility and customer engagement.
- North America, Europe, and Asia Pacific dominate the market, with North America projected to hold 25% of the market share in 2024, followed by Europe at 22%, and Asia Pacific at 40%.
- The Middle East and Africa, along with Latin America, are emerging markets, with steady growth driven by increasing urbanization and rising disposable incomes.
Market Drivers:
Growing Consumer Demand for Convenience:
The increasing demand for convenience is a primary driver in the Electric Household Appliances Market. As consumers lead increasingly busy lives, there is a rising preference for appliances that reduce manual effort and enhance efficiency. Products like smart refrigerators, washing machines, and dishwashers are gaining popularity for their time-saving features. For instance, LG Electronics offers smart washing machines equipped with AI-powered sensors that automatically detect fabric type and weight, optimizing washing cycles for greater convenience. Additionally, multifunctional appliances that offer multiple tasks in one device are appealing to modern households, simplifying everyday chores.
Advancements in Technology:
Technological innovations are significantly shaping the Electric Household Appliances Market. The integration of Artificial Intelligence (AI), IoT, and smart technology in household appliances is revolutionizing the sector. Consumers are now opting for devices that offer advanced functionalities, such as smart refrigerators that track inventory or washing machines that adjust washing cycles based on load size. For instance, Samsung’s Family Hub refrigerator enables users to track groceries, stream music, and control other smart devices directly from its touchscreen panel, creating a more connected home experience. These advancements improve appliance performance and enhance home efficiency, making technology a strong market driver.
Energy Efficiency and Sustainability Trends:
There is a growing emphasis on energy efficiency and sustainability in the Electric Household Appliances Market. As global awareness of environmental issues increases, consumers are becoming more conscious of the energy consumption of their household devices. Energy-efficient appliances, such as those with Energy Star ratings or those designed to minimize water usage, are in high demand. For instance, Whirlpool has introduced dishwashers with low water consumption and eco-modes, helping households reduce their environmental footprint while cutting utility costs. Manufacturers are investing in developing green technologies to meet this rising demand.
Rising Disposable Incomes and Urbanization:
Rising disposable incomes and increasing urbanization are major contributors to the market’s growth. As more people move to urban areas, there is a higher demand for modern, high-tech household appliances. Urban consumers, with greater financial capabilities, are willing to invest in premium electric household appliances that enhance lifestyle and provide long-term value. For instance, Dyson’s premium vacuum cleaners appeal to urban consumers seeking high-performing, durable household devices that offer advanced features like cordless functionality and powerful suction. Additionally, the growing middle-class population in emerging economies is further boosting market growth, expanding the consumer base for electric household products.
Market Trends:
Smart Appliances and IoT Integration:
One of the most significant trends in the Electric Household Appliances Market is the growing integration of smart technology and the Internet of Things (IoT) in household devices. Smart appliances such as refrigerators, washing machines, and ovens are now equipped with sensors, Wi-Fi connectivity, and AI-driven capabilities. These innovations allow consumers to control and monitor their appliances remotely via smartphone apps, creating more convenience and enhancing user experience. For instance, GE Appliances offers a suite of smart devices that integrate seamlessly with home automation platforms like Google Home and Amazon Alexa, allowing users to control their appliances via voice commands. The rise of connected homes has driven demand for appliances that seamlessly integrate with other smart devices.
Energy Efficiency and Sustainability:
Consumers are becoming increasingly aware of environmental concerns, leading to a rising demand for energy-efficient appliances. Manufacturers are responding by developing products that minimize energy consumption and reduce carbon footprints. Energy-efficient washing machines, refrigerators, and HVAC systems are equipped with features that help lower electricity bills while contributing to sustainability. For instance, Bosch has introduced energy-efficient dishwashers with eco-friendly modes, reducing water and energy usage while maintaining high performance. Green certifications, such as Energy Star ratings, have become a key selling point for eco-conscious consumers.
Customization and Personalization:
Customization has become a key trend in the Electric Household Appliances Market, particularly in products like refrigerators and kitchen appliances. Brands like Samsung’s Bespoke line are offering consumers the ability to personalize appliances with different colors, finishes, and configurations to match their unique home styles. For instance, LG’s MoodUP refrigerators feature customizable LED panels, allowing users to change colors and create unique kitchen aesthetics. This trend reflects a shift toward products that not only offer functionality but also cater to individual preferences and aesthetics.
Rise of Online Retail and E-commerce:
The increasing shift toward e-commerce is another major trend driving the Electric Household Appliances Market. Consumers are increasingly purchasing appliances online due to the convenience, wide selection, and often lower prices. E-commerce platforms provide detailed product information, customer reviews, and delivery services, making it easier for consumers to make informed decisions. For instance, Amazon and Flipkart offer a wide range of electric household appliances, complete with customer reviews and fast delivery options, making them popular choices for modern consumers. This trend is encouraging manufacturers to strengthen their online presence and digital marketing strategies to engage with a broader audience.
Market Challenges Analysis:
Rising Raw Material Costs and Supply Chain Disruptions:
One of the primary challenges facing the Electric Household Appliances Market is the increasing cost of raw materials and ongoing supply chain disruptions. The prices of essential components such as metals, plastics, and semiconductors have surged in recent years, primarily due to global supply chain bottlenecks, labor shortages, and geopolitical tensions. These rising material costs are putting pressure on manufacturers to either absorb the higher costs or pass them onto consumers, which could potentially affect pricing competitiveness. Furthermore, the global shortage of microchips has disrupted production schedules, leading to delays in the launch of new products and an inability to meet consumer demand. As these challenges persist, companies must find ways to optimize their supply chains, improve procurement strategies, and manage costs effectively without compromising product quality, innovation, or affordability. In some cases, manufacturers are being forced to delay product releases, which could affect their market position and overall growth.
Intense Competition and Price Sensitivity:
Another significant challenge for the Electric Household Appliances Market is the intense competition and the price sensitivity of consumers. With a wide range of brands and products available in the market, companies are under constant pressure to differentiate themselves through innovation, quality, and pricing strategies. While technological advancements and premium features are attractive to certain consumer segments, price sensitivity remains a major concern for many buyers, particularly in developing economies where disposable incomes are lower. As a result, manufacturers must strike a balance between offering advanced, feature-rich products and maintaining affordable price points to remain competitive in a crowded market. Additionally, the rise of private-label and budget brands has intensified competition, making it difficult for premium brands to sustain market share without significant investments in marketing, strategic partnerships, and product differentiation. Companies that fail to manage these challenges risk losing customer loyalty and market relevance.
Market Opportunities:
The Electric Household Appliances Market presents numerous opportunities driven by evolving consumer preferences and technological advancements. One of the most significant opportunities lies in the growing demand for smart, connected appliances. As more consumers embrace the concept of smart homes, there is an increasing need for IoT-enabled devices that can be controlled remotely through smartphones or integrated with voice assistants like Amazon Alexa or Google Assistant. Appliances that offer enhanced functionality, energy efficiency, and seamless connectivity are highly sought after, providing a lucrative market for manufacturers. Companies can tap into this demand by developing advanced products with AI-driven capabilities, smart sensors, and energy-saving features that align with consumers' desire for convenience and sustainability.
Furthermore, the focus on sustainability and energy efficiency offers another substantial opportunity. With rising awareness about environmental issues, consumers are increasingly looking for appliances that reduce energy consumption and support eco-friendly living. Manufacturers can capitalize on this trend by designing energy-efficient products with green certifications, such as Energy Star ratings. Additionally, as global urbanization continues, the demand for modern, compact, and multifunctional household appliances is set to rise, especially in metropolitan areas where space and resources are limited. This trend provides a growth opportunity for businesses to innovate and offer solutions that meet the needs of smaller living spaces, such as smart refrigerators with adaptive storage and space-saving kitchen appliances. By aligning product development with these consumer priorities, companies can secure long-term market growth and strengthen their competitive edge.
Market Segmentation Analysis:
By Type
The Electric Household Appliances Market is segmented by product type into major categories such as kitchen appliances, laundry appliances, and home comfort appliances. Kitchen appliances include items like refrigerators, ovens, and dishwashers, while laundry appliances focus on washing machines and dryers. Home comfort appliances encompass air conditioners, heaters, and air purifiers. Each segment caters to specific consumer needs, with significant demand driven by convenience, energy efficiency, and technological innovation.
By Distribution Channel
The Electric Household Appliances Market is also segmented by distribution channel, with key channels including online and offline sales. Online sales are increasingly popular due to the convenience of e-commerce platforms, providing consumers with access to a wide variety of products and competitive pricing. Meanwhile, offline retail stores, including specialty appliance retailers and department stores, continue to dominate in many regions, offering hands-on product experiences and personalized customer service. Both channels are vital in reaching diverse consumer segments.
Segments:
Based on Type
- Major Appliances
- Refrigeration Equipment
- Cooking Appliances
- Washing & Drying Equipment
- Heating & Cooling Appliances
- Others
- Small Appliances
- Coffeemakers
- Food Processors
- Humidifiers
- Microwave Ovens
- Others
- Smart Home Appliances
Based on Distribution Channel
- Supermarkets & Hypermarkets
- Specialty Stores
- Online/E-commerce
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Electric Household Appliances Market, projected to account for 25% of the global market in 2024. The region’s strong demand for high-tech and energy-efficient appliances is driven by a large base of tech-savvy consumers and high disposable incomes. Smart appliances, including IoT-enabled refrigerators, washing machines, and air conditioning systems, are gaining traction due to growing interest in smart homes and home automation. Additionally, the focus on sustainability is propelling demand for energy-efficient products. The presence of key players like Whirlpool, General Electric, and Samsung further strengthens North America’s market position.
Europe
Europe is another dominant region in the Electric Household Appliances Market, holding 22% of the global market share in 2024. The region has witnessed significant growth due to a rising focus on sustainability, energy efficiency, and green technologies. European consumers are increasingly opting for appliances with energy-saving features to lower both energy consumption and carbon footprints. Countries like Germany, the UK, and France are major contributors to the regional market, with a high demand for premium, eco-friendly household appliances. Regulatory measures, such as stricter energy efficiency standards, are further driving innovation and market growth in Europe.
Asia Pacific
Asia Pacific is expected to be the fastest-growing region in the Electric Household Appliances Market, accounting for 40% of the global market share in 2024. The region’s growth is driven by rapid urbanization, increasing disposable incomes, and a growing middle class, particularly in countries like China, India, and Japan. Consumers in these nations are increasingly investing in modern household appliances that offer convenience, energy efficiency, and smart features. The rise in demand for air conditioning, refrigeration, and kitchen appliances has fueled market expansion, and manufacturers are focusing on producing affordable yet technologically advanced products to cater to the large population.
Latin America
Latin America holds a smaller portion of the Electric Household Appliances Market, with an estimated market share of 7% in 2024. However, the region is experiencing steady growth, driven by rising disposable incomes and growing demand for modern household appliances. Countries like Brazil and Mexico are leading the market, where consumers are becoming more interested in energy-efficient and technologically advanced products. Retail expansion and an increase in e-commerce sales are helping to drive the availability of these appliances.
Middle East and Africa
The Middle East and Africa (MEA) region contributes 6% to the global market share in 2024. The market in this region is expanding due to increasing urbanization, population growth, and rising standards of living, particularly in the Gulf Cooperation Council (GCC) countries. Smart appliances and energy-efficient products are becoming more popular as consumers seek convenience and sustainability. The demand for cooling appliances, such as air conditioners, is particularly high due to the region's hot climate.
Key Player Analysis:
- Panasonic Holdings Corporation (Japan)
- Whirlpool Corporation (U.S.)
- Eureka Forbes Ltd. (India)
- Samsung Electronics Co. Ltd. (South Korea)
- Haier Inc. (China)
- KENT (India)
- Orient Electric (India)
- IFB Appliances (India)
- Koninklijke Philips N.V. (South Korea)
- Bajaj Electricals Ltd (India)
Competitive Analysis:
The Electric Household Appliances Market is highly competitive, with major players constantly innovating to maintain market leadership. Companies like Whirlpool Corporation, Samsung Electronics Co. Ltd., Haier Inc., Bajaj Electricals Ltd., Koninklijke Philips N.V., IFB Appliances, KENT, Eureka Forbes Ltd., Panasonic Holdings Corporation, and Orient Electric are all vying for a share of this rapidly growing market. These companies are investing heavily in research and development to introduce smart, energy-efficient, and user-friendly products. For instance, Samsung and Haier are focusing on IoT and AI integration, enhancing the connected experience in appliances, while Whirlpool and Panasonic emphasize energy efficiency and sustainability. Additionally, regional players like Bajaj Electricals, IFB, and Orient Electric are capturing local demand by offering affordable, high-quality products tailored to specific market needs. To stay competitive, these companies are also expanding their distribution networks, leveraging online platforms, and employing aggressive marketing strategies to increase their consumer reach and brand presence.
Recent Developments:
- In September 2023, Bosch launched its fully automatic All Round Carefront load washing machines, continuing its commitment to simplifying daily tasks for customers.
- In January 2023, Samsung introduced new products to its Bespoke home appliance lineup, including the AI Oven and a wider range of Bespoke refrigerators, offering seamless integration with SmartThings for greater convenience.
- In May 2024, Samsung unveiled AI-driven washing machines that optimize water and energy usage, with smart sensors and Wi-Fi connectivity for remote control via smartphone apps.
- In June 2024, Haier launched smart refrigerators with AI and IoT connectivity, featuring energy-efficient cooling, adaptive temperature zones, and a built-in virtual assistant. The refrigerators reduce power consumption by up to 30%, supporting sustainability efforts.
Market Concentration & Characteristics:
The Electric Household Appliances Market exhibits moderate to high concentration, with a few major players dominating the global landscape. Companies such as Whirlpool, Samsung Electronics, Haier, and Panasonic lead the market, leveraging their strong brand presence, extensive product portfolios, and innovation in energy-efficient and smart appliances. These players invest heavily in research and development to maintain a competitive edge, continually introducing advanced features like AI, IoT, and sustainability-focused technologies. The market is characterized by high product differentiation, with companies offering a wide range of appliances targeting diverse consumer needs, from smart refrigerators to energy-efficient washing machines. Regional players also have a significant presence, particularly in emerging markets, where affordability and localized solutions play a key role in gaining market share. Despite the dominance of large players, the market remains dynamic, with opportunities for growth driven by technological advancements, shifting consumer preferences, and sustainability trends.
Report Coverage:
The research report offers an in-depth analysis based on Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for smart and IoT-enabled appliances will continue to rise as more consumers adopt connected home systems.
- Energy-efficient products will see increased adoption, driven by both consumer preferences and stricter global regulations.
- The integration of artificial intelligence in household appliances will enhance convenience, offering tailored experiences for users.
- There will be a growing focus on sustainability, with manufacturers developing eco-friendly appliances to reduce power consumption and carbon footprints.
- As urbanization increases, especially in emerging markets, the demand for space-saving and multifunctional appliances will grow.
- Online retail channels will become increasingly important, offering greater accessibility and convenience for consumers worldwide.
- Manufacturers will continue to innovate with customizable appliance designs to cater to varying consumer tastes and needs.
- Smart kitchens and home automation technologies will drive demand for appliances that can integrate seamlessly into smart homes.
- The trend toward premium appliances will gain momentum, with consumers willing to invest in high-quality, feature-rich products.
- Regional markets will experience growth driven by rising disposable incomes and expanding middle-class populations, especially in Asia Pacific and Latin America.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements and Smart Integration
The integration of AI, IoT, and smart technology into household appliances is transforming user experience, enabling remote control, automation, and enhanced efficiency. This is driving consumer preference for connected devices that offer convenience and seamless integration with smart home systems.
Energy Efficiency and Sustainability
Growing environmental awareness and stricter regulations are pushing both consumers and manufacturers toward energy-efficient and eco-friendly appliances. Products with features like low power consumption and green certifications are increasingly favored, supporting market growth.
Rising Disposable Incomes and Urbanization
As urban populations expand and disposable incomes rise, especially in emerging markets, consumers are investing more in modern, high-tech household appliances that improve quality of life and convenience.
Customization and Personalization
Consumers are seeking appliances that not only perform well but also match their personal tastes and home aesthetics. The trend toward customizable designs and modular appliances is attracting tech-savvy and design-conscious buyers, expanding the market.
Expansion of Online Retail and E-commerce
The shift toward online sales channels is making electric household appliances more accessible, offering consumers a wider selection, competitive pricing, and convenience. This is broadening the market reach and accelerating adoption, especially among younger demographics.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electric Household Appliances Market?
What factors are driving the growth of the Electric Household Appliances Market?
What are the key segments within the Electric Household Appliances Market?
QWhat are some challenges faced by the Electric Household Appliances Market?
Who are the major players in the Electric Household Appliances Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Major Appliances
- 1.2.2 Refrigeration Equipment
- 1.2.3 Cooking Appliances
- 1.2.4 Washing & Drying Equipment
- 1.2.5 Heating & Cooling Appliances
- 1.2.6 Small Appliances
- 1.2.7 Smart Home Appliances
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 173,519 million → 2032: USD 377,398.17 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Household Appliances Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Household Appliances Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Household Appliances Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Household Appliances Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Household Appliances Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Household Appliances Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Household Appliances Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Household Appliances Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 173,519 million → 2032: USD 377,398.17 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Household Appliances Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Major Appliances
- 12.3.7.2 Refrigeration Equipment
- 12.3.7.3 Cooking Appliances
- 12.3.7.4 Washing & Drying Equipment
- 12.3.7.5 Heating & Cooling Appliances
- 12.3.7.6 Small Appliances
- 12.3.7.7 Smart Home Appliances
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Household Appliances Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electric Household Appliances Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electric Household Appliances Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Whirlpool Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Samsung Electronics Co. Ltd.
- 17.4 Haier Inc.
- 17.5 Panasonic Holdings Corporation
- 17.6 Koninklijke Philips N.V.
- 17.7 Bajaj Electricals Ltd
- 17.8 IFB Appliances
- 17.9 Eureka Forbes Ltd.
- 17.10 KENT
- 17.11 Orient Electric
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

