
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
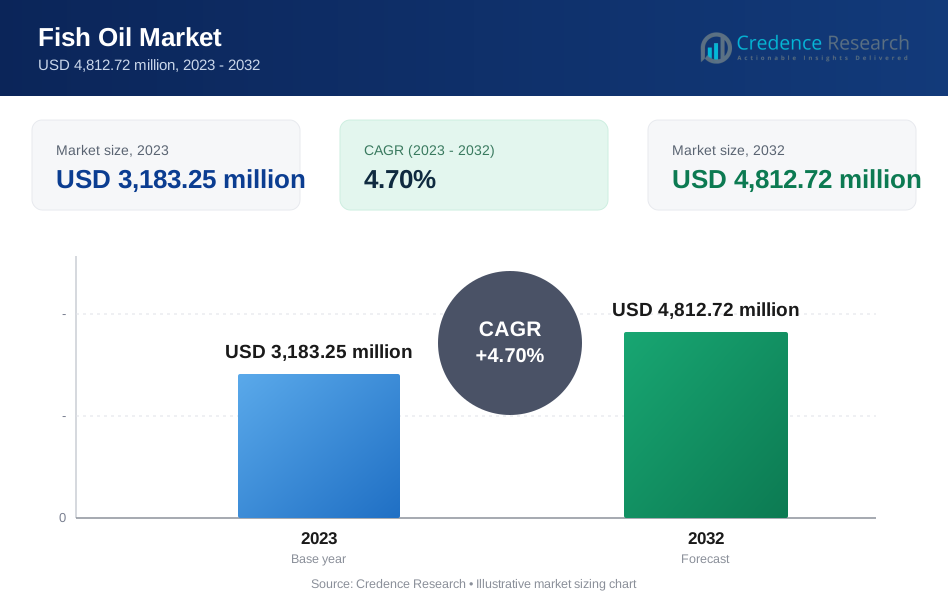
| Fish Oil Market Size 2023 | USD 3,183.25 Million |
| Fish Oil Market, CAGR | 4.70% |
| Fish Oil Market Size 2032 | USD 4,812.72 Million |
Market Overview
The Fish Oil Market is projected to grow from USD 3,183.25 million in 2023 to an estimated USD 4,812.72 million by 2032, registering a compound annual growth rate (CAGR) of 4.70% from 2024 to 2032. This growth trajectory reflects increasing demand driven by the health benefits and diverse applications of fish oil, including dietary supplements, pharmaceuticals, animal feed, and functional food products.
Key market drivers include growing consumer demand for nutrition-rich supplements, increasing adoption of aquaculture practices, and regulatory support promoting omega-3 products' health benefits. The market also benefits from technological advancements in fish oil extraction and purification processes, which improve product quality and broaden its use across multiple sectors. Additionally, industry trends such as sustainability-focused sourcing, marine conservation, and innovations in fish oil substitutes like algal-based products influence market dynamics.
Regionally, North America and Europe hold significant shares of the market due to established demand for fish oil in pharmaceuticals and functional foods. The Asia-Pacific region, however, is expected to witness the fastest growth due to rising health awareness and expanding aquaculture industries. Prominent market players include Royal DSM, Croda International Plc, BASF SE, Omega Protein Corporation, and GC Rieber Oils, which focus on innovation, sustainability, and strategic expansions to meet growing global demand.
Market Drivers
Increasing Demand for Omega-3-Based Dietary Supplements and Functional Foods
The rising consumer focus on maintaining overall health and wellness has driven a surge in demand for dietary supplements enriched with omega-3 fatty acids, primarily derived from fish oil. **Consumers are increasingly recognizing the numerous health benefits** of omega-3, including heart health improvement, anti-inflammatory properties, and enhanced cognitive functions. For instance, a 2022 meta-analysis published in the *Journal of the American Heart Association* confirmed that regular consumption of EPA and DHA, key omega-3 fatty acids, significantly lowers the risk of coronary heart disease (CHD). This scientific validation reinforces the growing consumer confidence in omega-3 supplements.Omega-3 supplements have gained traction among diverse age groups, ranging from pregnant women and infants to older adults, due to their role in brain development and chronic disease prevention. Additionally, the trend of incorporating omega-3s into functional foods, such as fortified beverages and snacks, has propelled fish oil consumption. This movement aligns with global health initiatives and consumer preference for preventive health solutions, significantly bolstering the market's expansion.
Growth in Aquaculture Industry and Fish Oil Demand for Animal Feed
The rapid growth of the aquaculture industry has significantly impacted the global fish oil market. Fish oil is a critical component of aquafeed due to its high nutritional content, particularly for farmed fish such as salmon, trout, and marine species that require omega-3 fatty acids for optimal growth and health. In 2021, aquaculture consumed 74% of the global fish oil supply, highlighting its pivotal role in ensuring optimal growth and health for species like salmon and trout. The demand for fish oil is closely linked to the aquaculture industry's development, which has become a major driver due to increased seafood consumption globally and efforts to reduce overfishing of wild stocks.Innovations in feed formulations and sustainable aquaculture practices further underscore fish oil's role as a pivotal nutritional additive, ensuring high yield and quality in farmed fish. This rising demand for high-quality aquafeed has strengthened fish oil's market position and created robust growth opportunities within the aquaculture sector.
Growing Awareness and Regulatory Support for Cardiovascular Health Benefits
Fish oil's well-documented cardiovascular benefits have become a key driver for market growth, driven by heightened awareness and substantial backing from healthcare professionals and regulatory bodies worldwide. Numerous studies have highlighted fish oil's positive impact on reducing cardiovascular disease risks, including lowering triglycerides, improving arterial function, and mitigating the risks of heart attack and stroke.Clinical trials have provided compelling evidence of omega-3's cardiovascular benefits. For example, the REDUCE-IT trial demonstrated a significant reduction in major adverse cardiovascular events among participants taking purified EPA. This aligns with the emphasis on cardiovascular disease prevention and public health campaigns.The recommendations from entities like the American Heart Association, which endorse fish oil and omega-3 consumption as part of a heart-healthy diet, have led to increased consumer confidence and demand for fish oil-based products. These recommendations are supported by regulatory approvals for omega-3 health claims across several countries.This synergy between awareness campaigns, scientific validation, and favorable regulations has further propelled the fish oil market's growth trajectory, underscoring the increasing importance of omega-3 fatty acids in preventive healthcare and nutritional supplementation.
Technological Advancements in Extraction and Sustainable Sourcing Practices
Innovations in fish oil extraction technologies and sustainable sourcing practices are significant market drivers, addressing both consumer demand for high-quality products and environmental concerns regarding overfishing and marine ecosystem conservation. The industry has witnessed a transition from traditional extraction methods to advanced techniques that enhance product purity, concentration, and stability while minimizing environmental impact. Technologies such as molecular distillation, supercritical CO2 extraction, and microencapsulation have led to the production of more refined, high-potency fish oil products tailored to different applications. Moreover, sustainability-driven sourcing practices, including certified fisheries and by-product utilization, reflect the industry’s commitment to ethical and responsible production. Consumer preference for traceable and environmentally friendly fish oil products has further accelerated the adoption of these practices, making sustainability a competitive differentiator and growth driver for market participants.
Market Trends
**Growing Emphasis on Sustainability and Traceability in Sourcing**
A key trend shaping the fish oil market is the increasing emphasis on sustainability and traceability in sourcing practices. As consumer awareness regarding environmental conservation grows, demand for ethically sourced fish oil products has surged. For instance, a 3-ounce serving of commonly consumed fish like mackerel provides about 2 grams of omega-3 fatty acids (DHA + EPA), highlighting the direct connection between sustainable fishing and nutritional value. Industry participants are actively collaborating with certification bodies such as the Marine Stewardship Council (MSC) and Friends of the Sea to adhere to sustainable harvesting practices, minimize overfishing, and protect marine biodiversity. Additionally, the use of by-products from fish processing, such as trimmings and off-cuts, has gained momentum as a more sustainable source of fish oil, reducing waste and contributing to circular economy initiatives. Technologies that enhance traceability in the supply chain, such as blockchain and other digital tracking systems, provide consumers with transparent information about the origin, quality, and environmental impact of fish oil products. This trend aligns with broader market expectations for responsible sourcing and resonates with environmentally conscious consumers seeking eco-friendly options.
**Rising Popularity of Concentrated and Customized Omega-3 Formulations**
The demand for concentrated and customized omega-3 formulations derived from fish oil is on the rise, driven by the diverse and specific health needs of consumers. Manufacturers are focusing on developing high-concentration fish oil supplements with targeted health benefits, such as heart health, joint health, cognitive function, and prenatal development. For instance, fish like herring offer around 1.3 grams of omega-3 fatty acids per 3-ounce serving, demonstrating the natural potency of these marine sources. The increasing availability of pharmaceutical-grade and ultra-pure omega-3 formulations has led to more personalized and efficacious options tailored to individual health requirements. This trend is further supported by advancements in extraction and purification techniques, enabling the production of refined products with higher purity, stability, and bioavailability. Furthermore, new delivery formats, including soft gels, liquid emulsions, and gummies, are being introduced to enhance consumer convenience and appeal. The ability to customize fish oil products based on varying age groups, lifestyles, and specific health goals has opened new avenues for product differentiation and market growth, reflecting an ongoing commitment to innovation and consumer-centric offerings within the fish oil sector.
Market Restraints and Challenges
**Sustainability Concerns and Environmental Impact of Overfishing**
A major challenge facing the fish oil market is the environmental impact associated with fish oil production, particularly overfishing and depletion of fish stocks. High demand for fish oil products has put pressure on marine ecosystems, raising concerns about unsustainable fishing practices that threaten biodiversity and ocean health. Environmental advocacy groups and regulatory bodies are increasingly focused on promoting sustainable sourcing practices to protect fish populations and maintain ecological balance. This regulatory scrutiny and consumer demand for eco-friendly products necessitate a shift toward certified sustainable fisheries, alternative sources such as algal oil, or enhanced utilization of fish by-products. While these approaches offer solutions, they also introduce challenges related to cost and scalability, requiring significant investments by industry participants to balance supply demands with environmental responsibility.
**Price Volatility and Supply Chain Instability**
The fish oil market is susceptible to price volatility due to fluctuating raw material availability and changing market dynamics. Factors such as unpredictable weather patterns, fishing quotas, geopolitical tensions, and trade restrictions can disrupt the supply of fish, leading to inconsistent pricing and increased production costs. These uncertainties make it challenging for manufacturers to maintain stable pricing structures, potentially reducing profit margins and affecting their ability to invest in innovation and expansion. Supply chain disruptions further exacerbate the issue by creating logistical bottlenecks and delays, impacting the timely delivery of fish oil products to end-users. To mitigate these challenges, industry players must navigate complex market forces and explore strategies for supply chain diversification, risk management, and alternative sources to ensure a steady supply of raw materials and more predictable pricing.
Market Segmentation Analysis
By Spices
The fish oil market is significantly influenced by species such as traditional pelagic and demersal fish, including anchovies, sardines, mackerel, and cod, known for their high omega-3 content and cost-effective fatty acid concentration. While pelagic fish dominate global production, demersal species found in deeper waters contribute less due to limited availability and sustainability challenges. Tuna-derived fish oil, though niche due to limited supply, is gaining traction in premium health products, especially for dietary supplements and infant nutrition due to its DHA-rich profile. Salmon oil, driven by growing farmed salmon production, supports market expansion with its favorable nutrient profile for human nutrition and pet food applications. Additionally, pangasius and tilapia, primarily farmed for food, present a sustainable source of fish oil through the utilization of processing by-products, despite offering lower omega-3 concentrations compared to other species.
By Application
The fish oil market, segmented by application, is led by human consumption, primarily driven by rising awareness of omega-3 health benefits and its incorporation into dietary supplements, fortified foods, and liquid formulations targeting heart health, cognitive function, and anti-inflammatory properties. The aquaculture segment remains a key demand driver, utilizing fish oil in aquafeed to support the health and growth of farmed fish as global aquafarming expands. This segment also faces growing interest in optimizing feed formulations with sustainable alternatives. The pet food sector is witnessing increased demand due to consumer awareness of omega-3’s benefits for pets, enhancing coat quality, joint health, and immune system support through fish oil-infused treats and supplements. Additionally, fish oil finds applications in pharmaceuticals and industrial uses, leveraging its bioactive properties for purposes ranging from wound healing agents to chemical intermediates.
Segments
Based on Species
- Traditional Pelagic and Demersal Species
- Tuna
- Salmon
- Pangasius and Tilapia
Based on Application
- Human Consumption
- Aquaculture
- Pet Food
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (30%)**
North America holds a significant share of the fish oil market, accounting for approximately 30% of the global market. This strong position is primarily attributed to high consumer awareness regarding the health benefits of omega-3 fatty acids and a robust demand for dietary supplements and functional foods. The United States is the major contributor to the region’s growth, with a well-established nutraceuticals sector and increasing adoption of fish oil products for cardiovascular health, cognitive enhancement, and joint health. The market is further supported by stringent regulatory standards ensuring product quality, which builds consumer trust. Moreover, pet nutrition and pharmaceutical applications contribute to market growth, reflecting a diverse range of uses.
Europe (28%)**
Europe closely follows North America, with a market share of approximately 28%. The region’s strong emphasis on health and wellness, coupled with regulatory support for omega-3 health claims, has driven substantial demand for fish oil-based products. Countries such as Norway, Denmark, and Iceland lead in fish oil production due to their established fishing industries and extensive marine resources. The European market also places considerable focus on sustainability, with a preference for certified fish oil sourced from sustainable fisheries. Aquaculture applications play a pivotal role in the region, with fish oil serving as a vital component in high-quality aquafeed to support the growth of farmed fish, especially salmon.
Key players
- Croda International plc
- Pelagia A/S
- Sürsan
- Ocean Group Ltd
- GC Rieber
- BASF SE
- DSM
- Omega Protein Corporation
- Triple Nine
- OLVEA Group
Competitive Analysis
The fish oil market is highly competitive, with key players focusing on innovation, sustainable sourcing, and expanding their product portfolios to gain a competitive edge. Companies like Croda International plc and BASF SE leverage their extensive R&D capabilities to develop high-quality omega-3 products tailored for diverse applications, from pharmaceuticals to dietary supplements. DSM and Omega Protein Corporation prioritize strategic acquisitions and partnerships to strengthen their global footprint and meet rising consumer demand for omega-3-enriched products. Sustainability and traceability remain critical factors, with companies such as Pelagia A/S and OLVEA Group committing to responsible sourcing practices to address environmental concerns. Market participants face competition from emerging players, making differentiation through advanced extraction techniques and customer-centric product offerings vital for maintaining market leadership.
Recent Developments
- In 2024, Croda reported a sequential improvement in sales driven by their Consumer Care and Industrial Specialties segments. The company highlighted its focus on sustainable ingredients and innovation, particularly in life sciences, with new drug delivery technologies like novel lipid-based adjuvants contributing to sales growth (June 2024).
- In March 2024, Pelagia announced the acquisition of UK-based seafood trading firm Ideal Foods Limited to strengthen its global supply chain and enhance its market position by advancing the use of seafood by-products. Additionally, in August 2024, Pelagia acquired the Epax Omega-3 business from FMC, expanding its portfolio of refined marine oils for human consumption.
- In June 2024, GC Rieber VivoMega opened a new omega-3 manufacturing facility in Norway, doubling its production capacity for triglyceride marine omega-3s and vegan algal oils. This facility operates on 100% renewable energy. In March 2024, GC Rieber also launched Vivomega EPA+DHA Algae Oil in the North American market at Expo West.
- In June 2024, BASF SE entered into a strategic partnership with DSM to co-develop and market high-purity omega-3 products aimed at the nutraceutical sector.
Market Concentration and Characteristics
The fish oil market is characterized by a moderately concentrated structure, with a mix of established multinational corporations and regional players competing for market share. Major companies such as Croda International, BASF SE, DSM, and Omega Protein Corporation dominate the global market through their extensive product portfolios, innovative capabilities, and commitment to sustainability. The market's competitive landscape is shaped by strong consumer demand for high-quality omega-3 products, advancements in extraction and purification technologies, and increasing emphasis on sustainable and traceable sourcing. Market concentration is further influenced by regional dynamics, with key players often forming strategic partnerships and engaging in mergers and acquisitions to expand their geographical reach and enhance production capabilities. Smaller players also contribute to market diversity by offering niche products and emphasizing ethical sourcing practices.
Report Coverage
The research report offers an in-depth analysis based on Species, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The growing global awareness of omega-3 fatty acids' health benefits will continue driving demand for fish oil-based supplements across age groups, enhancing market expansion.
- Industry players will increasingly adopt sustainable and traceable sourcing practices to meet consumer and regulatory demands, ensuring long-term availability of marine resources and reducing environmental impact.
- Advancements in extraction and purification techniques, such as supercritical CO2 extraction, will improve fish oil quality, yield, and stability, broadening its application scope and enhancing market competitiveness.
- Fish oil will witness growing incorporation into functional foods and beverages, driven by consumer preferences for fortified products aimed at preventive health and wellness.
- Expansion in aquaculture practices, particularly in Asia-Pacific, will sustain high demand for fish oil as a key ingredient in nutritionally balanced and high-quality aquafeed formulations.
- The fish oil market may face competition from plant-based omega-3 alternatives like algal oil, prompting companies to diversify offerings and address varying consumer preferences.
- Favorable regulatory frameworks across major markets will bolster the credibility of fish oil products, enabling manufacturers to capitalize on health claims related to cardiovascular and cognitive health.
- Fish oil-derived omega-3 concentrates will see increased adoption in pharmaceutical formulations for chronic disease management, offering a significant growth avenue in the market.
- Rising health awareness and increasing disposable incomes in emerging economies, particularly in Latin America and Asia-Pacific, will open new growth opportunities for fish oil products in diverse applications.
- Manufacturers will develop new product formats, such as gummies, soft gels, and liquid emulsions, to cater to evolving consumer demands for convenient, palatable, and easy-to-consume fish oil products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Fish Oil market in 2023 and 2032, and what is its CAGR?**
What drives the growth of the Fish Oil market?**
Which regions hold the largest shares of the Fish Oil market?**
What applications utilize fish oil the most?
How does sustainability influence the Fish Oil market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fish Oil Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fish Oil Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 3,183.25 million → 2032: USD 4,812.72 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fish Oil Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fish Oil Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fish Oil Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fish Oil Market Drivers
- 3.3 Fish Oil Market Restraints & Challenges
- 3.4 Fish Oil Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fish Oil Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fish Oil Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fish Oil category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fish Oil Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Fish Oil Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Fish Oil market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fish Oil Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fish Oil Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Fish Oil Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fish Oil (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Fish Oil Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fish Oil Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Fish Oil Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fish Oil Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fish Oil Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fish Oil Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fish Oil Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fish Oil Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fish Oil Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
