
Market Overview
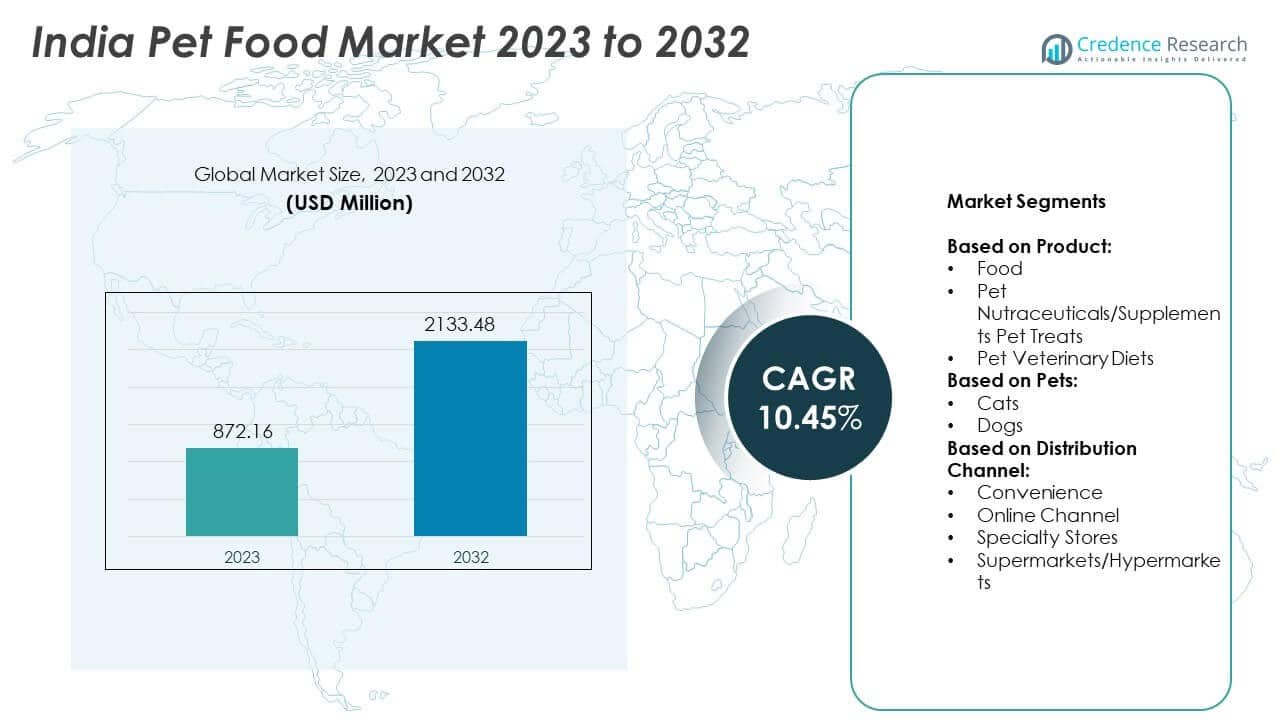
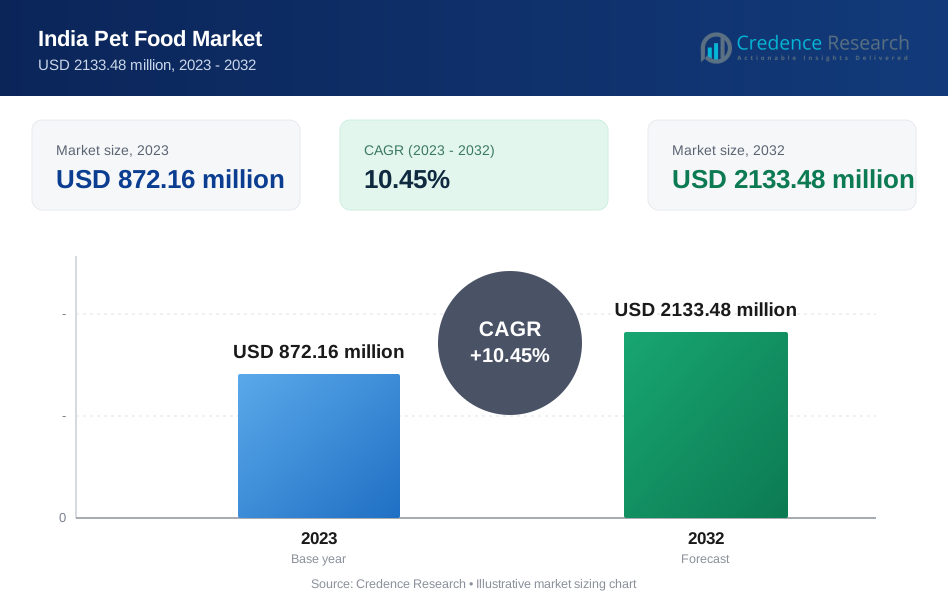
India Pet Food Market size was valued at USD 872.16 million in 2024 and is anticipated to reach USD 2133.48 million by 2032, at a CAGR of 10.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Pet Food Market Size 2024 | USD 872.16Million |
| India Pet Food Market, CAGR | 10.45% |
| India Pet Food Market Size 2032 | USD 2133.48 Million |
The India Pet Food market grows steadily, supported by rising pet ownership, urban lifestyle shifts, and increasing awareness of pet health and nutrition. Higher disposable incomes and pet humanization encourage demand for premium, functional, and breed-specific diets. Expanding e-commerce and organized retail strengthen product accessibility, while veterinarians influence choices toward nutritionally balanced food. Trends highlight strong momentum in natural, organic, and preservative-free formulations, along with sustainable packaging solutions.
The India Pet Food market shows strong regional presence across the Southern, Northern, Western, Eastern, and emerging offshore regions, with urban hubs such as Bengaluru, Delhi NCR, Mumbai, and Kolkata driving significant demand. Rising disposable incomes and growing awareness of pet nutrition support market expansion across metropolitan and semi-urban cities, while digital channels extend reach into smaller towns. Key players shaping the industry include Mars Incorporated, Nestle Purina, and IB Group (Drools Pet Food Pvt. Ltd.). Companies such as Colgate-Palmolive (Hill’s Pet Nutrition) further strengthen competition by offering specialized and premium formulations tailored to evolving consumer needs.
Market Insights
- The India Pet Food market was valued at USD 872.16 million in 2023 and is projected to reach USD 2133.48 million by 2032, growing at a CAGR of 10.45% during the forecast period.
- Rising pet ownership, urbanization, and humanization of pets drive consistent demand for nutritionally balanced and premium food products.
- Trends indicate strong consumer interest in natural, organic, and preservative-free formulations, along with sustainable packaging and functional diets addressing specific health needs.
- Competition intensifies with multinational companies like Mars Incorporated, Nestle Purina, and Colgate-Palmolive (Hill’s Pet Nutrition) competing against domestic players such as IB Group (Drools), supported by innovation and pricing strategies.
- High price sensitivity in semi-urban and rural regions, combined with limited awareness of nutritional benefits, acts as a restraint, slowing penetration outside metro markets.
- Regional growth remains strongest in the Southern and Northern regions with urban hubs leading adoption, while Western and Eastern regions show expanding demand supported by digital platforms and retail networks.
- The market reflects a clear transition from home-cooked feeding practices to scientifically formulated options, supported by veterinarians, online platforms, and evolving consumer preferences that ensure long-term growth potential.
Market Drivers
Rising Pet Ownership and Humanization of Pets
The India Pet Food market benefits from a steady rise in pet ownership, driven by urbanization, nuclear families, and changing lifestyles. Pet humanization shapes consumer choices, with owners demanding premium nutrition for their companions. Growing awareness of pet health promotes specialized diets that support immunity, digestion, and overall vitality. It reflects a shift from traditional home-cooked feeding toward scientifically formulated products. Middle-class households increasingly view pets as family members, which stimulates demand for branded and nutritionally balanced food. Expanding awareness campaigns by veterinarians and industry players further enhance the adoption of packaged pet food.
- For instance, Nestlé Purina expanded its e-commerce presence by partnering with over 30 online retailers in Asia and reported a 28% increase in online pet food sales by the year 2023.
Expanding Availability through Modern Retail and E-Commerce
The India Pet Food market gains momentum through improved accessibility in organized retail and online channels. Supermarkets, hypermarkets, and specialty stores broaden distribution networks across urban centers. E-commerce platforms provide convenience and product variety, attracting tech-savvy and busy consumers. It strengthens reach to Tier II and Tier III cities, where digital adoption accelerates. Subscription-based delivery models encourage recurring purchases, creating consistent revenue streams. Growing partnerships between manufacturers and e-retailers expand market penetration and consumer trust.
- For instance, Hill’s Pet Nutrition invests over 180 million annually in R&D and employs more than 220 veterinarians and Ph.D. nutritionists to design therapeutic diets for chronic pet conditions.
Increasing Health and Nutrition Awareness among Pet Owners
The India Pet Food market experiences growth due to rising focus on animal health and preventive care. Owners prefer foods fortified with proteins, vitamins, and minerals to ensure balanced nutrition. Functional and therapeutic diets addressing obesity, joint issues, or skin conditions gain traction. It reflects a deeper understanding of dietary needs shaped by veterinary advice and scientific research. Demand for natural, organic, and preservative-free formulations continues to rise. Pet food brands capitalize on this shift by promoting transparency in ingredients and production processes.
Rising Disposable Income and Premiumization Trends
The India Pet Food market expands in line with increasing disposable incomes and higher willingness to spend on premium products. Urban consumers favor specialized formulas such as grain-free, breed-specific, or age-specific food. It strengthens the segment of super-premium brands catering to discerning buyers. Marketing strategies highlighting quality, safety, and international standards appeal strongly to affluent households. Growing influence of global pet care trends accelerates demand for imported and innovative offerings. This premiumization wave creates differentiation opportunities for both domestic and multinational players.
Market Trends
Growing Demand for Premium and Specialized Pet Food
The India Pet Food market shows a clear trend toward premium and specialized nutrition. Pet owners increasingly prefer products designed for specific breeds, age groups, or dietary needs. It drives innovation in grain-free, high-protein, and organic formulations. Veterinary recommendations and rising health consciousness fuel the adoption of functional diets that address joint health, digestion, or weight management. Imported brands gain visibility, but domestic players also expand premium portfolios. This shift highlights the evolving expectations of consumers seeking high-quality and customized pet nutrition.
- For instance, Farmina Pet Foods introduced over 45 premium formulas across its N&D range, supported by clinical trials on more than 4,000 dogs and cats in collaboration with veterinary universities.
Rising Influence of E-Commerce and Digital Platforms
The India Pet Food market benefits from the rapid adoption of e-commerce platforms and mobile applications. Online retail ensures greater accessibility, wider assortments, and competitive pricing. It enables consumers in smaller towns to access global and domestic brands with ease. Subscription models and auto-replenishment services drive repeat purchases and build brand loyalty. Social media engagement and digital campaigns strengthen consumer awareness and influence purchasing decisions. The digital ecosystem emerges as a critical growth enabler for both established and emerging brands.
- For instance, Amazon India reported that its pet supplies category grew by over 40% year-on-year in 2023, with more than 1.5 million customers purchasing pet food and accessories through its platform.
Shift Toward Natural and Sustainable Pet Food Products
The India Pet Food market witnesses rising preference for natural and environmentally responsible options. Consumers opt for products made with organic ingredients, free from preservatives and artificial additives. It reflects a broader sustainability movement shaping global consumer behavior. Manufacturers experiment with plant-based proteins, recyclable packaging, and ethically sourced ingredients. Demand for transparency in sourcing and labeling reinforces this trend. Growing alignment with eco-conscious values positions natural and sustainable pet food as a long-term growth driver.
Expansion of Domestic Manufacturing and Innovation
The India Pet Food market advances through capacity expansion and product innovation by domestic manufacturers. Local players invest in research facilities to develop recipes suited to regional preferences and climatic conditions. It enables cost efficiency and supports competitive pricing against imports. Multinationals collaborate with Indian partners to strengthen supply chains and reach underserved markets. Product portfolios diversify into treats, supplements, and wet food to cater to evolving demands. This focus on innovation and localized production fosters resilience and accelerates market maturity.
Market Challenges Analysis
High Price Sensitivity and Limited Awareness in Non-Metro Regions
The India Pet Food market faces challenges due to strong price sensitivity among consumers, particularly outside metropolitan areas. Many pet owners in Tier II and Tier III cities still rely on home-cooked food for affordability and familiarity. It restricts the adoption of branded pet food despite growing pet ownership. Limited awareness of nutritional benefits further slows market penetration in semi-urban and rural regions. Manufacturers struggle to balance affordability with quality, especially in the premium category. Competitive pricing pressure hinders wider acceptance of advanced formulations.
Supply Chain Constraints and Regulatory Complexities
The India Pet Food market also encounters obstacles related to distribution, logistics, and compliance standards. Supply chain gaps in cold storage and transportation affect the availability of wet and specialized food. It increases costs for manufacturers and reduces product freshness in smaller towns. Regulatory frameworks governing imports, labeling, and safety standards remain fragmented and difficult to navigate. Smaller companies find compliance costly, which restricts innovation and expansion. Complex distribution structures and lack of streamlined policies create barriers to scaling operations efficiently.
Market Opportunities
Expansion in Untapped Regional Markets and Rising Middle-Class Adoption
The India Pet Food market presents significant opportunities in Tier II and Tier III cities, where pet ownership is expanding rapidly. Rising disposable incomes and lifestyle changes in these regions create new demand for branded and nutritious food. It allows manufacturers to introduce affordable product lines that cater to cost-sensitive households while ensuring quality. Awareness campaigns led by veterinarians and pet care communities can accelerate adoption. Growing penetration of organized retail and online platforms further supports distribution. This expansion offers long-term growth potential by tapping into a wide consumer base beyond metros.
Innovation in Specialized Nutrition and Sustainable Offerings
The India Pet Food market is well-positioned to capitalize on demand for premium, health-focused, and eco-friendly products. Pet owners increasingly seek diets addressing weight control, joint care, skin health, and breed-specific needs. It creates space for functional food, supplements, and organic options. Innovation in plant-based protein formulas and sustainable packaging resonates with environmentally conscious buyers. Collaborations with veterinarians and nutrition experts enhance credibility and product differentiation. Companies that focus on specialized and sustainable offerings can strengthen brand loyalty and capture high-value segments.
Market Segmentation Analysis:
By Product:
The India Pet Food market demonstrates strong growth across product categories, with food remaining the dominant segment due to its role in daily nutrition. Pet nutraceuticals and supplements gain momentum as owners prioritize preventive health and functional benefits. It drives demand for vitamins, minerals, and probiotics that address immunity, digestion, and mobility. Pet treats represent a fast-expanding category, supported by their role in training, bonding, and indulgence. Veterinary diets serve a niche but important segment, meeting needs for weight control, kidney care, and skin health. Rising awareness of specialized nutrition strengthens the diversity and value of these product categories.
- For instance, Hill’s Pet Nutrition develops over 60 specialized veterinary diet formulas and invests in more than 180 clinical studies annually to validate therapeutic outcomes.
By Pet:
The India Pet Food market shows clear dominance of the dog segment, supported by the large base of dog owners in urban and semi-urban households. Dogs benefit from a wider product variety ranging from dry kibble to breed-specific formulations. It strengthens the revenue share of this segment while encouraging innovation in premium and functional diets. Cats account for a smaller but growing portion of demand, driven by rising adoption among younger consumers and nuclear families. Growth in cat ownership creates opportunities for specialized food and treats tailored to feline preferences. This shift broadens the overall market landscape by diversifying pet categories.
- For instance, Nestlé Purina Friskies brand offers a wide variety of cat food options globally, with over 50 distinct products. This extensive product line is backed by a dedicated team of over 500 nutritionist, behaviorists, and veterinarians who focus on developing innovative and beneficial food options specifically for cats
By Distribution Channel:
The India Pet Food market evolves rapidly through multiple distribution channels. Convenience stores provide accessibility for price-conscious buyers and those in smaller towns. Specialty stores play a critical role in urban centers, offering product variety and professional guidance to owners. It helps premium brands establish credibility and visibility among informed consumers. Online channels emerge as a leading growth driver, supported by subscription models, doorstep delivery, and wider reach. Supermarkets and hypermarkets contribute by improving shelf visibility and catering to impulse purchases. Together, these channels strengthen availability, ensuring that diverse consumer groups can access products aligned with their needs.
Segments:
Based on Product:
- Food
- Pet Nutraceuticals/Supplements Pet Treats
- Pet Veterinary Diets
Based on Pets:
- Cats
- Dogs
Based on Distribution Channel:
- Convenience
- Online Channel
- Specialty Stores
- Supermarkets/Hypermarkets
Based on the Geography:
- Western Region (Gujarat and Rajasthan)
- Eastern Region (Assam, Tripura, and West Bengal)
- Western Offshore Region
- Southern Region
- Northern Region
Regional Analysis
Western Region (Gujarat and Rajasthan)
The Western Region contributes a market share of 23% in the India Pet Food market, driven by rapid urbanization and rising middle-class households in Gujarat and Rajasthan. Major urban centers such as Ahmedabad, Surat, and Jaipur witness steady growth in pet ownership, supported by changing lifestyles and nuclear family structures. It encourages higher adoption of packaged pet food, particularly dry food and treats. The presence of organized retail chains and specialty stores improves availability, while online platforms strengthen penetration into semi-urban areas. Growing disposable incomes enhance willingness to spend on premium formulations, including nutraceuticals and veterinary diets. Rising awareness about pet health and nutrition ensures long-term demand stability in this region.
Eastern Region (Assam, Tripura, and West Bengal)
The Eastern Region holds a market share of 14%, reflecting moderate but rising adoption of branded pet food. West Bengal, with Kolkata as a key hub, dominates consumption due to its urban concentration and strong retail presence. It reflects growing acceptance of packaged food among cat owners, as felines gain popularity in urban households. Assam and Tripura show slower adoption because of lower awareness and reliance on home-cooked meals. Online channels provide a vital pathway to reach consumers across smaller towns. Veterinary influence and pet care campaigns play an important role in encouraging pet owners to shift toward nutritionally balanced products. Expanding distribution and targeted education remain critical growth drivers for this region.
Western Offshore Region
The Western Offshore Region accounts for 8% of the market share, reflecting its smaller consumer base but rising potential. Pet ownership in offshore industrial and port-related communities remains limited but gradually expanding. It encourages manufacturers to test niche opportunities through e-commerce and direct-to-consumer models. Limited physical retail infrastructure restricts product availability, yet digital channels help bridge this gap. It reflects growing interest in premium food among higher-income households located in offshore urban clusters. Veterinary clinics and pet service providers play a vital role in promoting awareness. With steady economic growth in these areas, the offshore region is expected to show gradual market expansion.
Southern Region
The Southern Region leads with the highest market share of 32%, driven by strong urban centers such as Bengaluru, Hyderabad, and Chennai. High literacy rates and awareness among pet owners accelerate the adoption of premium and specialized food. It supports robust growth in nutraceuticals, supplements, and treats, reflecting a demand for advanced nutrition. Specialty stores, veterinary clinics, and online platforms strengthen distribution networks in this region. Rising disposable incomes and a growing trend of nuclear families increase pet adoption rates. Demand for breed-specific, functional, and organic food sees strong traction, positioning the South as a hub of innovation. The presence of multinational and domestic manufacturers further strengthens product availability and brand visibility.
Northern Region
The Northern Region captures a market share of 23%, supported by large pet-owning populations in Delhi NCR, Punjab, and Haryana. Strong economic growth and urban affluence encourage consumers to invest in high-quality pet food. It boosts demand for dry food, treats, and veterinary diets across diverse consumer groups. Specialty retail outlets, supermarkets, and hypermarkets enhance accessibility in metropolitan and semi-urban cities. The growing influence of digital channels expands reach into smaller towns. Rising pet adoption among young professionals and families supports market stability. The North remains a highly competitive region where premium and mass-market brands compete strongly for consumer attention.
Key Player Analysis
- Mars Incorporated
- IB Group (Drools Pet Food Pvt. Ltd.)
- General Mills Inc.
- Nestle (Purina)
- Schell & Kampeter Inc. (Diamond Pet Foods)
- Colgate-Palmolive Company (Hill’s Pet Nutrition Inc.)
- Farmina Pet Foods
- Charoen Pokphand Group
- Adm
Competitive Analysis
The leading players in the India Pet Food market include Mars Incorporated, Nestle Purina, Colgate-Palmolive (Hill’s Pet Nutrition), IB Group (Drools Pet Food Pvt. Ltd.), General Mills Inc., Farmina Pet Foods, ADM, Charoen Pokphand Group, and Schell & Kampeter Inc. (Diamond Pet Foods).These companies compete through diverse portfolios, strong distribution networks, and continuous innovation in nutrition-focused products. Global leaders emphasize premiumization, introducing specialized formulas such as grain-free, breed-specific, and functional diets that align with global health trends. Domestic manufacturers leverage cost efficiency and local consumer insights to deliver affordable options that appeal to price-sensitive households, strengthening their presence in Tier II and Tier III cities. E-commerce partnerships and subscription-based delivery models enhance reach and customer loyalty, especially among younger urban consumers. Strategic marketing, veterinarian endorsements, and sustainability-driven initiatives, including natural ingredients and eco-friendly packaging, further reinforce competitive positioning. Innovation in pet treats, supplements, and veterinary diets diversifies offerings, enabling players to address evolving preferences. While global players dominate the premium space, local brands focus on accessibility and affordability, creating a balanced competitive landscape that reflects both international influence and strong domestic adaptability.
Recent Developments
- In July 2025, General Mills company launched its Edgard & Cooper and fresh Blue Buffalo initiatives following its April 2025 acquisition of Edgard & Cooper to strengthen its premium pet food portfolio
- In July 2025, Nestlé Purina expanded its Friskies cat food line in India, introducing two new dry variants under the Meaty Grills range
- In January 2024, Mars Petcare India reported double‑digit year‑over‑year growth in South Asia’s largest pet food market
Market Concentration & Characteristics
The India Pet Food market displays moderate concentration, with a mix of multinational leaders and strong domestic players shaping its structure. Global companies dominate the premium and specialized nutrition segment through established brand recognition, research capabilities, and wide distribution networks. It reflects steady competition from domestic manufacturers that focus on affordability, local taste preferences, and cost-efficient production, gaining traction in price-sensitive regions. The market exhibits characteristics of rapid innovation, with rising demand for organic, grain-free, and functional diets that cater to evolving consumer expectations. E-commerce platforms and specialty retail channels enhance accessibility, while veterinarian influence reinforces adoption of branded products. It demonstrates dynamic growth potential with both premium and mass-market players coexisting, driving balanced competition across diverse consumer segments.
Report Coverage
The research report offers an in-depth analysis based on Product, Pet, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The India Pet Food market will expand steadily with rising pet ownership in urban and semi-urban households.
- Premium and specialized diets will gain stronger traction among health-conscious pet owners.
- E-commerce platforms will drive greater accessibility and penetration into smaller towns and cities.
- Functional and therapeutic diets addressing specific health needs will see higher adoption.
- Domestic manufacturers will expand product lines to compete with international brands.
- Natural, organic, and sustainable formulations will become central to consumer preferences.
- Veterinary recommendations will continue to shape demand for nutritionally balanced products.
- Investment in localized production and innovation will enhance cost efficiency and reach.
- Digital marketing, subscription models, and social media engagement will strengthen customer loyalty.
- The market will evolve into a more competitive space with both global and regional players focusing on differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Pet Ownership and Humanization
Urbanization, nuclear families, and changing lifestyles in India are driving a steady increase in pet ownership. As pets are increasingly viewed as family members, owners are seeking premium, nutritionally balanced food, shifting away from traditional home-cooked diets.
Expanding E-Commerce and Organized Retail
The growth of online platforms and organized retail chains has made pet food more accessible, especially in Tier II and Tier III cities. E-commerce enables a wider product assortment and convenience, while retail expansion improves shelf visibility and product availability.
Increasing Health and Nutrition Awareness
Pet owners are becoming more aware of the importance of preventive care and balanced nutrition, leading to higher demand for functional, therapeutic, and specialized diets. Veterinary recommendations and transparent ingredient labeling further support this trend.
Rising Disposable Income and Premiumization
Higher disposable incomes, particularly in urban and semi-urban areas, are fueling demand for premium, breed-specific, and functional pet food products. This premiumization trend is supported by marketing strategies that emphasize quality, safety, and international standards.
Shift Toward Natural and Sustainable Products
Growing consumer preference for natural, organic, and preservative-free pet food, along with sustainable packaging, is shaping product innovation. Brands that focus on eco-friendly and health-oriented offerings are capturing the attention of environmentally conscious pet owners.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Pet Food market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Pet Food Market projected to grow between 2025 and 2032?
Which India Pet Food market segment held the largest share in 2023?
What are the primary factors fueling the growth of the India Pet Food market?
Who are the leading companies in the India Pet Food Market?
Which region commanded the largest share of the India Pet Food market in 2023?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Pet
- 1.2.1 Dogs
- 1.2.2 Cats
- 1.3 By Product
- 1.3.1 Food
- 1.3.2 Pet Nutraceuticals/Supplements
- 1.3.3 Pet Treats
- 1.3.4 Pet Veterinary Diets
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 872.16 million → 2032: USD 2133.48 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Pet Food Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Pet Food Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Pet Food Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Pet Food Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Pet Food Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Pet Food Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Pet Food Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Pet Food Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 872.16 million → 2032: USD 2133.48 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Pet Food Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Pet - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dogs
- 12.3.7.2 Cats
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food
- 12.4.7.2 Pet Nutraceuticals/Supplements
- 12.4.7.3 Pet Treats
- 12.4.7.4 Pet Veterinary Diets
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 India Pet Food Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 India Pet Food Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 India Pet Food Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Mars Incorporated
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Nestle (Purina)
- 17.4 IB Group (Drools Pet Food Pvt. Ltd.)
- 17.5 Colgate-Palmolive Company (Hill’s Pet Nutrition Inc.)
- 17.6 General Mills Inc.
- 17.7 Farmina Pet Foods
- 17.8 Charoen Pokphand Group
- 17.9 ADM
- 17.10 Schell & Kampeter Inc. (Diamond Pet Foods)
- 17.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
