
Market Overview:
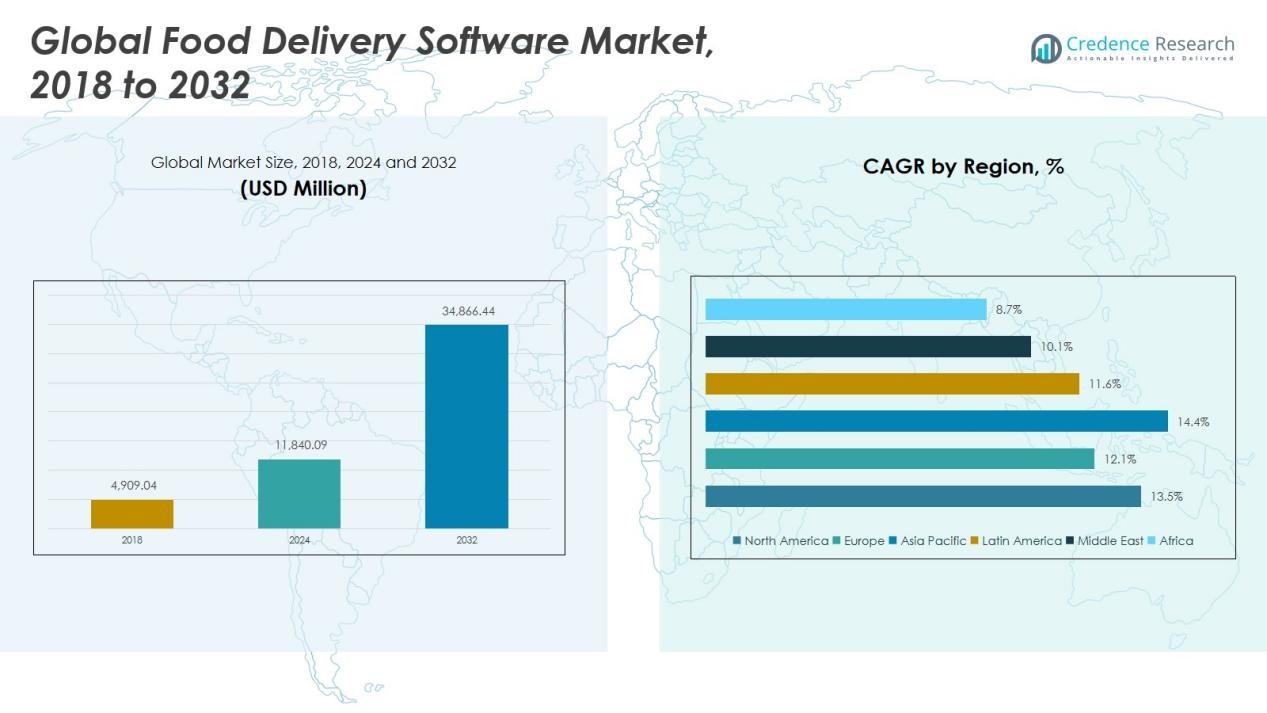
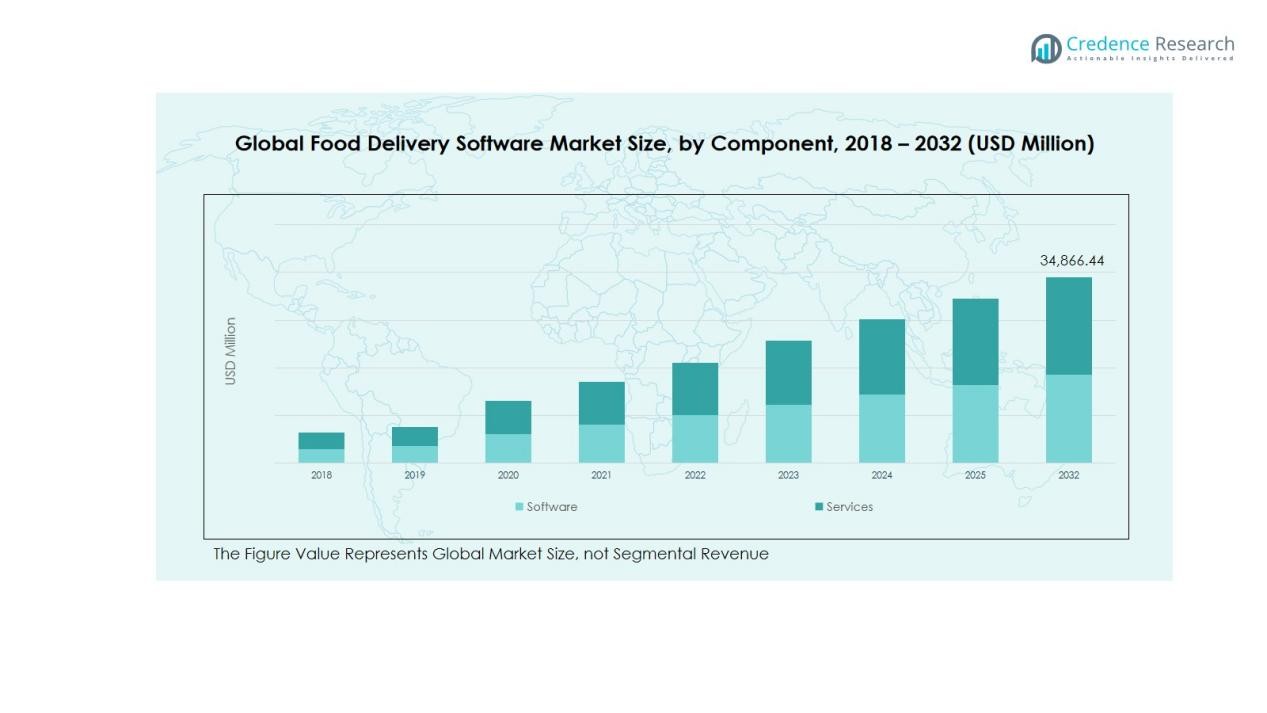
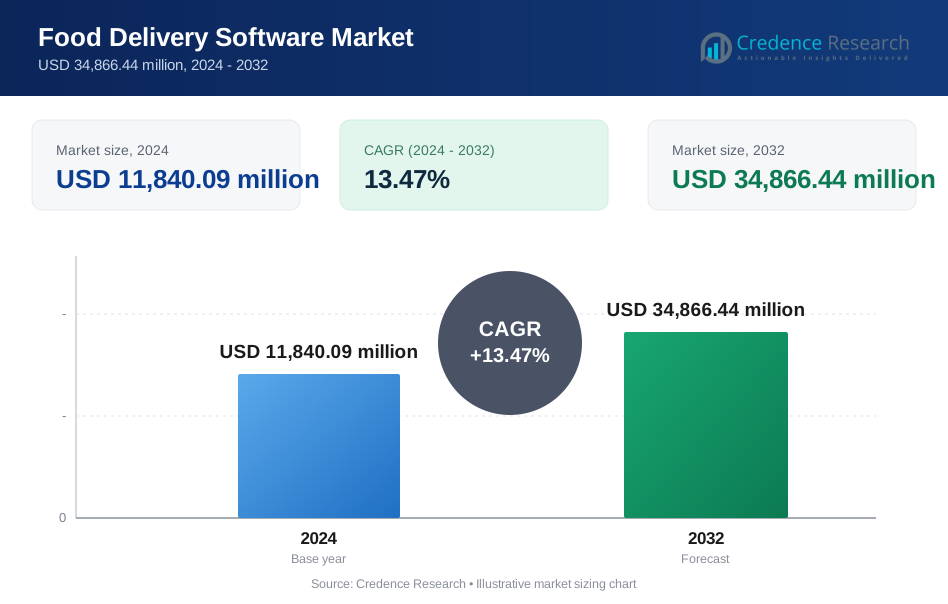
The Global Food Delivery Software Market size was valued at USD 4,909.04 million in 2018 to USD 11,840.09 million in 2024 and is anticipated to reach USD 34,866.44 million by 2032, at a CAGR of 13.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Delivery Software Market Size 2024 | USD 11,840.09 Million |
| Food Delivery Software Market, CAGR | 13.47% |
| Food Delivery Software Market Size 2032 | USD 34,866.44 Million |
Rising consumer preference for convenience and contactless services continues to drive demand for advanced food delivery software solutions. Features such as AI-based route optimization, order tracking, real-time analytics, and automated dispatching enhance operational efficiency and customer satisfaction. Cloud-based deployment and integration with digital payment systems are further improving scalability and reliability, benefiting small and large food service operators alike.
Regionally, North America leads the market due to high smartphone penetration, strong internet connectivity, and a mature online food delivery ecosystem. Europe follows, supported by increased demand for sustainable and efficient logistics platforms. The Asia-Pacific region is expected to witness the fastest growth, driven by rapid urbanization, expanding digital infrastructure, and the popularity of online food ordering platforms in countries like China, India, and Indonesia.
Market Insights:
- The Global Food Delivery Software Market was valued at USD 4,909.04 million in 2018, reached USD 11,840.09 million in 2024, and is projected to attain USD 34,866.44 million by 2032, growing at a CAGR of 13.47% during the forecast period.
- North America holds 32% of the market, driven by strong internet infrastructure, advanced logistics, and leading players such as DoorDash and Uber Eats. Europe accounts for 24% share due to high digital literacy and sustainability-focused delivery networks, while Asia Pacific leads with 35% share supported by rapid urbanization, digital payments, and large user bases in China and India.
- Asia Pacific is the fastest-growing region, expected to continue expanding due to government support for cashless economies, increasing mobile penetration, and growing adoption of aggregator platforms.
- The software segment dominates with over 65% of total market revenue in 2024, supported by the rising demand for integrated delivery management and real-time tracking solutions.
- The mobile-based platform segment accounts for nearly 70% share, driven by app-based food ordering convenience and the growing use of smartphones for quick, contactless transactions.
Market Drivers:
Growing Digitalization and Expansion of Online Food Ordering Platforms
The Global Food Delivery Software Market grows rapidly with rising digital adoption across the food service sector. Increasing internet and smartphone penetration supports higher demand for seamless online ordering experiences. Restaurants and cloud kitchens use these platforms to manage high order volumes efficiently. Integration with digital payment gateways and loyalty programs strengthens customer engagement and transaction speed. It continues to benefit from the global shift toward app-based dining and doorstep delivery.
- For instance, in the first quarter (Q1) of 2025, DoorDash reported a record 732 million total orders processed through its platform, an 18% increase year-over-year, highlighting the scalability and reach enabled by digital integration."
Integration of Advanced Technologies to Enhance Operational Efficiency
Automation and AI technologies drive strong improvements in delivery accuracy and speed. Predictive analytics, GPS tracking, and route optimization software reduce operational delays and fuel costs. The use of machine learning enables demand forecasting and better resource allocation. It helps businesses improve efficiency and minimize errors in peak hours. These advancements make delivery operations more responsive and profitable for food service providers.
- For Instance, UPS deployed its ORION (On-Road Integrated Optimization and Navigation) system that analyzes over 200,000 routes per minute, resulting in annual fuel savings of approximately 10 million gallons and reducing carbon emissions by 100,000 metric tons annually.
Rising Consumer Demand for Convenience and Contactless Services
Consumer preference for convenience plays a key role in shaping the market. Growing urban lifestyles and busy schedules push customers toward faster delivery and easy-to-use mobile apps. The pandemic accelerated the need for safe, contactless transactions supported by digital delivery platforms. It has led food chains and aggregators to expand technology-based solutions for improved safety and accessibility. The trend continues with personalized menu suggestions and faster service delivery.
Expanding Cloud-Based Solutions and Restaurant Management Integration
Cloud-based delivery software adoption is rising across restaurants of all sizes. These solutions support multi-location management, data synchronization, and cost efficiency. Integration with POS systems, CRM tools, and inventory platforms enables real-time data sharing. It allows businesses to improve visibility across delivery operations and customer touchpoints. The trend supports scalability and reduces infrastructure costs for delivery service providers.
Market Trends:
Adoption of Artificial Intelligence, Automation, and Predictive Analytics in Delivery Operations
The Global Food Delivery Software Market is witnessing strong adoption of artificial intelligence and automation across delivery networks. AI-powered tools predict demand, optimize driver routes, and analyze consumer behavior to improve service precision. Predictive analytics helps restaurants manage order peaks and reduce waste through accurate forecasting. Automation in order processing and communication enhances delivery speed and reliability. Chatbots and voice assistants are improving customer engagement by providing real-time updates and support. It enables food delivery companies to make data-driven decisions and reduce manual intervention. Integration of machine learning with backend systems strengthens logistics and customer experience management.
- For instance, Swiggy processes over 2 million orders daily through its AI and machine learning systems that handle real-time micro-optimization of dynamic demand-supply across millions of operations each day, achieving performance improvements like a reported 2x latency improvement in its ML and AI platform for faster prediction serving.
Rise of Cloud-Based, Multi-Channel, and Sustainable Delivery Platforms
Cloud-based delivery systems are gaining traction for their scalability and remote management benefits. Restaurants prefer unified platforms that connect mobile apps, web portals, and social media channels for order management. Multi-channel ordering helps brands reach a broader customer base while maintaining consistent service quality. The growing emphasis on eco-friendly and sustainable logistics solutions is reshaping business models. Electric bikes, optimized packaging, and carbon footprint tracking are becoming major differentiators among service providers. It also supports the adoption of subscription-based and SaaS models for better affordability and flexibility. Continuous innovation in integration tools and API-driven systems drives seamless connectivity across payment gateways, POS systems, and inventory software.
- For Instance, Starbucks was in the process of rolling out an AI-powered inventory counting system, developed in partnership with NomadGo, across more than 11,000 North American company-owned stores, with full integration anticipated by the end of September 2025.
Market Challenges Analysis:
High Operational Costs and Complex Logistics Management
The Global Food Delivery Software Market faces significant pressure from high operational and logistics costs. Maintaining real-time tracking systems, data security, and seamless integrations demands continuous investment. Smaller restaurants struggle with subscription fees and technical upgrades required to stay competitive. It often faces challenges in optimizing last-mile delivery due to traffic congestion and unpredictable demand patterns. Driver shortages and fluctuating fuel costs further impact profitability for service providers. Balancing customer expectations for fast delivery with operational efficiency remains a key challenge.
Data Privacy, Cybersecurity Risks, and Platform Dependence
Rising concerns over data breaches and cybersecurity threats create hurdles for digital food delivery platforms. Storing sensitive user and payment data increases vulnerability to hacking and unauthorized access. Frequent software updates and compliance with global data protection laws add to the operational burden. It must also address dependence on third-party apps and servers that can cause downtime or service disruption. Customer dissatisfaction due to delayed responses or technical glitches can damage brand trust. Managing system reliability while ensuring privacy remains a core issue for market stability.
Market Opportunities:
Expansion into Emerging Markets and Untapped Demographics
The Global Food Delivery Software Market offers strong opportunities in emerging economies with expanding digital infrastructure. Rising internet access and smartphone penetration in countries across Asia-Pacific, Latin America, and Africa create new customer bases. Growing urbanization and younger demographics with higher disposable income support rapid adoption. It can benefit from local partnerships with restaurants and logistics providers to strengthen regional networks. Multilingual interfaces and localized payment options further improve market penetration. Government initiatives promoting digital commerce also provide a supportive environment for expansion.
Integration of Advanced Technologies and Sustainable Delivery Solutions
Artificial intelligence, IoT, and blockchain present new possibilities for innovation in food delivery software. Automation in order processing and smart route optimization can lower costs and improve service quality. It can leverage data analytics to design personalized experiences and predictive order management. Integration with electric or drone-based delivery fleets offers an edge in sustainability. The rising demand for green logistics and recyclable packaging solutions opens new revenue streams. Subscription-based cloud models and white-label solutions also expand access for small and medium restaurants. These advancements create long-term growth opportunities through efficiency and differentiation.
Market Segmentation Analysis:
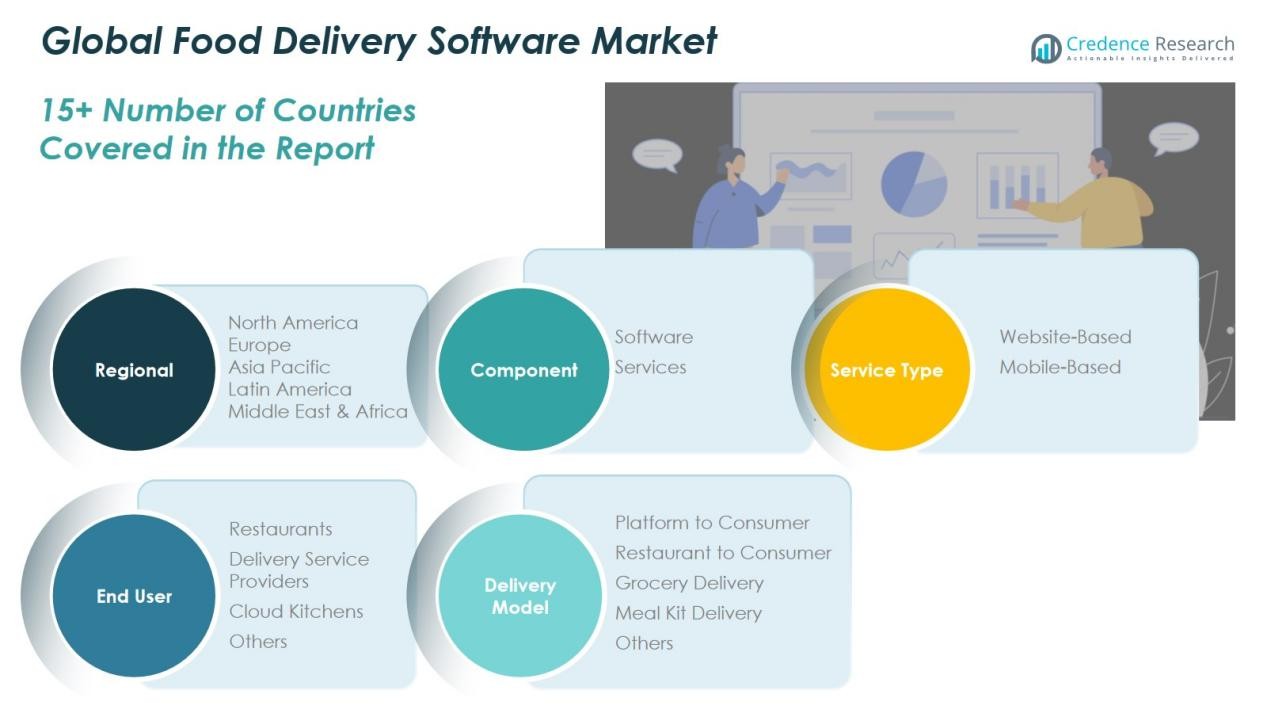
By Component
The Global Food Delivery Software Market is segmented by component into software and services. The software segment holds the dominant share due to its essential role in order management, real-time tracking, and customer engagement. Restaurants and aggregators rely on these systems to automate delivery operations and analyze customer data. The services segment grows steadily, driven by demand for system integration, maintenance, and cloud support. It supports operational efficiency and enhances user experience through continuous technical upgrades.
- For instance, DoorDash's order management infrastructure processes 1.2 million queries per second across 300+ database clusters, managing 1.9 petabytes of data to deliver seamless order automation and real-time customer insights to thousands of restaurants simultaneously.
By Type
The market divides by type into website-based and mobile-based platforms. Mobile-based software leads due to higher smartphone adoption and preference for app-based ordering. It offers better user convenience, location-based features, and push notifications that increase customer retention. Website-based platforms continue to serve customers who prefer desktop ordering and larger screen interfaces. It remains relevant for corporate clients and high-volume restaurant chains seeking multi-device compatibility.
- For instance, Toast POS, which has expanded its footprint to over 99,000 U.S. restaurants by 2023, provides comprehensive web-based restaurant management solutions including online ordering, delivery, takeout services, and inventory management.
By Delivery Model
The market classifies delivery models into platform-to-consumer, restaurant-to-consumer, grocery delivery, meal kit delivery, and others. The platform-to-consumer segment leads due to the popularity of aggregator apps offering diverse restaurant options. Restaurant-to-consumer models grow steadily with established brands building in-house delivery systems. Grocery and meal kit delivery segments show strong potential due to changing consumption habits and rising demand for convenience-driven food services.
Segmentations:
By Component:
- Software
- Services
- By Type:
- Website-Based
- Mobile-Based
By End User:
- Restaurants
- Delivery Service Providers
- Cloud Kitchens
- Others
By Delivery Model:
- Platform to Consumer
- Restaurant to Consumer
- Grocery Delivery
- Meal Kit Delivery
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Food Delivery Software Market size was valued at USD 1,606.95 million in 2018 to USD 3,822.11 million in 2024 and is anticipated to reach USD 11,297.10 million by 2032, at a CAGR of 13.5% during the forecast period. North America holds 32% of the Global Food Delivery Software MarketMarket. High smartphone penetration, advanced internet infrastructure, and growing adoption of online food services fuel regional growth. It benefits from strong participation of established players such as DoorDash, Uber Eats, and Grubhub. Continuous innovation in automation, AI-driven route planning, and payment integration enhances operational efficiency. The region also sees increasing investments in green and electric delivery fleets to support sustainability goals.
Europe
The Europe Food Delivery Software Market size was valued at USD 890.23 million in 2018 to USD 2,026.05 million in 2024 and is anticipated to reach USD 5,408.40 million by 2032, at a CAGR of 12.1% during the forecast period. Europe accounts for 24% of the Global Food Delivery Software MarketMarket. The region’s growth is driven by high digital literacy, urban population density, and expansion of cloud kitchens. It witnesses strong regulatory support for digital commerce and data privacy. Leading companies such as Deliveroo and Just Eat Takeaway are expanding AI-enabled delivery systems and eco-friendly logistics. The region emphasizes sustainable delivery practices and electric mobility integration. Increasing partnerships between restaurants and digital platforms continue to strengthen the competitive landscape.
Asia Pacific
The Asia Pacific Food Delivery Software Market size was valued at USD 2,038.40 million in 2018 to USD 5,107.45 million in 2024 and is anticipated to reach USD 16,004.03 million by 2032, at a CAGR of 14.4% during the forecast period. Asia Pacific holds 35% of the Global Food Delivery Software MarketMarket. Rapid urbanization, large youth demographics, and expanding digital payment ecosystems drive market adoption. Strong presence of key players such as Zomato, Swiggy, and Meituan enhances market competitiveness. It benefits from government initiatives promoting cashless economies and digital transformation. The increasing role of cloud kitchens and aggregator platforms improves delivery efficiency and affordability. The region continues to experience innovation in automation and real-time tracking systems.
Latin America
The Latin America Food Delivery Software Market size was valued at USD 216.60 million in 2018 to USD 515.47 million in 2024 and is anticipated to reach USD 1,331.07 million by 2032, at a CAGR of 11.6% during the forecast period. Latin America holds 6% of the Global Food Delivery Software MarketMarket. The region shows steady adoption due to rising smartphone use and improved internet connectivity. Local players are collaborating with restaurants to expand service coverage in urban areas. It faces infrastructure challenges, yet digital transformation in logistics creates new opportunities. Brazil and Mexico remain the leading markets, supported by rising middle-class spending and convenience-oriented lifestyles. Expansion of digital payment gateways and loyalty-based apps drives customer engagement.
Middle East
The Middle East Food Delivery Software Market size was valued at USD 104.78 million in 2018 to USD 224.23 million in 2024 and is anticipated to reach USD 520.85 million by 2032, at a CAGR of 10.1% during the forecast period. The region accounts for 2% of the Global Food Delivery Software MarketMarket. Growth is supported by increasing adoption of online food delivery services in the UAE, Saudi Arabia, and Israel. It benefits from the expansion of international and regional aggregators offering multilingual apps and flexible delivery options. Demand for premium food delivery services among high-income consumers strengthens market performance. Cloud kitchen adoption continues to grow in metropolitan areas. Government initiatives for smart city development support digital and contactless food delivery platforms.
Africa
The Africa Food Delivery Software Market size was valued at USD 52.07 million in 2018 to USD 144.78 million in 2024 and is anticipated to reach USD 305.00 million by 2032, at a CAGR of 8.7% during the forecast period. Africa contributes 1% of the Global Food Delivery Software MarketMarket. The region’s growth is emerging, driven by expanding urban centers and rising smartphone accessibility. South Africa and Egypt lead due to improving internet infrastructure and growing online commerce. It faces logistical challenges in rural distribution but continues to attract investments from new startups. Mobile-based payment systems and low-cost delivery models are gaining traction. Local innovation and collaborations with global platforms are expected to strengthen future growth.
Key Player Analysis:
Competitive Analysis:
The Global Food Delivery Software Market is highly competitive with several global and regional players focusing on innovation, scalability, and customer experience. Key participants include Uber Eats, DoorDash, Grubhub, Deliveroo, Zomato, and Swiggy. These companies invest heavily in AI-driven logistics, automation, and predictive analytics to optimize delivery time and resource utilization. It continues to evolve through strategic partnerships with restaurants and logistics providers to expand service coverage. Players are also prioritizing sustainability by deploying electric vehicles and promoting eco-friendly packaging. Market leaders emphasize seamless app integration, real-time tracking, and personalized recommendations to retain customer loyalty. Continuous upgrades in software performance and user interfaces strengthen brand positioning and competitive advantage across both developed and emerging markets.
Recent Developments:
- In June 2025, DoorDash acquired ad tech platform Symbiosys to expand its offsite advertising capabilities and launched new AI-powered ad tools for restaurants and brands.
- In February 2025, Zomato further strengthened its position in quick commerce by investing an additional ₹1,500 crore in Blinkit, continuing its post-acquisition strategy to deepen integration and market reach.
Report Coverage:
The research report offers an in-depth analysis based on Component, End User, Delivery Model and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Food Delivery Software Market will experience sustained growth driven by increasing digital adoption in the food service industry.
- AI-powered automation and predictive analytics will enhance delivery accuracy and customer engagement.
- Cloud-based deployment will dominate, offering scalability and remote management for restaurants and delivery operators.
- Integration with advanced payment gateways and loyalty platforms will boost transaction efficiency and retention rates.
- Expansion of drone and robotic delivery systems will improve speed and reduce operational costs.
- Rising demand for eco-friendly and electric delivery fleets will promote sustainable business models.
- Data-driven personalization will help platforms offer customized meal suggestions and promotions.
- Collaboration between software providers and restaurants will strengthen end-to-end digital ecosystems.
- Emerging economies in Asia-Pacific, Latin America, and Africa will offer new opportunities for market expansion.
- Continuous innovation in cybersecurity, API connectivity, and AI integration will define the next growth phase of the industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Food Delivery Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Food Delivery Software Market projected to grow between 2024 and 2032?
Which segment held the largest share in the Global Food Delivery Software Market in 2024?
What are the primary factors fueling the growth of the Global Food Delivery Software Market?
Who are the leading companies in the Global Food Delivery Software Market?
Which region commanded the largest share of the Global Food Delivery Software Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Food Delivery Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Food Delivery Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 11,840.09 million → 2032: USD 34,866.44 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Food Delivery Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Food Delivery Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Food Delivery Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Food Delivery Software Market Drivers
- 3.3 Food Delivery Software Market Restraints & Challenges
- 3.4 Food Delivery Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Food Delivery Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Food Delivery Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Food Delivery Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Food Delivery Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Food Delivery Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Food Delivery Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Food Delivery Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Food Delivery Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Food Delivery Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Food Delivery Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Food Delivery Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Food Delivery Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Food Delivery Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Food Delivery Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Food Delivery Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Food Delivery Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Food Delivery Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Food Delivery Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Food Delivery Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
