
Market Overview
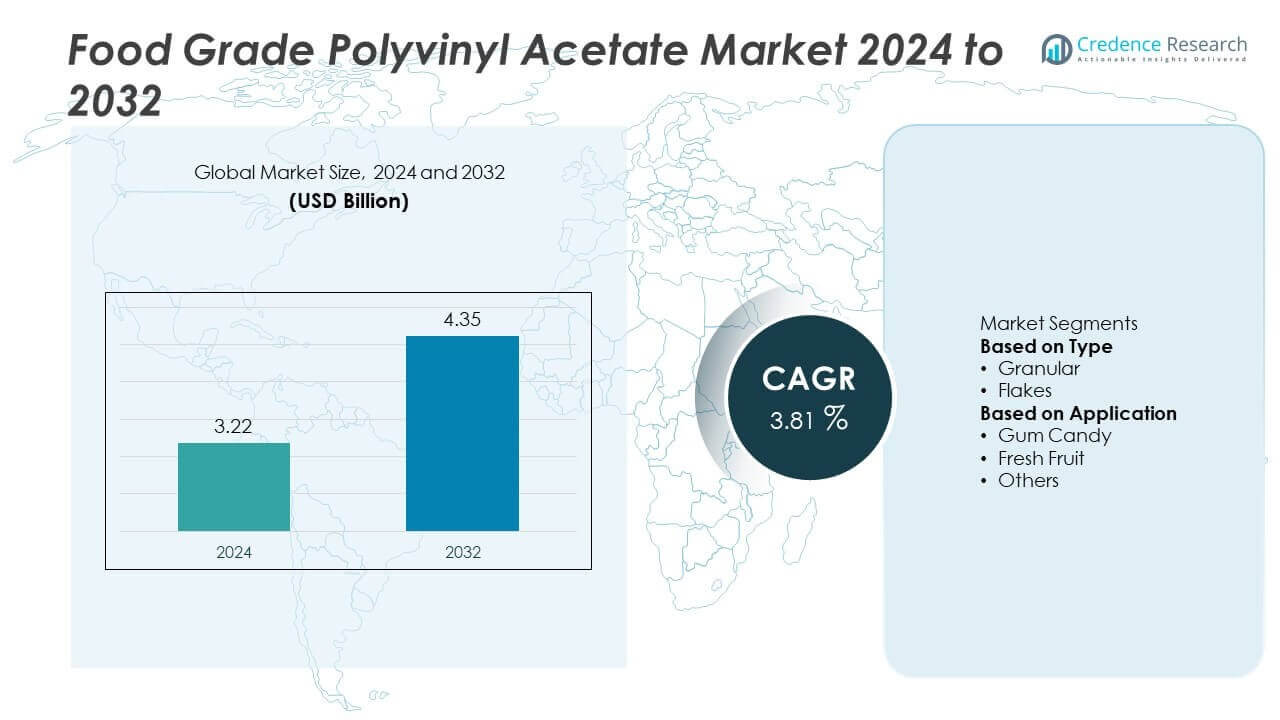
Food Grade Polyvinyl Acetate Market size was valued at USD 3.22 billion in 2024 and is projected to reach USD 4.35 billion by 2032, growing at a CAGR of 3.81% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Grade Polyvinyl Acetate Market Size 2024 | USD 3.22 Billion |
| Food Grade Polyvinyl Acetate Market, CAGR | 3.81% |
| Food Grade Polyvinyl Acetate Market Size 2032 | USD 4.35 Billion |
Key players in the Food Grade Polyvinyl Acetate market include Celanese, Wacker, VINAVIL, Brenntag Specialties, Jiangsu Yinyang Gumbase Materials, Shuanghui Rubber Nantong Co., LTD, Foreverest Resources Ltd., Nacalai, Synthomer PLC, and Eastman Chemical Company. These companies focus on producing high-purity grades, expanding production capacity, and strengthening distribution networks to meet growing demand from confectionery and fruit coating applications. Asia-Pacific leads the market with 38% share, driven by strong chewing gum consumption in China and India and rising adoption of fruit coatings across ASEAN exporters. Europe follows with 25% share, supported by established confectionery production and strict EFSA regulations, while North America accounts for 20% share, led by innovation in sugar-free gum and functional snacks.
Market Insights
- Food Grade Polyvinyl Acetate market was valued at USD 3.22 billion in 2024 and is projected to reach USD 4.35 billion by 2032, growing at a CAGR of 3.81% during the forecast period.
- Rising demand for chewing gum and confectionery drives market growth, with gum candy applications holding over 55% share and granular type leading with more than 60% share due to its superior processing efficiency.
- Clean-label movement and innovation in high-purity, food-safe formulations are major trends, encouraging adoption of low-residue polymers and sustainable coating solutions.
- Competition is moderately consolidated with players like Celanese, Wacker, VINAVIL, and Jiangsu Yinyang Gumbase Materials focusing on R&D, capacity expansion, and strategic distribution partnerships to strengthen market presence.
- Asia-Pacific leads with 38% share, followed by Europe at 25% and North America at 20%, driven by confectionery production, fresh fruit exports, and automation in food processing.
Market Segmentation Analysis:
By Type
The Food Grade Polyvinyl Acetate market by type is led by granular form, accounting for over 60% share. Its free-flowing nature supports consistent dosing and better process efficiency in large-scale food production. Granular form is widely used in chewing gum manufacturing, where uniformity and stability are critical. Flake form caters to niche uses requiring slower dissolution and customized formulations. Growing adoption of automated production lines and demand for consistent quality in confectionery continue to strengthen the dominance of granular polyvinyl acetate in the market.
- For instance, Wacker Chemie AG’s VINNAPAS® B 500/20 VL and B 500/40 VL vinyl acetate-vinyllaurate copolymers (used in gum base) are permitted in chewing-gum base at levels up to about 26% of the gum base weight.
By Application
Gum candy dominates the application segment with more than 55% share, driven by its use as a key base polymer in chewing gum. Polyvinyl acetate enhances chewability, flavor retention, and shelf life, making it essential for major gum brands. Fresh fruit applications are growing rapidly as exporters adopt coatings to preserve appearance and reduce spoilage. The “others” segment, including bakery and snack coatings, benefits from clean-label trends and safer food-grade solutions. Rising demand for functional and innovative gum products continues to support strong growth in this application segment.
- For instance, an HPLC-ELSD study of commercial chewing gum samples found PVAc content up to 13.8 g/kg in some samples.
 Key Growth Drivers
Rising Demand for Chewing Gum and Confectionery
The Food Grade Polyvinyl Acetate market grows with increasing consumption of chewing gum and sugar confectionery worldwide. Manufacturers rely on polyvinyl acetate for its elasticity, flavor retention, and stability, which enhance chewing experience. Demand for sugar-free and functional gum varieties also boosts polymer usage. Emerging markets with rising disposable incomes, such as India and Brazil, further drive production volumes. Confectionery brands invest in advanced formulations to meet changing consumer preferences, reinforcing steady growth in this segment and solidifying its position as a core driver for the market.
- For instance, a patented bubble gum base formula uses a blend of low molecular weight PVAc (≈ 12,000-16,000 mean average molecular weight) and medium molecular weight PVAc (≈ 35,000-55,000) in amounts up to 14% and 35% by weight of the gum base respectively.
Growing Adoption in Fresh Fruit Coatings
The market benefits from the expanding use of polyvinyl acetate as a coating for fresh fruits. The edible film preserves moisture, improves shelf life, and maintains visual appeal during transport. Rising global exports of perishable fruits, particularly from Latin America and Asia, strengthen this demand. Exporters seek reliable coating materials that meet regulatory standards and reduce post-harvest losses. The trend aligns with sustainability goals by minimizing food waste. Increasing consumer demand for fresh, high-quality fruits accelerates adoption, making fresh fruit coatings a major contributor to market expansion.
- For instance, a 2011 study in Revista Chapingo Serie Horticultura on green-stage 'Gabriela' tomatoes found that a polyvinyl acetate (PVA) coating provided some protective effects during ambient storage for up to 14 days, though the effects on luminosity, weight loss, and respiration rate were not statistically significant under the experimental conditions used.
Advancements in Food-Grade Polymer Technology
Technological innovation in food-grade polymer production supports market growth by offering improved purity and performance. Manufacturers develop low-residue, high-quality polyvinyl acetate grades that meet stringent food safety regulations. New formulations enhance solubility, processing efficiency, and compatibility with automated systems. These innovations enable consistent production of chewing gum bases and coatings, reducing variability and improving product quality. Investments in research and development drive continuous improvement, allowing companies to cater to evolving consumer expectations and regulatory requirements. This focus on innovation helps expand market opportunities globally.
Key Trends & Opportunities
Shift Toward Clean-Label and Natural Ingredients
Consumers increasingly prefer products with safe, traceable, and natural ingredients, encouraging producers to use food-grade polyvinyl acetate that meets strict compliance standards. Clean-label confectionery and coatings require high-purity polymers with minimal additives. This trend creates opportunities for manufacturers to develop eco-friendly, bio-based alternatives while maintaining functional properties. Brands promoting transparency and health benefits are likely to see stronger adoption of certified materials. The clean-label movement is particularly strong in Europe and North America, offering a favorable environment for producers to differentiate through safer and sustainable formulations.
- For instance, in the study Determination of Polyvinyl Acetate in Chewing Gum the content of PVAc in commercial chewing gum samples ranged from not detected up to 13.8 g per kilogram of gum.
Expansion in Emerging Markets
Emerging economies present significant opportunities due to rising urbanization, income levels, and demand for packaged food products. Chewing gum consumption is growing in Asia-Pacific and Latin America, creating demand for polyvinyl acetate as a key raw material. Expansion of modern retail and cold-chain logistics further supports market penetration in these regions. Local producers and multinationals invest in capacity expansion to meet demand. These markets also encourage innovation in low-cost formulations tailored to regional preferences, opening new growth avenues for food-grade polyvinyl acetate suppliers.
- For instance, a product listing from a Chinese supplier of food-grade PVA (which is closely related in use to PVAc adhesives/coatings) specifies molecular weights (degree of polymerization) in the range of 13,000 to 23,000 for low-molecular weight PVA.
Key Challenges
Fluctuating Raw Material Prices
The market faces challenges due to volatility in vinyl acetate monomer prices, a key raw material for polyvinyl acetate. Price fluctuations affect production costs and profit margins for manufacturers. Dependency on petrochemical feedstocks exposes the industry to crude oil price variations. Sudden cost increases can disrupt supply contracts and reduce competitiveness, particularly for smaller producers. Companies are focusing on supply chain optimization and exploring alternative sourcing to mitigate risks. Stable pricing strategies are essential to maintain profitability in a price-sensitive food industry environment.
Regulatory Compliance and Food Safety Standards
Strict food safety regulations across regions require producers to maintain high-quality standards, which can increase production costs. Meeting compliance with frameworks like FDA, EFSA, and Codex Alimentarius involves continuous testing and certification. Any contamination or deviation can lead to recalls, damaging brand reputation. Frequent regulatory updates demand constant monitoring and process adjustments. This creates pressure on manufacturers to invest in advanced production technologies and robust quality control systems. Compliance complexity may hinder market entry for small players and limit operational flexibility for established companies.
Regional Analysis
North America
North America holds 20% market share. The United States drives demand through large confectionery production. Chewing gum brands favor granular grades for dosing accuracy. Clean-label pressure supports high-purity, low-residue formulations. Fresh fruit coatings grow with longer domestic supply chains. Retail private labels expand functional gum lines. Regulatory compliance with FDA standards shapes specifications and audits. Automation in mixing and extrusion boosts polymer consistency needs. Canada adds steady demand from snack and bakery coatings. Cross-border sourcing strategies reduce raw material volatility. Sustainability programs encourage waste reduction and tighter process control.
Europe
Europe accounts for 25% market share. Germany, Italy, and the U.K. lead confectionery output. Brands emphasize texture stability and flavor retention in sugar-free gum. EFSA requirements drive strict purity and migration limits. Fresh produce exporters adopt coatings for shelf-life gains. Northern Europe prioritizes traceability and certified inputs. Western Europe modernizes legacy plants with automated dosing. Eastern Europe adds capacity for regional private labels. Energy management initiatives favor efficient processing aids. Circular packaging efforts push cleaner auxiliary materials. Premium formulations support long-lasting chew performance and consistent sensory profiles.
Asia-Pacific
Asia-Pacific commands 38% market share, the largest region. China and India anchor chewing gum and candy growth. Rising incomes and urban retail boost packaged confectionery sales. ASEAN fruit exporters use coatings to protect high-value shipments. Local producers scale automated lines for dosing precision. Japan and South Korea demand high-purity specialty grades. Regional players tailor formulations for tropical climates. E-commerce snacking trends lift gum innovations. Supply proximity to vinyl acetate improves cost agility. Multinationals expand joint ventures and technical centers to meet regulatory and performance needs.
Latin America
Latin America holds 10% market share. Mexico and Brazil lead gum base consumption. Fruit exporters adopt coatings to cut moisture loss in transit. Retail expansion supports impulse confectionery categories. Producers invest in reliable granular grades for throughput gains. Regulatory frameworks align with Codex and major import markets. Currency swings highlight the need for stable sourcing. Contract manufacturers serve multinational brand requirements. Seasonal fruit peaks require flexible coating supply. Training on process control improves batch uniformity and flavor carry. Sustainability programs target food waste reduction across the cold chain.
Middle East & Africa
Middle East & Africa represents 7% market share. GCC countries import gum and confectionery at scale. Local plants focus on heat-stable, clean-label grades. North African fruit exporters use coatings for EU shipments. Modern trade grows premium gum formats in urban centers. Temperature extremes require robust storage and handling practices. Standards harmonization supports cross-border sales. Regional distributors favor granular form for fewer line stoppages. Investments target quality labs and migration testing. Education on shelf-life benefits expands coating adoption. Logistics upgrades improve consistency from plant to retail display.
Market Segmentations:
By Type
- Granular
- Flakes
By Application
- Gum Candy
- Fresh Fruit
- Others
By Geography
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Food Grade Polyvinyl Acetate market features a moderately consolidated competitive landscape with global and regional players focusing on product quality, compliance, and innovation. Companies such as Celanese, Wacker, VINAVIL, and Brenntag Specialties lead with well-established supply chains and advanced manufacturing capabilities. Asian players like Jiangsu Yinyang Gumbase Materials and Shuanghui Rubber Nantong Co., LTD cater to the growing demand for chewing gum bases in high-volume markets. Firms invest in R&D to develop high-purity, food-safe grades with improved solubility and consistency for automated production lines. Strategic partnerships and distribution agreements help expand market reach, particularly in emerging regions. Sustainability and regulatory compliance remain key differentiators, driving adoption of cleaner formulations and environmentally responsible production processes. Competitors also focus on capacity expansion and localization to ensure cost efficiency and stable supply, positioning themselves to meet rising demand from confectionery, fruit coating, and specialty food applications worldwide.
Key Player Analysis
- Celanese
- Foreverest Resources Ltd.
- Jiangsu Yinyang Gumbase Materials
- Shuanghui Rubber Nantong CO., LTD
- Wacker
- VINAVIL
- Nacalai
- Brenntag Specialties
- Synthomer PLC
- Eastman Chemical Company
Recent Developments
- In May 2025, Vinavil announced a price increase on all its vinylic polymers.
- In May 2025, Wacker declared a price rise for dispersions and dispersible polymer powders, which includes materials used in vinyl acetate based coatings and adhesives.
- In March 2025, Celanese announced an increase in prices for Vinyl Acetate Monomer (VAM) and derivatives in the Western Hemisphere.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for chewing gum bases will continue to drive consistent consumption of food grade polyvinyl acetate.
- Growth in sugar-free and functional gum products will boost adoption of high-purity grades.
- Automation in food processing will increase the need for granular forms with better flow properties.
- Rising fresh fruit exports will expand the use of edible coatings to reduce spoilage.
- Innovation in bio-based and sustainable polymers will gain traction to meet clean-label demands.
- Capacity expansion by leading producers will ensure stable supply for global confectionery brands.
- Regulatory compliance will remain a focus, pushing investment in quality control systems.
- Emerging markets in Asia and Latin America will see faster consumption growth from rising incomes.
- Strategic collaborations between suppliers and food manufacturers will enhance product innovation.
- Technological advancements in polymer processing will improve consistency and performance in end applications.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Chewing Gum and Confectionery Production
Polyvinyl acetate is a key ingredient in gum bases, valued for its elasticity and flavor retention. The increasing global consumption of chewing gum and sugar confectionery, especially in Asia-Pacific and emerging markets, is driving demand for food grade polyvinyl acetate.
Expansion of Fresh Fruit Exports and Coatings
Exporters are increasingly using polyvinyl acetate-based edible coatings to extend shelf life and preserve the appearance of fresh fruits during transport. This trend is particularly strong in Latin America and Asia, where fruit exports are rising and food waste reduction is a priority.
Advancements in Food-Grade Polymer Technology
Manufacturers are investing in R&D to develop high-purity, low-residue polyvinyl acetate grades that meet stringent food safety regulations. These innovations improve processing efficiency and product consistency, supporting adoption in automated food production lines.
Shift Toward Clean-Label and Sustainable Ingredients
Consumer demand for clean-label and traceable food products is encouraging the use of food-safe, high-purity polyvinyl acetate with minimal additives. This trend is especially prominent in Europe and North America, where regulatory and market pressures favor eco-friendly and certified formulations.
Rising Automation in Food Processing
The adoption of automated production lines in confectionery and fruit processing industries increases the need for granular forms of polyvinyl acetate, which offer superior flow properties and dosing accuracy, supporting large-scale, consistent manufacturing.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Food Grade Polyvinyl Acetate market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Grade Polyvinyl Acetate market projected to grow between 2025 and 2032?
Which Food Grade Polyvinyl Acetate market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Grade Polyvinyl Acetate market?
Who are the leading companies in the Food Grade Polyvinyl Acetate market?
Which region commanded the largest share of the Food Grade Polyvinyl Acetate market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Granular
- 1.2.2 Flakes
- 1.3 By Application
- 1.3.1 Gum Candy
- 1.3.2 Fresh Fruit
- 1.3.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.22 billion → 2032: USD 4.35 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Grade Polyvinyl Acetate Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Grade Polyvinyl Acetate Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Grade Polyvinyl Acetate Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Grade Polyvinyl Acetate Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Grade Polyvinyl Acetate Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Grade Polyvinyl Acetate Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Grade Polyvinyl Acetate Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Grade Polyvinyl Acetate Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.22 billion → 2032: USD 4.35 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Grade Polyvinyl Acetate Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Granular
- 12.3.7.2 Flakes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Gum Candy
- 12.4.7.2 Fresh Fruit
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Grade Polyvinyl Acetate End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Food Grade Polyvinyl Acetate Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Food Grade Polyvinyl Acetate Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Food Grade Polyvinyl Acetate Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Celanese
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Wacker
- 18.4 VINAVIL
- 18.5 Brenntag Specialties
- 18.6 Jiangsu Yinyang Gumbase Materials
- 18.7 Shuanghui Rubber Nantong Co., LTD
- 18.8 Foreverest Resources Ltd.
- 18.9 Nacalai
- 18.10 Synthomer PLC
- 18.11 Eastman Chemical Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

