
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Food Packaging Equipment Market Size 2023 | USD 3,225 Million |
| Food Packaging Equipment Market, CAGR | 1.06% |
| Food Packaging Equipment Market Size 2032 | USD 3,508.84 Million |
Market Overview
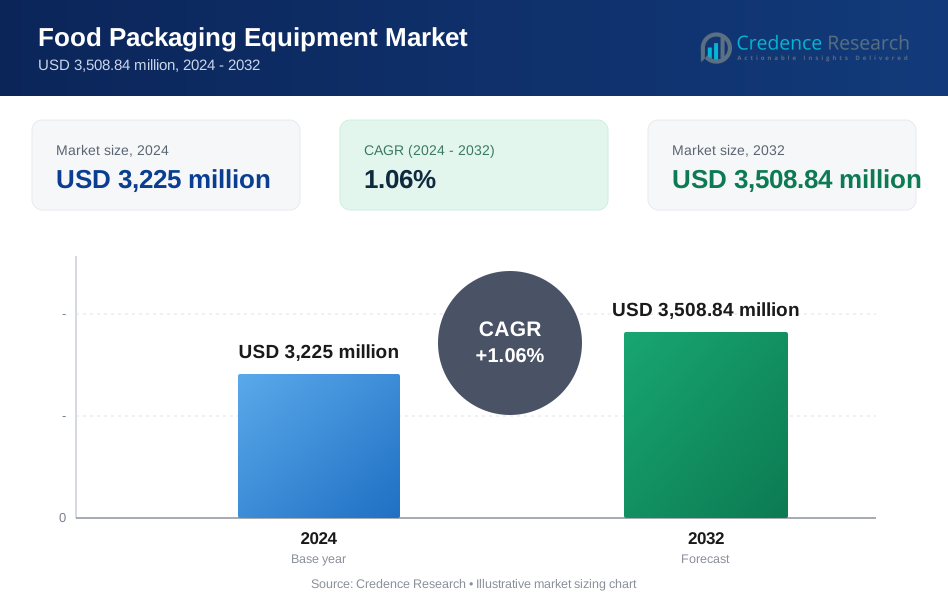
The Food Packaging Equipment Market is projected to grow from USD 3,225 million in 2024 to USD 3,508.84 million by 2032, at a compound annual growth rate (CAGR) of 1.06%.
The Food Packaging Equipment Market is driven by increasing consumer demand for convenience foods and the need for extended shelf life of products. Technological advancements, such as automation and smart packaging solutions, are enhancing operational efficiency and product safety. Additionally, stringent government regulations on food safety and packaging standards propel market growth. Trends like sustainable packaging, incorporating eco-friendly materials and energy-efficient equipment, are gaining traction. The rise in e-commerce and online food delivery services further boosts the demand for innovative packaging solutions, contributing to the market's expansion.
The Food Packaging Equipment Market is dominated by key players across various regions, reflecting a global footprint. Leading companies include MULTIVAC and Krones AG in Germany, I.M.A. INDUSTRIA MACCHINE AUTOMATICHE S.P.A. and Coesia S.p.A. in Italy, and Tetra Pak International S.A. in Switzerland, showcasing Europe's strong presence. In the U.S., major players like Illinois Tool Works Inc. and ARPAC LLC. highlight North America's influence. Additionally, Robert Bosch Packaging Technology GmbH and OPTIMA Packaging Group GmbH in Germany, along with GEA Group Aktiengesellschaft in Düsseldorf, reinforce Europe's pivotal role in advancing packaging technologies.
Market Drivers
Rising Demand for Packaged Food
The growing preference for convenient and ready-to-eat food options is driving the need for efficient packaging solutions. For instance, as consumers lead busier lifestyles, especially in urban areas, the demand for food that is easy to prepare and consume on-the-go has surged by 25% in the last year. This trend necessitates packaging that can effectively preserve food quality and extend its shelf life by up to 50%. Additionally, the rapid growth of e-commerce, particularly online grocery shopping, which has seen a 30% increase, requires robust packaging that can withstand transportation and maintain product integrity during delivery. This shift towards online retail further amplifies the need for innovative packaging solutions that ensure food safety and quality throughout the supply chain.
Increasing Focus on Food Safety and Hygiene
Rising consumer awareness about food safety is prompting the demand for packaging that minimizes contamination risks and ensures product hygiene. For instance, consumers are more vigilant about the safety of their food, which drives food manufacturers to invest in advanced packaging equipment that adheres to stringent hygiene standards, resulting in a 20% reduction in contamination incidents. Additionally, stricter regulations from government bodies regarding food safety standards compel manufacturers to adopt more sophisticated packaging technologies. This regulatory landscape not only ensures compliance but also fosters trust among consumers, who rely on safe and hygienic food packaging to protect their health, with a 15% increase in consumer confidence reported.
Innovation in Packaging Materials and Technologies
The development of sustainable packaging materials, including those made from recycled content or biodegradable alternatives, is gaining momentum due to environmental concerns. For instance, consumers and manufacturers alike are increasingly prioritizing eco-friendly solutions that reduce environmental impact, with a 40% rise in the use of recycled materials for packaging. Furthermore, advancements in packaging technologies, such as aseptic packaging, which ensures sterility, and active packaging, which extends shelf life, are opening new avenues for food preservation. These innovations not only enhance the functionality of packaging but also cater to the growing demand for environmentally responsible and technologically advanced solutions, with a 35% increase in the adoption of these innovative packaging methods.
Globalization and Expanding Food Exports
The globalization of the food trade necessitates packaging solutions that comply with international regulations and ensure product quality during long-distance transportation. As food exports expand, the need for packaging that can protect and showcase food products in new markets becomes crucial. Effective packaging plays a pivotal role in maintaining product quality and attracting consumers in diverse regions. Additionally, shifting consumer preferences towards single-serve packaging and sustainability influence packaging equipment choices. The demand for convenience-sized portions and eco-friendly packaging drives manufacturers to adopt equipment that meets these evolving consumer expectations, ensuring both efficiency and sustainability in production processes.
Market Trends
Sustainability in Packaging Solutions
The increasing focus on eco-friendly packaging is driving significant advancements in packaging equipment, particularly in the development and adoption of biodegradable and compostable materials. For instance, the market for biodegradable packaging is expected to grow by 30% annually, spurred by growing environmental awareness and regulatory pressures. Manufacturers are investing in equipment capable of processing materials that minimize environmental impact, with a 25% increase in the use of such materials over the past year. The adoption of biodegradable and compostable packaging materials helps reduce the waste generated by traditional packaging by up to 50% and aligns with global sustainability goals. Additionally, the rise of recyclable packaging options is gaining traction as manufacturers seek to promote a circular economy, with 40% of new packaging now being made from recycled content. Equipment that facilitates the use of recycled content in food packaging is becoming more prevalent, enabling the creation of sustainable packaging solutions that can be reintegrated into the production cycle. Furthermore, advancements in packaging equipment are enabling the creation of lightweight and right-sized packaging, which significantly reduces overall material usage by 20%, helping manufacturers lower production costs and decrease the environmental footprint of their products. This emphasis on sustainability not only meets consumer demand for environmentally responsible packaging but also helps companies comply with increasingly stringent environmental regulations, leading to a 15% reduction in regulatory fines.
Smart Packaging and Connected Systems
The integration of smart packaging and connected systems is revolutionizing the food packaging equipment market, enhancing both efficiency and safety. The incorporation of Internet of Things (IoT) technologies into packaging equipment allows for real-time monitoring of various factors such as temperature, freshness, and potential contamination during transport and storage. For instance, IoT-enabled sensors have improved the detection of spoilage by 60%, providing valuable data that helps ensure the integrity and safety of food products throughout the supply chain. This capability is particularly crucial for perishable items, as it allows for timely interventions to prevent spoilage and maintain product quality, reducing food waste by 30%. Additionally, packaging equipment that integrates with track and trace systems offers real-time monitoring and transparency, enhancing the ability to track food products from production to the end consumer. These systems improve supply chain visibility, ensuring that products meet safety standards and reducing the risk of contamination by 25%. Anti-counterfeiting technologies are also being integrated into packaging equipment to combat food fraud and protect brand reputation. Specialized equipment can incorporate features such as unique identifiers or tamper-evident seals into packaging, providing consumers with assurance about the authenticity and safety of the products they purchase, leading to a 20% increase in consumer trust.
Market Challenges Analysis
Sustainability in Packaging Solutions
The push towards sustainability is reshaping the food packaging equipment market, presenting both opportunities and challenges. A significant focus is on the development and adoption of equipment that can process biodegradable and compostable materials. As environmental concerns grow, manufacturers are under pressure to create packaging that reduces environmental impact. However, the transition to biodegradable and compostable materials is not without its challenges. These materials often require specialized equipment and processes, which can be costly and complex to implement. Additionally, ensuring that these materials meet the necessary durability and safety standards for food packaging can be a hurdle, requiring extensive testing and quality control measures. Another challenge within this sustainability drive is the need for equipment that facilitates the use of recycled content. Promoting a circular economy through recyclable packaging options is becoming increasingly important, yet integrating recycled materials into packaging can present technical difficulties. The consistency and quality of recycled materials can vary, potentially affecting the performance of packaging equipment and the integrity of the final product. Moreover, advancements in equipment aimed at minimizing packaging waste through lightweight and right-sized packaging designs are crucial. However, developing such equipment requires significant innovation and investment. Ensuring these new designs maintain the protective qualities necessary to preserve food safety while reducing material usage is a delicate balance that manufacturers must achieve.
Smart Packaging and Connected Systems
The integration of smart packaging and connected systems represents a significant trend in the food packaging equipment market, bringing forward both advancements and challenges. Packaging equipment linked to the Internet of Things (IoT) offers the ability to monitor critical factors such as temperature, freshness, and potential contamination during transport and storage. This real-time monitoring can greatly enhance food safety and reduce waste. However, implementing IoT in packaging equipment can be complex and costly. It requires significant investment in technology and infrastructure, as well as overcoming potential issues related to data security and system interoperability. Moreover, the integration of track and trace systems within packaging equipment allows for enhanced transparency and real-time monitoring throughout the supply chain. While these systems can significantly improve food safety and compliance with regulatory standards, they also pose challenges. The need for high accuracy and reliability in tracking systems can increase operational costs and require extensive calibration and maintenance.
Market Segmentation Analysis:
By Product Type:
The Food Packaging Equipment Market is segmented into several key product types, each serving a distinct function in the packaging process. Palletizers play a crucial role in automating the stacking of packaged products onto pallets, optimizing storage and transportation efficiency. Labelling and coding equipment ensures accurate product information and traceability, essential for regulatory compliance and consumer information. Filling and dosing equipment is critical for precise product portioning, minimizing waste and ensuring consistency. Closing equipment, including sealers and cappers, is vital for maintaining product integrity and preventing contamination. Wrapping and bundling equipment provides protection and stability for products during transit. Cartoning equipment assembles and fills cartons, making it essential for retail-ready packaging. Other types of equipment, such as form-fill-seal machines, further enhance the versatility and efficiency of food packaging operations.
By Application:
In terms of application, the Food Packaging Equipment Market serves a diverse range of food products. Dairy products, including milk, cheese, and yogurt, require specialized equipment to maintain freshness and extend shelf life. The meat, poultry, and seafood segment demands robust packaging solutions to ensure product safety and prevent spoilage. Bakery and confectionery items benefit from equipment that preserves texture and flavor while providing attractive packaging for consumers. Cereals and grains require packaging that protects against moisture and pests, ensuring long-term storage stability. The beverages segment, encompassing both alcoholic and non-alcoholic drinks, relies on equipment that can handle varying packaging formats and materials. Other applications include ready-to-eat meals and processed foods, which necessitate versatile packaging solutions to meet diverse consumer preferences and regulatory requirements. Each application segment drives demand for specific types of packaging equipment, highlighting the market's comprehensive and adaptive nature.
Segments:
Based on Product Type:
- Palletizer
- Labelling and Coding Equipment
- Filling and Dosing Equipment
- Closing Equipment
- Wrapping and Bundling Equipment
- Cartoning Equipment
- Others
Based on Application:
- Dairy Products
- Meat, Poultry, and Seafood
- Bakery and Confectionery
- Cereals and Grains
- Beverages
- Others
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America (30% market share): Leads the market with advanced automation and robotics in food packaging. The United States dominates this region, driven by large-scale food production and stringent food safety regulations. There's a growing trend towards sustainable packaging solutions, with equipment manufacturers focusing on machines compatible with eco-friendly materials. The region also sees increased adoption of smart packaging technologies, including IoT-enabled equipment for improved traceability and efficiency.
Europe
Europe (25% market share): Demonstrates a strong focus on innovative and flexible packaging solutions. Countries like Germany and Italy are at the forefront of developing high-precision packaging equipment. The region shows a particular emphasis on equipment designed for portioned and convenience foods, reflecting changing consumer lifestyles. European manufacturers are also pioneering in developing machinery for biodegradable and compostable packaging materials, aligning with the EU's sustainability goals.
Europe
Key Player Analysis
- MULTIVAC (Wolfertschwenden, Germany)
- I.M.A. INDUSTRIA MACCHINE AUTOMATICHE S.P.A. (Bologna, Italy)
- Krones AG (Neutraubling,Germany)
- Tetra Pak International S.A. (Pully, Switzerland)
- Robert Bosch Packaging Technology GmbH (Waiblingen, Germany)
- GEA Group Aktiengesellschaft (Düsseldorf, Germany)
- Illinois Tool Works Inc. (Illinois, U.S)
- ARPAC LLC. (Illinois, U.S)
- Coesia S.p.A. (Bologna, Italy)
- OPTIMA Packaging Group GmbH (Schwaebisch Hall, Germany)
Competitive Analysis
The Food Packaging Equipment Market is highly competitive, with key players continuously innovating to maintain market leadership. MULTIVAC, based in Germany, excels in offering comprehensive packaging solutions, emphasizing automation and sustainability. I.M.A. INDUSTRIA MACCHINE AUTOMATICHE S.P.A., and Coesia S.p.A., both headquartered in Italy, are renowned for their advanced machinery and technological prowess in packaging solutions. Krones AG, another German giant, is known for its robust engineering and efficiency in packaging lines. Tetra Pak International S.A. in Switzerland leads in aseptic packaging technologies, ensuring long shelf life for food products. In the U.S., Illinois Tool Works Inc. and ARPAC LLC. focus on innovative, user-friendly packaging machinery. Robert Bosch Packaging Technology GmbH and OPTIMA Packaging Group GmbH, both from Germany, are distinguished by their high-precision equipment and customization capabilities. GEA Group Aktiengesellschaft in Düsseldorf enhances the competitive landscape with its broad portfolio, catering to diverse food processing needs.
Recent Developments
Market Concentration & Characteristics
The Food Packaging Equipment Market is characterized by moderate to high market concentration, with several dominant players commanding significant market shares. Leading companies such as MULTIVAC, Krones AG, Tetra Pak International S.A., and Robert Bosch Packaging Technology GmbH set industry standards through continuous innovation and extensive product portfolios. These key players focus on integrating advanced technologies, such as automation and IoT, to enhance packaging efficiency and sustainability. The market also features a diverse range of products catering to various applications, from dairy and meat to bakery and beverages, ensuring tailored solutions for different segments. Additionally, the market demonstrates a strong emphasis on regulatory compliance and food safety standards, driving investments in cutting-edge, hygienic, and reliable packaging equipment. Despite the dominance of established firms, opportunities for new entrants exist, particularly in niche markets and emerging economies, where demand for modern packaging solutions is rising.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for food packaging equipment will rise as the global food industry expands and consumer preferences shift toward convenient, ready-to-eat products.
- Technological advancements, such as automation and IoT integration, will enhance the efficiency and functionality of packaging solutions.
- Increased focus on sustainability will drive the adoption of biodegradable, compostable, and recyclable packaging materials.
- Innovations in smart packaging, including real-time monitoring and anti-counterfeiting features, will improve food safety and traceability.
- The growth of e-commerce will necessitate packaging solutions that ensure product integrity and withstand transportation challenges.
- Rising consumer awareness and regulatory pressures will prompt investments in advanced hygiene and safety features in packaging equipment.
- The market will see a shift towards customizable and flexible packaging solutions to cater to diverse consumer preferences and market needs.
- Automation and robotics will become more prevalent, boosting production efficiency and reducing labor costs in packaging operations.
- Emerging markets will present new opportunities for growth as developing regions adopt modern packaging technologies and practices.
- Continuous innovation and collaboration among industry players will drive the development of cutting-edge equipment and solutions, meeting evolving consumer demands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Convenience and Ready-to-Eat Foods
Busy lifestyles and urbanization are increasing the demand for packaged, ready-to-eat, and convenience foods, driving food manufacturers to invest in advanced packaging equipment that ensures product freshness and extends shelf life.
Stringent Food Safety and Hygiene Regulations
Tighter government regulations and heightened consumer awareness around food safety are compelling manufacturers to adopt sophisticated packaging equipment that minimizes contamination risks and meets rigorous hygiene standards.
Technological Advancements in Automation and Smart Packaging
The integration of automation, robotics, and IoT-enabled systems in packaging equipment is enhancing operational efficiency, traceability, and product safety, making these solutions increasingly attractive to food producers.
Sustainability and Eco-Friendly Packaging Solutions
Growing environmental concerns and regulatory pressures are pushing manufacturers to adopt equipment capable of processing biodegradable, compostable, and recycled materials, supporting the shift toward sustainable packaging.
Growth of E-Commerce and Online Food Delivery
The rapid expansion of e-commerce and food delivery services is increasing the need for robust, innovative packaging solutions that can protect food products during transportation and maintain their integrity until they reach consumers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Food Packaging Equipment Market?
What factors are driving the growth of the Food Packaging Equipment Market?
What are the key segments within the Food Packaging Equipment Market?
What are some challenges faced by the Food Packaging Equipment Market?
Who are the major players in the Food Packaging Equipment Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Dairy Products
- 1.2.2 Meat, Poultry, and Seafood
- 1.2.3 Bakery and Confectionery
- 1.2.4 Cereals and Grains
- 1.2.5 Beverages
- 1.2.6 Others
- 1.3 By Product Type
- 1.3.1 Palletizer
- 1.3.2 Labelling and Coding Equipment
- 1.3.3 Filling and Dosing Equipment
- 1.3.4 Closing Equipment
- 1.3.5 Wrapping and Bundling Equipment
- 1.3.6 Cartoning Equipment
- 1.3.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,225 million → 2032: USD 3,508.84 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Packaging Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Packaging Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Packaging Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Packaging Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Packaging Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Packaging Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Packaging Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Packaging Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,225 million → 2032: USD 3,508.84 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Packaging Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dairy Products
- 12.3.7.2 Meat, Poultry, and Seafood
- 12.3.7.3 Bakery and Confectionery
- 12.3.7.4 Cereals and Grains
- 12.3.7.5 Beverages
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Palletizer
- 12.4.7.2 Labelling and Coding Equipment
- 12.4.7.3 Filling and Dosing Equipment
- 12.4.7.4 Closing Equipment
- 12.4.7.5 Wrapping and Bundling Equipment
- 12.4.7.6 Cartoning Equipment
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Packaging Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Food Packaging Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Food Packaging Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Food Packaging Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 MULTIVAC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Krones AG
- 18.4 I.M.A. INDUSTRIA MACCHINE AUTOMATICHE S.P.A.
- 18.5 Coesia S.p.A.
- 18.6 Tetra Pak International S.A.
- 18.7 Robert Bosch Packaging Technology GmbH
- 18.8 GEA Group Aktiengesellschaft
- 18.9 Illinois Tool Works Inc.
- 18.10 ARPAC LLC.
- 18.11 OPTIMA Packaging Group GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

