
Market Overview:
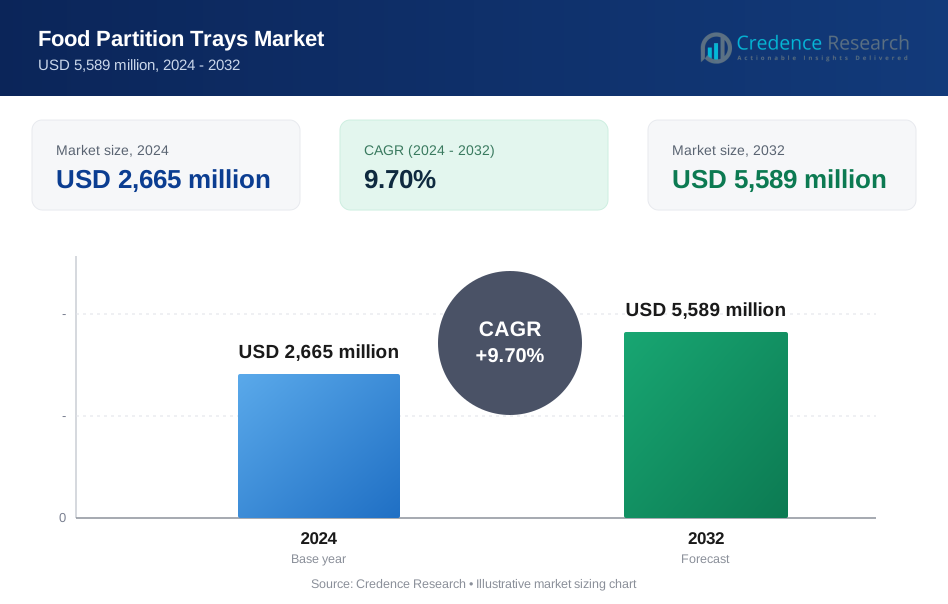
The Food partition trays market size was valued at USD 2665 million in 2024 and is anticipated to reach USD 5589 million by 2032, at a CAGR of 9.7 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Partition Trays Market Size 2024 | USD 2665 million |
| Food Partition Trays Market, CAGR | 9.7% |
| Food Partition Trays Market Size 2032 | USD 5589 million |
Key drivers fueling the growth of the food partition trays market include the rising demand for convenient and hygienic food packaging solutions, especially in institutional and quick-service restaurant (QSR) settings. Growing consumer preference for on-the-go meals and the expansion of the food delivery ecosystem have increased the adoption of trays that preserve food integrity and prevent cross-contamination between food portions. In addition, heightened awareness around health and nutrition is boosting the popularity of trays that support controlled portioning. The rise in eco-conscious packaging trends has further encouraged the development of compostable and recyclable partition trays, with governments and food service operators mandating sustainable alternatives to single-use plastics.
Regionally, North America dominates the global food partition trays market, supported by robust demand from educational institutions, airline catering services, and QSR chains. The United States accounts for the largest market share due to its well-established foodservice infrastructure and strict food safety standards, with key players such as Amcor, Anchor Packaging, and Be Green Packaging driving product innovation and sustainable packaging adoption. Europe follows closely, driven by environmental regulations and growing usage in institutional foodservice operations. Meanwhile, Asia Pacific is expected to witness the fastest growth through 2032, propelled by rapid urbanization, expanding food delivery networks, and increasing adoption of eco-friendly packaging in emerging economies such as India, China, and Southeast Asian countries.
Market Insights:
- The food partition trays market was valued at USD 2,665 million in 2024 and is expected to reach USD 5,589 million by 2032.
- Rising demand for hygienic, portion-controlled packaging drives adoption in schools, hospitals, and correctional facilities.
- The growth of food delivery and ready-to-eat meals fuels demand for multi-compartment trays that preserve food integrity.
- Consumer preference for sustainable packaging supports a shift toward bagasse, molded fiber, and compostable materials.
- North America leads with 36% market share, driven by institutional demand and strong food safety regulations.
- High costs of sustainable materials and limited composting infrastructure pose adoption challenges in cost-sensitive markets.
- Asia Pacific shows fastest growth due to urbanization, expanding foodservice, and eco-conscious packaging initiatives.
Market Drivers:
Rising Demand for Portion Control and Meal Segmentation in Institutional and Healthcare Settings:
The food partition trays market benefits from growing demand in schools, hospitals, and correctional facilities where standardized meal portions are essential. Institutions prioritize portion control for nutritional consistency, cost efficiency, and food safety compliance. Compartmentalized trays support structured meal planning and reduce cross-contact between food groups, improving hygiene and presentation. Governments and non-profits supplying meals under nutrition programs often require partition trays to ensure dietary guidelines are met. It supports operational efficiency in mass food distribution environments. The food partition trays market continues to gain traction in institutional sectors due to these requirements.
- For instance, ProAmpac’s ProActive Recyclable Fresh Tray FT-1000 is a lightweight, curbside-recyclable tray composed of 90% air, ensuring impact resistance and water and grease repellence for high-volume institutional use while maintaining sustainability targets.
Expansion of Food Delivery Services and Ready-to-Eat Meal Consumption:
Consumer lifestyles are shifting toward convenience-focused eating habits, increasing the consumption of ready-to-eat (RTE) meals and takeout foods. The food partition trays market supports this trend by offering packaging that preserves food quality and keeps items separated during transit. It helps restaurants, caterers, and delivery platforms maintain presentation and reduce spillage. Trays with sealed compartments enhance the consumer experience and meet rising expectations for product integrity. Growth in food delivery services across urban and suburban markets fuels consistent demand for multi-compartment trays. Their functionality aligns with evolving consumption patterns.
- For instance, Amcor and Cofigeo launched a bespoke three-compartment tray for single-serve microwaveable meals that delivers an ambient shelf life of over 12 months, with pre-launch tests showing up to 80 Percent of consumers planning to eat directly from the tray-demonstrating high acceptance and satisfaction with this packaging innovation.
Rising Consumer Preference for Sustainable and Eco-Friendly Packaging Alternatives:
Environmental awareness and regulatory pressures are pushing the food industry toward sustainable packaging. The food partition trays market is responding with materials such as molded fiber, bagasse, recycled paperboard, and biodegradable plastics. It addresses consumer demand for eco-conscious alternatives to polystyrene and single-use plastics. Businesses in the foodservice sector are adopting compostable trays to meet environmental standards and enhance brand perception. The shift toward circular economy practices supports continued investment in sustainable tray manufacturing. Market players are prioritizing material innovation to meet compliance and consumer preference.
Food Safety Regulations and Hygiene Standards Across the Supply Chain:
Strict food safety regulations across countries support the adoption of partitioned trays in both commercial and institutional settings. The food partition trays market plays a key role in ensuring hygienic food handling and distribution. It enables separation of hot and cold items, allergens, and proteins, which helps meet compliance requirements in sensitive environments. Foodservice operators use trays to minimize cross-contamination risks and improve operational hygiene. Regulatory agencies across regions continue to mandate improved food packaging practices. This reinforces the relevance of compartmentalized tray solutions in the supply chain.
Market Trends:
Adoption of Biodegradable and Compostable Materials to Meet Sustainability Goals:
Manufacturers are shifting toward biodegradable and compostable materials to align with sustainability goals and regulatory mandates. The food partition trays market is witnessing strong demand for products made from molded fiber, bagasse, palm leaves, and recycled paperboard. It reflects consumer preference for packaging with a lower environmental footprint. Foodservice providers and institutions are phasing out traditional polystyrene and plastic trays in favor of greener alternatives. Global efforts to reduce plastic waste are accelerating this transition. Businesses are investing in R&D to improve the durability and cost-efficiency of eco-friendly trays without compromising performance.
- For instance, Nature Fresh Farms introduced a fully compostable molded fiber tray for mini cucumbers, distributing 6 million trays since June 2018, and this initiative prevented 67,200 pounds of Styrofoam trays-equivalent to 12 truck loads-from entering landfills, with each tray designed to decompose within 90 days and made from 100% post-industrial paper waste.
Integration of Customization, Branding, and Functional Design in Tray Manufacturing:
Custom design and branding are gaining importance as food businesses seek to enhance customer engagement through packaging. The food partition trays market supports this trend by offering trays with tailored compartments, embossed logos, and color-coded segments for meal differentiation. It enables foodservice operators to align packaging with brand identity while improving portion visibility and meal aesthetics. Demand for microwave-safe, ovenable, and leak-resistant trays is growing across ready-to-eat and catering applications. Functional innovations such as stackable trays and resealable lids are helping companies streamline logistics and reduce waste. Tray manufacturers are focusing on value-added features to meet the evolving needs of modern foodservice environments.
- For example, KM Packaging’s K-Peel 4G lidding film enables clean peels at temperatures as low as 110°C with a dwell time of just 0.3 seconds, applicable to both APET and rPET trays and available in thicknesses of 21 or 25 microns for material efficiency.
Market Challenges Analysis:
High Cost of Sustainable Materials and Limited Infrastructure for Recycling:
The growing shift toward biodegradable and compostable trays presents cost challenges for manufacturers and end users. The food partition trays market faces pricing pressure due to higher raw material costs associated with eco-friendly substrates like bagasse, PLA, and molded fiber. It becomes difficult for budget-sensitive institutions and foodservice operators to absorb these costs without affecting profitability. Limited availability of composting and recycling infrastructure in many regions further restricts the adoption of sustainable trays. Without adequate waste processing systems, the environmental benefits of these products remain underutilized. Businesses must navigate this cost-sustainability trade-off while ensuring compliance with regulations.
Operational and Supply Chain Constraints in Large-Scale Institutional Settings:
Standardization and logistics remain key challenges for the food partition trays market, especially in high-volume institutional operations. It is difficult to maintain consistent quality and supply when sourcing trays from multiple vendors or across regions. Compatibility with existing equipment, storage limitations, and varying tray dimensions can disrupt service efficiency in hospitals, schools, and airlines. Supply chain disruptions, including delays in material procurement and fluctuating shipping costs, add further complexity. These operational hurdles impact tray availability, increase turnaround times, and reduce system flexibility. Stakeholders must address these barriers to ensure seamless integration of partition trays into foodservice workflows.
Market Opportunities:
Expansion of Eco-Friendly Packaging in Emerging Markets and Institutional Catering:
Emerging economies present strong growth potential for the food partition trays market, driven by rising urbanization and investment in healthcare, education, and public meal programs. It supports large-scale adoption in government-run nutrition schemes and institutional foodservice operations. Increasing awareness of food hygiene and sustainability is prompting demand for safe, eco-friendly meal packaging. Local manufacturers are exploring cost-effective biodegradable materials to meet regulatory and environmental goals. International suppliers are forming partnerships with regional distributors to expand market access. These developments create favorable conditions for product diversification and scale.
Rising Demand from Airline Catering, QSRs, and Meal Kit Providers:
Airline catering services, quick-service restaurants (QSRs), and meal kit companies are seeking packaging that ensures portion separation, food integrity, and user convenience. The food partition trays market aligns well with these needs, offering design flexibility and functional benefits for both hot and cold meals. It creates new revenue opportunities through value-added solutions such as microwavable compartments, tamper-evident features, and branded designs. Growth in premium and health-focused meal segments is also driving interest in innovative packaging formats. Tray manufacturers that offer customized, sustainable, and performance-driven products are well-positioned to serve this evolving demand.
Market Segmentation Analysis:
By Material Type:
The food partition trays market includes plastic, paperboard, bagasse, molded fiber, and aluminum. Plastic trays, particularly polypropylene and PET, dominate due to durability and heat resistance. It remains popular in commercial foodservice and institutional settings. Molded fiber and bagasse segments are gaining momentum with growing demand for eco-friendly options. These materials suit composting and meet evolving regulatory standards. Paperboard trays serve low-moisture food applications and appeal to cost-sensitive users. Aluminum trays see niche use in airline and frozen meal services where heat conduction is essential.
- For instance,Vollrath’s Traex® school compartment trays are engineered for schools and cafeterias, with heat resistance up to 180°F and sectioned compartments for portion control.
By Distribution Channel:
The market operates through direct sales, wholesalers/distributors, retail, and online channels. Direct sales to institutional buyers such as schools, hospitals, and catering companies account for a major share. It enables customized solutions and long-term contracts. Distributors play a key role in reaching small- to medium-sized businesses. Online platforms are expanding, serving food delivery startups and niche eco-packaging brands. Retail remains relevant for consumer-use partition trays, especially in bulk food storage and home meal prep.
- For instance, Herbalife operates one of the largest direct sales networks, with over 2.7 million independent distributors globally, supplying nutrition products directly to organizations and end-users.
By Capacity:
Food partition trays are segmented by compartment count and volume, typically ranging from 2 to 5 sections with varying depth. The 3-compartment format holds a dominant share due to its versatility in serving balanced meals. It supports portion control and separates proteins, grains, and vegetables efficiently. Larger-capacity trays suit institutional catering and airline meals. Smaller trays target snack kits, school lunches, and kids' meals across fast-food chains and delivery services.
Segmentations:
By Material Type:
- Plastic (Polypropylene, PET)
- Paperboard
- Bagasse
- Molded Fiber
- Aluminum
By Distribution Channel:
- Direct Sales
- Distributors and Wholesalers
- Retail Stores
- Online Platforms
By Capacity:
- 2-Compartment Trays
- 3-Compartment Trays
- 4-Compartment Trays
- 5-Compartment Trays and Above
By End Use:
- Institutional Foodservice (Schools, Hospitals, Correctional Facilities)
- Commercial Foodservice (Restaurants, Catering Services, QSRs)
- Airline and Rail Catering
- Household and Consumer Use
- Meal Kit and Food Delivery Services
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds 36% of the global food partition trays market due to strong institutional demand and widespread adoption of sustainable packaging. The United States remains the largest contributor, driven by federal nutrition programs, airline catering, and quick-service restaurant chains. It benefits from advanced foodservice infrastructure and strict hygiene regulations that support widespread tray usage. Local manufacturers offer a diverse range of recyclable and compostable tray options to meet evolving consumer and regulatory expectations. Canada also shows steady growth, supported by school meal programs and environmentally driven procurement policies. Regional focus on waste reduction and food safety compliance reinforces long-term market potential.
Europe :
Europe accounts for 29% of the global food partition trays market, fueled by strong environmental regulations and high usage in public catering services. Countries like Germany, France, and the United Kingdom are phasing out polystyrene trays and encouraging use of fiber-based and compostable alternatives. It supports demand in schools, healthcare institutions, and elderly care facilities where food safety and sustainability remain key priorities. EU policies promoting circular economy practices drive investments in material innovation and recycling infrastructure. Public-sector contracts and green procurement standards are shaping supplier strategies across the region. The market continues to evolve with demand for performance-based, eco-compliant packaging.
Asia Pacific :
Asia Pacific holds 21% of the global food partition trays market and is projected to register the fastest growth through 2032. Rising urbanization, growing food delivery networks, and expanding educational and healthcare systems drive demand in China, India, and Southeast Asia. It is supported by increasing awareness of hygiene in foodservice and a shift toward organized meal distribution. Government initiatives in mid-income economies are promoting improved public catering services, which creates opportunities for tray adoption. Regional manufacturers are scaling production of biodegradable trays to meet sustainability goals. The region presents strong long-term potential for local and global players.
Key Player Analysis:
- Amcor
- Anchor Packaging
- Be Green Packaging
- Genpak
- Novolex
- Huhtamaki
- Cascades
- Coveris
- Eco-Products
- Dart Container
Competitive Analysis:
The food partition trays market is moderately competitive, with key players focusing on sustainability, product customization, and cost efficiency to gain market share. Leading companies such as Amcor, Anchor Packaging, and Be Green Packaging are expanding their portfolios with biodegradable and compostable tray solutions to align with shifting regulatory and consumer preferences. It reflects strong competition in both institutional and commercial foodservice segments, where high-volume contracts and branding opportunities drive supplier differentiation. Global players leverage advanced manufacturing capabilities, material R&D, and wide distribution networks to maintain a competitive edge. Regional manufacturers compete by offering cost-effective solutions and rapid fulfillment to local buyers. Market competition continues to intensify as new entrants adopt innovative materials and digital sales models. Companies invest in automation, design enhancements, and sustainable sourcing to meet performance standards and environmental benchmarks, strengthening their position in a market shaped by hygiene, efficiency, and environmental responsibility.
Recent Developments:
- In June 2025, Amcor launched a first-of-its-kind more sustainable shrink bag designed for turkey packaging.
- In September 2024, Anchor Packaging launched its Culinary Tamper Safe™ Containers, which received a Gold award in the Hot New Products packaging category
- In April 2025, Novolex completed the acquisition of Pactiv Evergreen, creating a leading company in the food, beverage, and specialty packaging industries.
Market Concentration & Characteristics:
The food partition trays market exhibits moderate market concentration, with a mix of global packaging companies and regional manufacturers competing across segments. It features both standardized and customized products, catering to institutional, commercial, and consumer foodservice needs. Leading players focus on sustainable materials, cost-efficient production, and regulatory compliance to strengthen their market position. The market remains price-sensitive, especially in institutional procurement, where bulk volumes influence supplier selection. Entry barriers are relatively low, but scalability, material innovation, and distribution networks define competitive advantage. It reflects a balance between innovation-driven differentiation and high-volume utility-based demand across end-user sectors.
Report Coverage:
The research report offers an in-depth analysis based on Material, Distribution Channel, Capacity, End Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Manufacturers will expand use of biodegradable fibers, bagasse, and molded pulp in food partition trays.
- Producers will increase investment in lightweight, leak-resistant tray designs that support reheating and freezer storage.
- Brands will incorporate embossed logos, color codes, and tamper-evident features to enhance packaging appeal.
- Suppliers will form strategic partnerships with meal kit and food delivery platforms to provide co-branded tray solutions.
- Regional players will localize production to reduce logistics costs and shorten lead times in emerging markets.
- Foodservice operators will adopt standardized trays to streamline inventory management across multi-location operations.
- Regulatory agencies will tighten food safety and sustainability standards, pushing for certified compostable trays.
- Manufacturers will leverage automation and scale economies to lower per-unit tray costs for bulk buyers.
- Recycling and composting infrastructure will expand, encouraging procurement of eco-friendly packaging.
- Innovation in barrier coatings and compartmental separation will enhance tray functionality and shelf life.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Institutional Demand for Portion Control and Hygiene
Schools, hospitals, and correctional facilities require standardized meal portions and strict hygiene, driving adoption of partition trays that support portion control, reduce cross-contamination, and comply with food safety regulations.
Growth of Food Delivery and Ready-to-Eat Meals
The expansion of food delivery services and rising consumption of ready-to-eat meals have increased demand for trays that preserve food integrity, prevent mixing of meal components, and enhance consumer convenience during transit.
Shift Toward Sustainable and Eco-Friendly Packaging
Rising environmental awareness and regulatory mandates are pushing foodservice operators to adopt trays made from biodegradable, compostable, and recyclable materials, accelerating innovation and market growth in sustainable packaging solutions.
Stringent Food Safety Regulations
Global food safety standards require separation of allergens and prevention of cross-contact, making partition trays essential in both commercial and institutional foodservice to ensure compliance and protect consumer health.
Customization and Branding in Food Packaging
Food businesses are increasingly seeking customized, branded, and functional tray designs to enhance meal presentation, support marketing efforts, and improve operational efficiency, fueling demand for innovative partition tray solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Food partition trays market?
What are the key segments within the Food partition trays market?
What are some challenges faced by the Food partition trays market?
Who are the major players in the Food partition trays market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Institutional Foodservice (Schools, Hospitals, Correctional Facilities)
- 1.2.2 Commercial Foodservice (Restaurants, Catering Services, QSRs)
- 1.2.3 Airline and Rail Catering
- 1.2.4 Household and Consumer Use
- 1.2.5 Meal Kit and Food Delivery Services
- 1.3 By Capacity
- 1.3.1 2-Compartment Trays
- 1.3.2 3-Compartment Trays
- 1.3.3 4-Compartment Trays
- 1.3.4 5-Compartment Trays and Above
- 1.4 By Material Type
- 1.4.1 Plastic (Polypropylene, PET)
- 1.4.2 Paperboard
- 1.4.3 Bagasse
- 1.4.4 Molded Fiber
- 1.4.5 Aluminum
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,665 million → 2032: USD 5,589 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Partition Trays Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Partition Trays Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Partition Trays Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Partition Trays Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Partition Trays Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Partition Trays Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Partition Trays Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Partition Trays Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,665 million → 2032: USD 5,589 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Partition Trays Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Institutional Foodservice (Schools, Hospitals, Correctional Facilities)
- 12.3.7.2 Commercial Foodservice (Restaurants, Catering Services, QSRs)
- 12.3.7.3 Airline and Rail Catering
- 12.3.7.4 Household and Consumer Use
- 12.3.7.5 Meal Kit and Food Delivery Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Capacity - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 2-Compartment Trays
- 12.4.7.2 3-Compartment Trays
- 12.4.7.3 4-Compartment Trays
- 12.4.7.4 5-Compartment Trays and Above
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Plastic (Polypropylene, PET)
- 12.5.7.2 Paperboard
- 12.5.7.3 Bagasse
- 12.5.7.4 Molded Fiber
- 12.5.7.5 Aluminum
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Partition Trays End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Food Partition Trays Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Food Partition Trays Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Food Partition Trays Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Anchor Packaging
- 18.4 Be Green Packaging
- 18.5 Genpak
- 18.6 Novolex
- 18.7 Huhtamaki
- 18.8 Cascades
- 18.9 Coveris
- 18.10 Eco-Products
- 18.11 Dart Container
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

