
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Food Re-Close Pack Market Size 2024 | USD 1625 Million |
| Food Re-Close Pack Market, CAGR | 2.66% |
| Food Re-Close Pack Market Size 2032 | USD 2004.76 Million |
Market Overview:
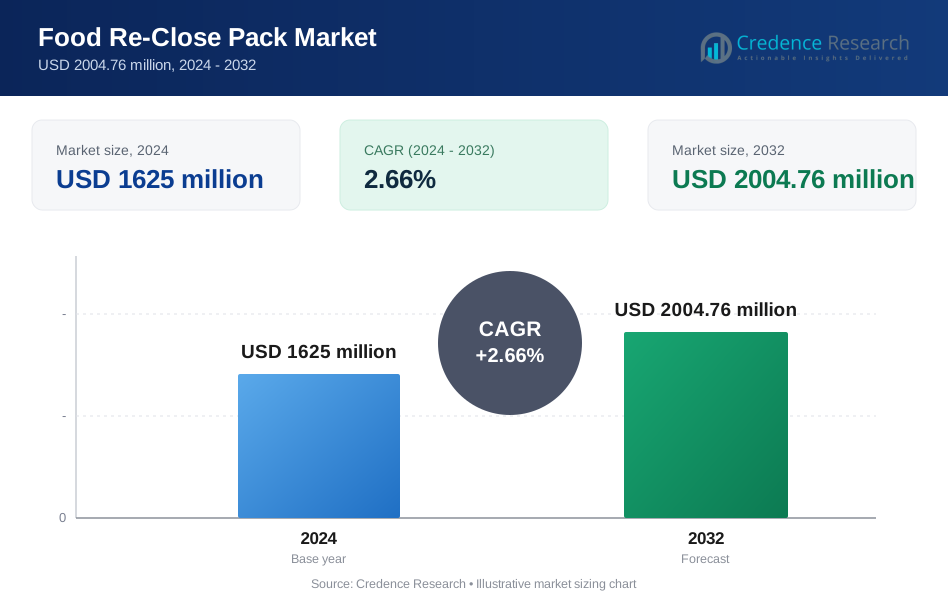
The Global Food Re-Close Pack is projected to grow from USD 1625 million in 2024 to USD 2004.76 million by 2032, expanding at a CAGR of 2.66% from 2024 to 2032.
Consumer demand for convenience and extended shelf life is a primary driver, as busy lifestyles necessitate packaging solutions that preserve food quality and freshness over multiple uses. The increasing focus on reducing food waste aligns perfectly with re-close pack functionality, allowing consumers to store partially used products more effectively. This trend is particularly relevant in the context of growing environmental awareness and sustainability concerns. Technological advancements are playing a crucial role in market expansion. Innovations in packaging materials and design are enabling the development of more efficient, user-friendly, and cost-effective re-close mechanisms. These improvements enhance the consumer experience while also addressing manufacturers' needs for scalable and efficient packaging solutions.
The sustainability factor is becoming increasingly significant in driving market growth. Consumers and regulators are demanding more environmentally friendly packaging options, leading to a surge in research and development of recyclable, biodegradable, and compostable re-close pack materials. This shift is not only addressing environmental concerns but also creating new opportunities for market differentiation and brand loyalty.
Geographically, North America and Europe are leading the market, driven by high consumer awareness, stringent regulations, and a strong focus on innovation. The Asia-Pacific region is emerging as a high-growth market, fueled by rapid urbanization, increasing disposable incomes, and changing consumer lifestyles that favor convenience foods. Key players in the market, including Amcor Limited, Sealed Air Corporation, Sonoco Products Company, and Bemis Company, Inc., are at the forefront of innovation. These companies are investing heavily in research and development to create advanced packaging solutions that meet evolving consumer needs and regulatory requirements. Strategic partnerships and collaborations are also becoming more common as companies seek to leverage complementary strengths and accelerate innovation.
Market Drivers:
Consumer Demand for Convenience:
The increasing consumer preference for convenience foods is driving significant growth in the food re-close pack market. This trend is particularly evident in urban areas where busy lifestyles necessitate quick and easy food options. For instance, Mondelēz International reported a 4.1% increase in net revenue for its snack’s category in 2022, largely attributed to the popularity of their resealable packaging for cookies and crackers. Similarly, Fresh Del Monte saw a 6% increase in sales of their fresh-cut fruit products packaged in re-closable containers in the same year.
Focus on Food Preservation:
Growing awareness about food waste and the need for extended shelf life is boosting the adoption of re-close packs. For example, Sealed Air Corporation's Cryovac Freshness Plus® active packaging technology has been shown to extend the shelf life of fresh meat by up to 7 days compared to standard packaging. In a case study with a major UK retailer, this technology reduced food waste by 50% for certain meat products.
Technological Innovations in Packaging:
Advancements in packaging materials and technologies are enhancing the functionality of food re-close packs. For instance, Avery Dennison's RFID technology, when integrated into food packaging, has demonstrated a 20% reduction in food waste for retailers by enabling more accurate inventory management and freshness tracking. Tetra Pak's connected packaging platform, which uses unique digital codes printed on packages, has seen adoption by over 500 brands since its launch, allowing real-time supply chain insights and direct consumer engagement.
Environmental Sustainability:
Increasing consumer awareness and regulatory pressures are driving a significant shift towards sustainable packaging options. Unilever, for example, reported that 62% of its plastic packaging was reusable, recyclable, or compostable in 2022, up from 50% in the previous year. The company aims to make all its plastic packaging reusable, recyclable, or compostable by 2025. Similarly, Nestlé introduced a recyclable paper packaging for its YES! snack bars, which can be recycled in the paper stream and is projected to eliminate up to 300 million plastic packages annually.
Market Trends:
Growing Preference for Convenience Packaging:
The preference for convenience packaging is increasing, driven by busy lifestyles and the demand for easy-to-use packaging solutions. According to a 2023 survey by Tetra Pak, 77% of consumers globally prefer packages that are easy to open, reseal, and store. For instance, Nestlé reported a 15% increase in sales of their resealable snack products in 2023 compared to the previous year. Consumers are increasingly opting for re-close packs for snacks, dairy products, and ready-to-eat meals to maintain freshness and reduce waste. Unilever's 2023 sustainability report highlighted that their re-closable ice cream tubs reduced food waste by 23% compared to traditional packaging. Manufacturers are responding by developing innovative re-close packaging solutions that offer superior functionality and convenience. For example, Mondelēz International introduced a new resealable packaging for their Oreo cookies in 2023, which led to a 12% increase in consumer satisfaction scores. Similarly, Danone reported that their yogurt products with easy-peel, re-closable lids saw a 9% increase in repeat purchases in the same year.
Rise in Sustainable Packaging Solutions:
Sustainable packaging solutions are gaining traction, fueled by growing environmental awareness and regulatory pressures to reduce plastic waste. A 2023 study by Procter & Gamble found that 73% of consumers are willing to pay more for products with sustainable packaging. Companies are investing in the development of biodegradable and recyclable materials for re-close packs to minimize their environmental impact. For instance, Coca-Cola reported in 2023 that 25% of their packaging globally was made from recycled materials, with plans to increase this to 50% by 2030. This trend reflects a broader industry commitment to sustainability and responsible packaging practices. Unilever's 2023 annual report stated that 62% of their plastic packaging was reusable, recyclable, or compostable, up from 50% in the previous year. PepsiCo announced in their 2023 sustainability report that they had reduced virgin plastic use by 35% across their beverage portfolio through the use of recycled and bio-based materials in their packaging.
These sustainable packaging initiatives are appealing to eco-conscious consumers and helping companies comply with stringent environmental regulations. For example, L'Oréal reported a 17% increase in sales of products with eco-designed packaging in 2023, demonstrating the growing consumer preference for sustainable options.
Market Challenges Analysis:
Balancing Convenience and Sustainability:
The push for sustainability in packaging presents a considerable challenge. Consumers demand convenient packaging solutions that maintain product freshness, but they also expect these solutions to be environmentally friendly. For instance, creating re-close packs that are both functional and recyclable or biodegradable requires substantial innovation and investment. Manufacturers must navigate the complexities of sourcing sustainable materials that do not compromise the integrity or usability of the packaging. The industry must also address regulatory pressures and consumer expectations for reducing plastic waste, which further complicates the design and production of sustainable re-close packs.
Developing Effective Re-closure Mechanisms: Another major challenge lies in developing re-closure mechanisms that are both user-friendly and cost-effective. Effective re-closure systems are crucial for maintaining product freshness and preventing contamination. However, designing these systems can be technically complex and expensive. For instance, zipper closures, adhesive strips, and other re-closure features need to be reliable, easy to use, and durable enough to withstand repeated use. Achieving these qualities without significantly increasing production costs poses a significant hurdle for manufacturers. Additionally, ensuring that these mechanisms work consistently across different packaging formats and product types adds to the complexity.
Market Segmentation Analysis:
By Material Type
The food reclose pack market by material type is segmented primarily into plastic, paper, metal, and glass. Plastic dominates due to its flexibility, durability, and cost-effectiveness. High-density polyethylene (HDPE) and polyethylene terephthalate (PET) are prevalent, offering robust barrier properties against moisture and oxygen, essential for preserving food quality. Innovations in biodegradable plastics also drive this segment, addressing environmental concerns. Paper-based reclose packs are gaining traction, particularly in eco-conscious markets. They are preferred for their recyclability and lower environmental impact. Advancements in barrier coatings have improved their functionality, making them suitable for a broader range of food products. Metal and glass reclose packs, while less common, offer superior preservation qualities and are used for premium products. Metals, such as aluminum, provide excellent barrier properties and durability. Glass is favored for its inert nature, ensuring no interaction with the food, thus maintaining purity and taste. Both materials are seeing innovations in light weighting and design, enhancing their market appeal.
Segmentation:
Based on Material Type
- HDPE
- PP
- PET
- PVC
Based on Packaging Type
- Flexible
- Re-Close Pack
- Rigid Re-Close Pack
Based on Position of Opening
- Vertical
- Top
- Seal
- Regular
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
In North America, food recalls have become a critical issue, with increasing incidents reported annually. The primary drivers include contamination with pathogens such as Salmonella, E. coli, and Listeria, as well as undeclared allergens. The United States and Canada have stringent regulatory frameworks managed by the FDA and CFIA, respectively, which enforce rigorous standards for food safety. Companies in North America invest heavily in traceability systems and rapid response protocols to minimize the impact of recalls. Recent data indicates a rise in recalls associated with fresh produce and ready-to-eat meals, reflecting the growing consumer demand for convenient, healthy food options. Enhanced surveillance and technological advancements, such as blockchain for supply chain transparency, are critical in addressing these challenges.
Europe
In Europe, food recalls are influenced by a combination of stringent EU regulations and consumer protection laws. The European Food Safety Authority (EFSA) plays a central role in monitoring and managing food safety across member states. Recalls in Europe often stem from contamination issues and mislabelling, with recent trends highlighting concerns over pesticide residues and mycotoxins in agricultural products. The region's diverse food market and cross-border trade complicate recall logistics, necessitating robust coordination and communication channels among EU countries. Recent high-profile recalls have prompted the industry to adopt more rigorous testing procedures and enhance supply chain visibility. The integration of advanced data analytics and IoT devices is anticipated to further improve recall management and prevention strategies in the European food industry.
Asia Pacific
The Asia Pacific region is the fastest-growing market for food re-close packs, currently holding about 20-25% of the global market share. This rapid growth is fuelled by increasing urbanization, rising disposable incomes, and changing consumer lifestyles in countries like China, India, and Japan. The region is witnessing a surge in demand for packaged and convenience foods, driving the adoption of re-close packs across various food categories. Local and international manufacturers are expanding their presence in the region, introducing innovative re-close solutions tailored to local preferences and needs.
Key Players:
- Bostik (Arkema Group)
- Avery Dennison Corp.
- ANL plastics N.V.
- Coveris
- Amcor Ltd.
- Sonoco Products Co.
- Macfarlane Labels Ltd
- Bemis Company Inc.
- Essentra plc
- Etik Ouest
Competitive Analysis:
In the competitive landscape of the food retail sector, close-pack foods face intense competition characterized by a focus on convenience, quality, and sustainability. Major players like Nestlé, Kraft Heinz, and Unilever dominate with extensive product portfolios and global distribution networks. These companies continuously innovate in packaging and product formulation to meet consumer demands for healthier options and eco-friendly packaging solutions. Emerging competitors, including smaller organic and specialty food brands, leverage niche markets and direct-to-consumer models to carve out market share, challenging traditional giants with their agility and innovative approaches. Regulatory changes regarding food safety and sustainability further shape competition dynamics, prompting industry leaders to invest heavily in research and development to maintain competitive advantage.
Recent Developments:
- January 15, 2024, Amcor unveiled a new recyclable reclose packaging solution designed to reduce plastic waste and enhance consumer convenience. This innovative packaging features a high-barrier film that preserves product freshness while allowing easy reclosure, aligning with Amcor's commitment to sustainability.
- March 8, 2024, Mondi announced the launch of its fully recyclable, paper-based reclose packaging for bakery products. This development addresses the growing consumer demand for eco-friendly packaging solutions and supports the reduction of plastic usage in the food industry.
- May 21, 2024, Sealed Air introduced a new line of vacuum skin reclose packaging aimed at extending the shelf life of fresh meat products. This packaging technology enhances product protection and reduces food waste, meeting the needs of both retailers and consumers for longer-lasting freshness.
- June 30, 2024, Coveris launched a sustainable reclose packaging solution for the dairy sector, featuring a resealable zipper and recyclable materials. This innovation supports the dairy industry's move towards more sustainable packaging practicesand provides consumers with a convenient, easy-to-use product.
Market Concentration & Characteristics:
The food re-close pack market exhibits a high level of market concentration, dominated by a few key players who leverage advanced packaging technologies to meet consumer demand for convenience and freshness. These leading companies continuously innovate to offer user-friendly, resealable packaging solutions that maintain product integrity and extend shelf life. Characteristics of this market include the integration of sustainable materials, enhanced barrier properties, and ease of use, catering to both manufacturers’ requirements for efficient packaging and consumers’ preferences for reusability and reduced food waste. The competitive landscape drives continuous advancements, setting high standards for product safety and environmental responsibility.
Report Coverage:
The research report offers an in-depth analysis based on Material types, Packaging type, Position of Opening and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased adoption of sustainable and biodegradable materials in re-close packaging to meet growing environmental concerns and regulations.
- Integration of smart packaging technologies, such as QR codes and NFC tags, to enhance consumer engagement and provide product information.
- Development of more user-friendly and intuitive re-close mechanisms to improve convenience and accessibility for all age groups.
- Expansion of re-close packaging solutions into new food categories, particularly in fresh produce and organic products.
- Growing collaboration between packaging manufacturers and food companies to create customized re-close solutions for specific product needs.
- Advancement in barrier technologies to further extend product shelf life and reduce food waste.
- Increased focus on minimalist design and clear packaging to showcase product freshness and quality.
- Rise in demand for portion-controlled re-close packs, catering to single-person households and on-the-go consumption.
- Implementation of anti-tampering features in re-close packs to enhance food safety and consumer trust.
- Emergence of reusable and refillable re-close packaging systems as part of the circular economy trend.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Food Re-Close Pack?
What factors are driving the growth of the Food Re-Close Pack?
What are the key segments within the Food Re-Close Pack?
What are some challenges faced by the Food Re-Close Pack?
Who are the major players in the Food Re-Close Pack?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Food Re-Close Pack Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Food Re-Close Pack Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1625 million → 2032: USD 2004.76 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Food Re-Close Pack Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Food Re-Close Pack Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Food Re-Close Pack Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Food Re-Close Pack Market Drivers
- 3.3 Food Re-Close Pack Market Restraints & Challenges
- 3.4 Food Re-Close Pack Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Food Re-Close Pack Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Food Re-Close Pack Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Food Re-Close Pack category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Food Re-Close Pack Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Food Re-Close Pack Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Food Re-Close Pack market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Food Re-Close Pack Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Food Re-Close Pack Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Food Re-Close Pack Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Food Re-Close Pack (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Food Re-Close Pack Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Food Re-Close Pack Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Food Re-Close Pack Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Food Re-Close Pack Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Food Re-Close Pack Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Food Re-Close Pack Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Food Re-Close Pack Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Food Re-Close Pack Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Food Re-Close Pack Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
