
Market Overview
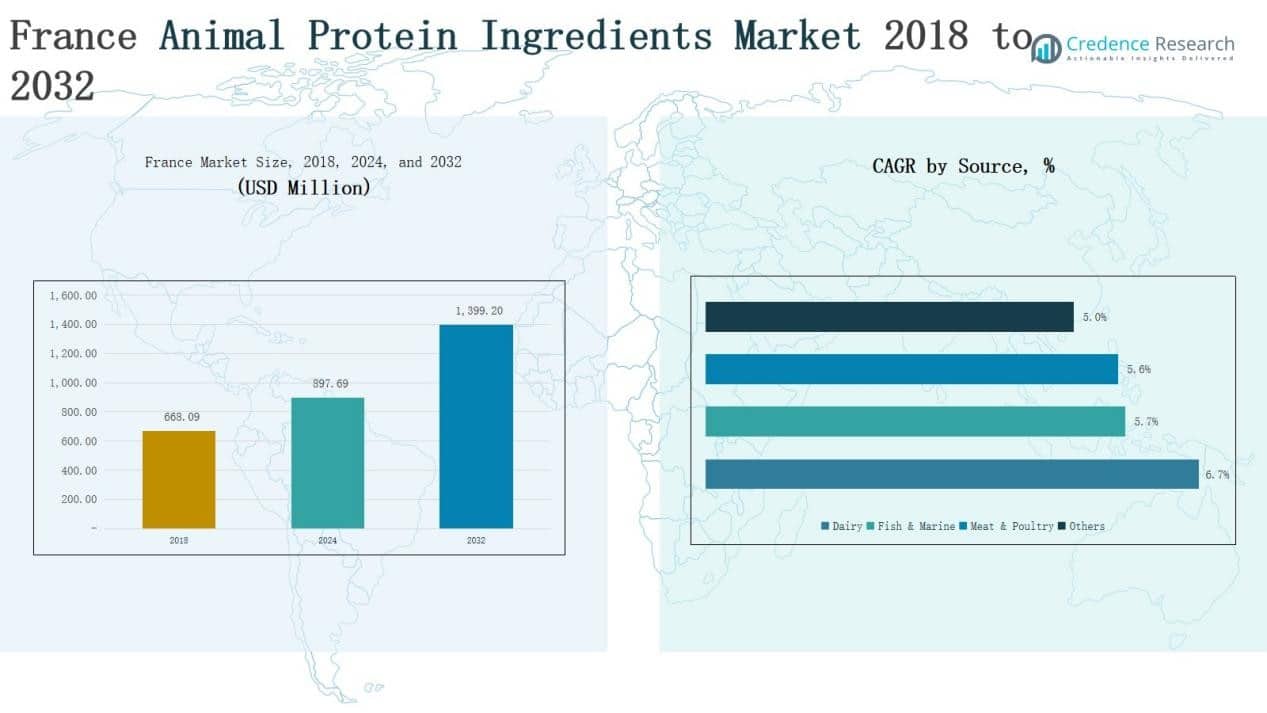
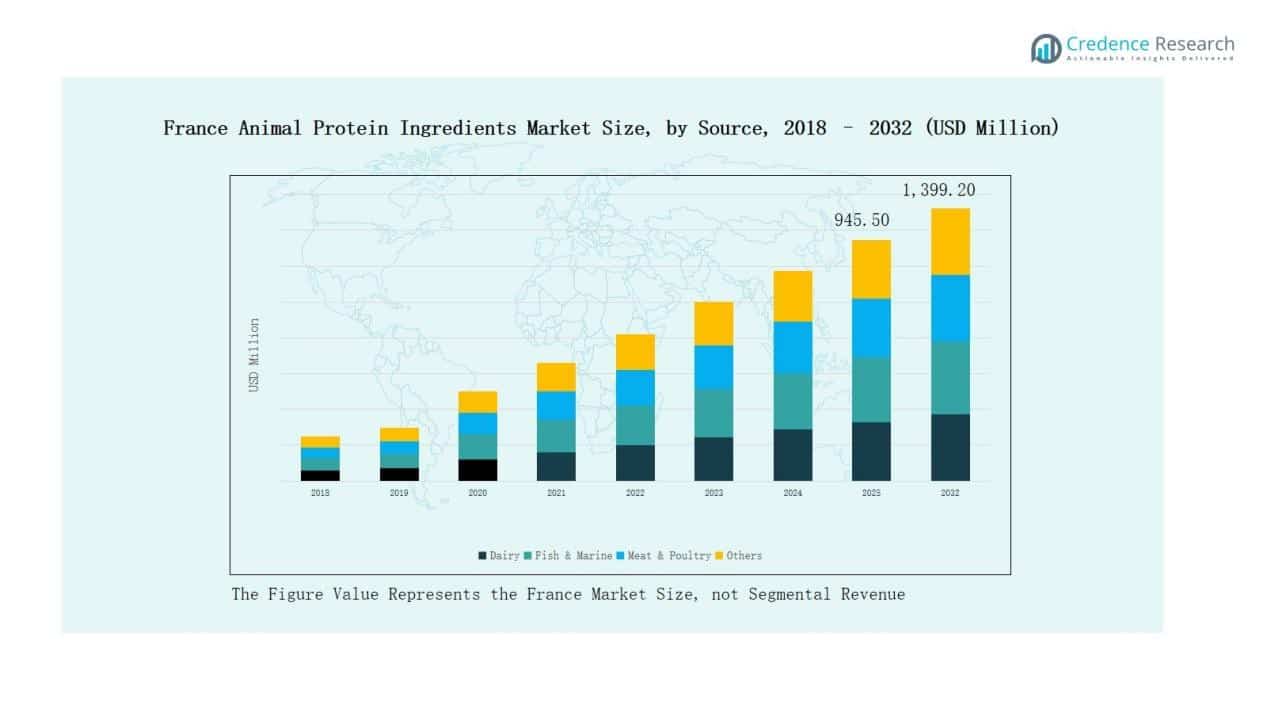
France Animal Protein Ingredients Market size was valued at USD 668.09 million in 2018, rising to USD 897.69 million in 2024, and is anticipated to reach USD 1,399.20 million by 2032, at a CAGR of 5.73% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Animal Protein Ingredients Market Size 2024 | USD 897.69 Million |
| France Animal Protein Ingredients Market, CAGR | 5.73% |
| France Animal Protein Ingredients Market Size 2032 | USD 1,399.20 Million |
The France Animal Protein Ingredients Market features strong competition among global and regional players, including Cargill, Tyson Foods, Darling Ingredients, Armor Proteines, Eurial I&N, Kemin Industries, Prinova, Saria Ltd, BHJ UK Ltd, and Kookaburra Limited. These companies maintain leadership through advanced processing technologies, broad product portfolios, and strategic investments in dairy, marine, and meat-based proteins. Innovation in functional and specialty applications, alongside sustainability initiatives, reinforces their market positions. Regionally, Île-de-France leads with a 29% market share in 2024, supported by its large consumer base, advanced healthcare infrastructure, and strong demand for clinical and sports nutrition products.
Market Insights
- The France Animal Protein Ingredients Market grew from USD 668.09 million in 2018 to USD 897.69 million in 2024 and is set to reach USD 1,399.20 million by 2032.
- Dairy leads the source segment with 42% share in 2024, driven by whey and casein demand in sports and clinical nutrition, supported by advanced dairy infrastructure.
- Powders dominate the form segment with 58% share in 2024, valued for storage, shelf life, and versatility across sports nutrition, medical supplements, and pet food.
- Sports and active nutrition holds 34% share in 2024, fueled by rising fitness awareness, while clinical nutrition and pet food also drive steady market expansion.
- Île-de-France leads regionally with 29% share in 2024, supported by advanced healthcare, dense population, innovation hubs, and strong demand for clinical and sports nutrition products.
Market Segment Insights
By Source
In the France Animal Protein Ingredients Market, dairy dominates the source segment, holding about 42% share in 2024. The strong preference for whey and casein proteins in sports and clinical nutrition drives this lead. Rising consumer focus on functional foods, advanced dairy processing facilities, and established export networks reinforce dairy’s dominance. Fish & marine proteins follow, supported by demand for collagen and omega-rich products in healthcare and cosmetics. Meat & poultry proteins contribute steadily, while the “others” category, including novel protein blends, gains traction through innovation.
- For instance, Roquette introduced Nutralys hydrolyzed pea protein blends in France, catering to novel high-digestibility applications, reflecting consumer interest in innovative protein alternatives.
By Form
Powders lead the form segment with nearly 58% share in 2024, as they offer easy storage, longer shelf life, and versatility across applications. Powders are widely used in sports nutrition, medical supplements, and pet food formulations, making them the most adopted form. Granules and flakes account for a moderate share, supported by their role in processed foods and animal feed. Liquid and paste formats capture a niche share, mainly in specialized formulations and ready-to-drink clinical products, where convenience and fast absorption are key drivers.
- For instance, Abbott introduced Ensure Complete, a ready-to-drink liquid nutrition product in North America, underscoring demand for convenience-oriented clinical nutrition solutions.
By Application
The sports and active nutrition segment holds the largest share at around 34% in 2024, fueled by rising health awareness, gym culture, and high demand for protein-enriched supplements. Clinical and medical nutrition follows closely, supported by France’s advanced healthcare infrastructure and the growing need for protein-based recovery diets among aging populations. Pet food represents a fast-growing segment, benefitting from premiumization trends and high spending on companion animals. Aquafeed and livestock feed sustain demand through France’s aquaculture and poultry industries, while other applications, including functional foods, add incremental growth opportunities.
Key Growth Drivers
Rising Demand for Sports and Clinical Nutrition
The growing adoption of protein-enriched supplements in sports and clinical nutrition is a major driver for the France Animal Protein Ingredients Market. French consumers are increasingly health-conscious, prioritizing functional foods and beverages that support muscle growth, recovery, and overall well-being. In addition, the healthcare sector uses dairy and marine-based proteins in therapeutic diets for aging populations and patients with chronic conditions. This demand sustains consistent growth and positions animal protein ingredients as essential components in both wellness and medical applications.
- For instance, FrieslandCampina supplies dairy-based protein ingredients for therapeutic dietary products in France, which are used in healthcare settings targeting aging populations and chronic disease patients to enhance nutritional intake and recovery.
Strong Dairy Infrastructure and Innovation
France benefits from a robust dairy industry, supported by advanced processing facilities and a rich history of milk production. This infrastructure strengthens the supply of high-quality whey, casein, and other dairy-derived proteins. Producers are also investing in innovative protein formulations for sports drinks, medical nutrition, and premium pet food. The ability to combine tradition with innovation enhances competitiveness and ensures the availability of diverse, value-added protein products. This strong base reinforces dairy’s dominance as the leading source segment in the French market.
- For instance, Sodiaal launched a range of dairy protein-based ingredients aimed at the pet food industry, emphasizing digestibility and premium protein content.
Expanding Pet Food and Livestock Industry
The premiumization of pet food and the growing livestock industry are accelerating demand for animal protein ingredients. French consumers are increasingly spending on high-quality, protein-rich formulations for companion animals, driving steady growth in the pet food segment. At the same time, aquafeed and livestock feed applications require consistent protein supplies to support animal health and productivity. This dual demand strengthens the market’s long-term outlook and encourages producers to develop tailored solutions for both pets and commercial animal husbandry.
Key Trends & Opportunities
Shift Toward Functional and Specialty Proteins
A rising trend in France is the use of animal proteins in functional and specialty applications. Dairy proteins enriched with bioactive compounds and marine-based collagen are increasingly used in cosmetics, nutraceuticals, and healthcare. Consumers are drawn to products that offer more than basic nutrition, including benefits for skin health, bone strength, and disease prevention. This shift creates opportunities for innovation in premium product segments, positioning animal proteins as value-added ingredients in high-growth industries beyond traditional food and beverage categories.
- For instance, Rousselot, a Darling Ingredients brand, announced the expansion of its Peptan marine collagen peptides in the European market, formulated for beauty-from-within applications such as skin elasticity and joint health.
Sustainability and Responsible Sourcing Practices
French consumers place high importance on sustainability and ethical sourcing. This trend is pushing companies to adopt transparent supply chains, reduce environmental footprints, and invest in circular economy models. Marine protein producers emphasize sustainable fishing, while dairy processors focus on carbon-neutral production. These practices not only meet regulatory requirements but also enhance brand value in competitive markets. The focus on sustainability opens opportunities for differentiation and strengthens consumer trust, creating a favorable environment for responsible market players.
- For instance, Danone launched a regenerative agriculture program in France covering over 20,000 hectares of dairy farms, aiming to cut methane emissions and promote biodiversity in its milk supply chain.
Key Challenges
Rising Competition from Plant-Based Alternatives
One of the primary challenges for the France Animal Protein Ingredients Market is the rising popularity of plant-based proteins. French consumers, especially younger demographics, are embracing vegan and flexitarian diets. Plant proteins like pea, soy, and rice are promoted as sustainable and ethical alternatives. This shift poses a direct threat to animal-based ingredients, forcing companies to innovate and highlight unique nutritional advantages, such as complete amino acid profiles. Without differentiation, animal protein products risk losing share to fast-expanding plant-based solutions.
Price Volatility and Supply Chain Constraints
The market faces significant risks from price fluctuations in raw materials and supply chain disruptions. Dairy, fish, and meat-based proteins are sensitive to seasonal variations, feed costs, and global trade dynamics. In addition, geopolitical factors and transportation bottlenecks can strain supply security. Such volatility impacts production costs, which in turn pressures profit margins for both producers and distributors. Ensuring consistent supply and adopting long-term procurement strategies remain critical to stabilizing operations in this competitive environment.
Stringent Regulations and Compliance Requirements
France enforces strict food safety, environmental, and labeling regulations, which can challenge animal protein producers. Compliance involves significant investment in quality testing, certification, and documentation processes. Smaller players often struggle to meet these requirements, limiting their market reach compared to larger, established companies. Moreover, growing scrutiny on sustainability and animal welfare adds further layers of compliance. These regulatory complexities increase operational costs and slow down product launches, creating hurdles for market expansion and innovation.
Regional Analysis
Île-de-France
Île-de-France leads the France Animal Protein Ingredients Market with a 29% share in 2024. The region benefits from its dense population, advanced healthcare infrastructure, and strong demand for clinical nutrition and functional foods. Its urban consumer base actively adopts protein-enriched products in sports and medical applications. The presence of multinational companies and research hubs further accelerates innovation. The region also supports premium pet food consumption, strengthening demand across multiple segments. It continues to serve as a central hub for product development and distribution.
Auvergne-Rhône-Alpes
Auvergne-Rhône-Alpes holds a 22% share in 2024, driven by its strong food processing industry and livestock sector. The region is known for dairy production, which sustains the supply of whey and casein proteins. Sports and active nutrition products see high adoption among its health-conscious population. Pet food and aquafeed applications also contribute significantly to growth. Its industrial base supports large-scale protein processing facilities, helping local players meet rising domestic demand. The region positions itself as a vital contributor to national production and exports.
Nouvelle-Aquitaine
Nouvelle-Aquitaine accounts for 18% of the market in 2024, supported by its prominence in fisheries and meat production. Marine protein ingredients derived from fish and collagen find strong demand in nutraceuticals and cosmetics. The livestock industry in the region sustains steady consumption of animal protein ingredients for feed applications. Its consumers also favor protein-based sports and wellness products. Local companies leverage regional strengths to target high-value applications in healthcare and personal care. It remains an emerging hub for innovation in marine-based protein solutions.
Occitanie
Occitanie captures a 16% market share in 2024, largely supported by its livestock and poultry base. The region provides consistent demand for animal protein ingredients used in aquafeed and livestock feed. Its growing urban centers also contribute to rising demand for sports nutrition and clinical dietary supplements. Strong agricultural infrastructure ensures stable raw material supply for processing industries. Companies in the region focus on feed efficiency and pet nutrition to maximize opportunities. It continues to consolidate its role as a balanced contributor to national growth.
Provence-Alpes-Côte d’Azur (PACA)
Provence-Alpes-Côte d’Azur holds a 15% share in 2024, supported by high consumer spending on premium and lifestyle-oriented nutrition products. The region’s urban population drives demand for protein-enriched foods, sports supplements, and clinical applications. Marine protein ingredients also gain traction, reflecting the region’s access to Mediterranean fisheries. Growth in pet food and specialized healthcare nutrition further supports expansion. Companies capitalize on affluent markets to promote high-value protein offerings. It remains a strong consumer-driven market with growing adoption of specialty animal proteins.
Market Segmentations:
By Source
- Dairy
- Fish & Marine
- Meat & Poultry
- Others
By Form
- Powders
- Granules/Flakes
- Liquids/Pastes
By Application
- Sports & Active Nutrition
- Clinical & Medical Nutrition
- Pet Food
- Aquafeed & Livestock Feed
- Others
By Region
- Île-de-France
- Auvergne-Rhône-Alpes
- Nouvelle-Aquitaine
- Occitanie
- Provence-Alpes-Côte d’Azur (PACA)
Competitive Landscape
The France Animal Protein Ingredients Market is characterized by a balanced mix of multinational corporations and domestic players competing across diverse applications. Leading companies such as Cargill, Tyson Foods, Darling Ingredients, Armor Proteines, and Eurial I&N dominate through strong product portfolios, advanced processing technologies, and well-established distribution networks. These firms emphasize innovation in dairy and marine proteins to meet rising demand in sports, clinical nutrition, and pet food sectors. Regional companies including Saria Ltd, BHJ UK Ltd, and Kookaburra Limited strengthen competition by focusing on livestock feed and sustainable sourcing. Market participants actively pursue partnerships, acquisitions, and new product launches to enhance market penetration and expand into high-value applications such as nutraceuticals and functional foods. The competitive environment remains dynamic, with a clear focus on differentiation through sustainability, premiumization, and tailored solutions that align with evolving consumer preferences and strict regulatory standards in France.
Key Players
- Eurial I&N
- Saria Ltd
- BHJ UK Ltd
- Kookaburra Limited
- Cargill
- Kemin Industries
- Prinova
- Darling Ingredients
- Armor Proteines
- Tyson Foods
- Other Key Players
Recent Developments
- In June 2025, Lesaffre completed the acquisition of Biorigin from Zilor to strengthen its animal nutrition portfolio.
- In January 2025, Bon Vivant received self-affirmed GRAS status in the US for its precision-fermented whey protein (animal-free β-lactoglobulin).
- In March 2023, Gelita AG launched Confixx, a novel gelatin innovation designed for starch-free gummy production, aimed at supplement manufacturers.
- In April 2024, Arla Foods Ingredients signed an agreement to acquire the Whey Nutrition division of the UK-based Volac business, with completion expected later in 2024.
Report Coverage
The research report offers an in-depth analysis based on Source, Form, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Dairy proteins will continue to lead due to strong demand in nutrition and healthcare.
- Marine-based proteins will gain traction in cosmetics and nutraceutical applications.
- Pet food will emerge as one of the fastest-growing application areas.
- Sports and active nutrition will expand with rising health and fitness awareness.
- Clinical nutrition will see steady growth driven by aging populations and medical needs.
- Powder formats will remain dominant for their versatility and wide adoption.
- Granules and flakes will see growth in feed and processed food industries.
- Sustainability and ethical sourcing will become major competitive differentiators.
- Product innovation will focus on functional and specialty protein blends.
- Domestic and international players will strengthen presence through partnerships and acquisitions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Sports and Clinical Nutrition
Increasing health consciousness and the popularity of fitness culture in France are driving demand for animal protein ingredients in sports and clinical nutrition products. These ingredients are valued for their role in muscle recovery, therapeutic diets, and overall wellness, especially among aging populations and active consumers.
Strong Dairy Infrastructure and Innovation
France's advanced dairy processing facilities and established milk production support a robust supply of high-quality whey and casein proteins. Ongoing investments in innovative formulations for sports, medical, and pet nutrition reinforce dairy's dominance and expand the market's value-added offerings.
Premiumization of Pet Food and Livestock Feed
French consumers are spending more on premium, protein-rich pet food, while the livestock and aquaculture sectors require consistent, high-quality protein ingredients. This dual demand from companion animal and commercial feed applications sustains steady market growth.
Expansion of Functional and Specialty Protein Applications
Animal proteins are increasingly used in functional foods, nutraceuticals, and cosmetics, with products like marine collagen and bioactive dairy proteins gaining traction. This trend toward specialty applications opens new high-value market segments beyond traditional food and beverage uses.
Focus on Sustainability and Responsible Sourcing
Consumer and regulatory emphasis on sustainability is pushing producers to adopt transparent supply chains, carbon-neutral production, and ethical sourcing practices. These initiatives not only meet compliance requirements but also enhance brand value and consumer trust in a competitive market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for France Animal Protein Ingredients Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the France Animal Protein Ingredients Market projected to grow between 2025 and 2032?
Which France Animal Protein Ingredients Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the France Animal Protein Ingredients Market?
Who are the leading companies in the France Animal Protein Ingredients Market?
Which region commanded the largest share of the France Animal Protein Ingredients Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Powders
- 1.2.2 Granules/Flakes
- 1.2.3 Liquids/Pastes
- 1.3 By Source
- 1.3.1 Dairy
- 1.3.2 Fish & Marine
- 1.3.3 Meat & Poultry
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Sports & Active Nutrition
- 1.4.2 Clinical & Medical Nutrition
- 1.4.3 Pet Food
- 1.4.4 Aquafeed & Livestock Feed
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 897.69 million → 2032: USD 1,399.20 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 France Animal Protein Ingredients Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 France Animal Protein Ingredients Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 France Animal Protein Ingredients Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 France Animal Protein Ingredients Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 France Animal Protein Ingredients Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 France Animal Protein Ingredients Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 France Animal Protein Ingredients Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 France Animal Protein Ingredients Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 897.69 million → 2032: USD 1,399.20 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 France Animal Protein Ingredients Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Powders
- 12.3.7.2 Granules/Flakes
- 12.3.7.3 Liquids/Pastes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dairy
- 12.4.7.2 Fish & Marine
- 12.4.7.3 Meat & Poultry
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Sports & Active Nutrition
- 12.5.7.2 Clinical & Medical Nutrition
- 12.5.7.3 Pet Food
- 12.5.7.4 Aquafeed & Livestock Feed
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 France Animal Protein Ingredients End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 France Animal Protein Ingredients Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 France Animal Protein Ingredients Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 France Animal Protein Ingredients Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cargill
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Tyson Foods
- 18.4 Darling Ingredients
- 18.5 Armor Proteines
- 18.6 Eurial I&N
- 18.7 Kemin Industries
- 18.8 Prinova
- 18.9 Saria Ltd
- 18.10 BHJ UK Ltd
- 18.11 Kookaburra Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

