
Market Overview
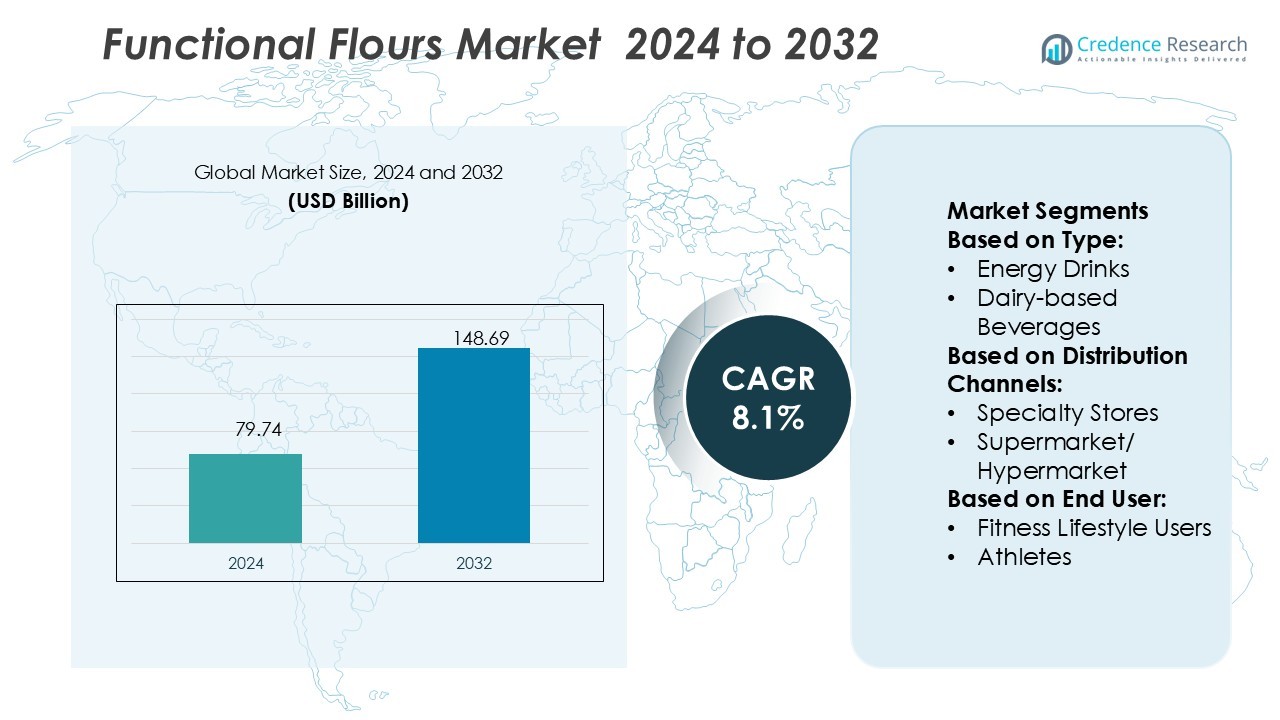
Functional Flours Market size was valued USD 79.74 billion in 2024 and is anticipated to reach USD 148.69 billion by 2032, at a CAGR of 8.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Functional Flours Market Size 2024 | USD 79.74 Billion |
| Functional Flours Market, CAGR | 8.1% |
| Functional Flours Market Size 2032 | USD 148.69 Billion |
The functional flours market is driven by prominent players including Archer Daniels Midland (ADM), Ardent Mills, Bay State Milling Company, Central Milling, General Mills, Giusto’s, Great River Organic Milling, Janie’s Mill, Doves Farm Foods, and Kaizen Food Company. These companies compete through innovation in gluten-free, fortified, and plant-based offerings, while also investing in sustainable sourcing and advanced processing technologies. Strategic expansions across retail and e-commerce channels further strengthen their positions. Regionally, North America leads the functional flours market with a 34% share in 2025, supported by strong consumer demand for clean-label, health-oriented products and the presence of major multinational manufacturers.
Market Insights
- The functional flours market was valued at USD 79.74 billion in 2024 and is projected to reach USD 148.69 billion by 2032, growing at a CAGR of 8.1%.
- Market growth is driven by rising health awareness, increasing demand for gluten-free and fortified products, and expanding adoption of plant-based diets among urban consumers.
- Key trends include clean-label innovations, sustainable sourcing, and the expansion of e-commerce channels, which enhance product visibility and consumer reach across global markets.
- Competitive dynamics are shaped by major players focusing on technological advancements, portfolio diversification, and strategic partnerships, while high production costs and regulatory complexities remain significant restraints.
- Regionally, North America dominates with a 34% share in 2025, supported by strong consumer demand and presence of leading manufacturers, while energy drinks lead the type segment with a 37% share, reflecting strong preference for quick energy and performance-focused products.
Market Segmentation Analysis:
By Type
Within the functional flours market, energy drinks dominate this segment with a 37% share in 2025. Their popularity stems from rising health-consciousness, demand for quick energy, and widespread acceptance among young consumers and working professionals. Dairy-based beverages follow, driven by protein enrichment and digestive health benefits. Sports drinks and juices also capture attention, though their shares remain lower due to intense competition. The “others” category, including plant-based beverages, is gaining traction, fueled by vegan lifestyles and clean-label preferences, which further strengthen diversification within the market landscape.
- For instance, Danone’s Research & Innovation centers hold over 5,000 patents and patent applications globally, underscoring their investment in ingredient innovations and functional formulations.
By Distribution Channels
Supermarkets and hypermarkets hold the largest share at 42% in 2025, reflecting consumer preference for convenience and variety. These outlets provide broad assortments and promotional offers, making them dominant sales channels. Specialty stores remain significant for premium and tailored functional flours, appealing to niche fitness consumers. E-commerce continues to grow rapidly, supported by online subscription models and home delivery services. Other channels, including local stores, still contribute but are less impactful, primarily serving rural areas and value-conscious customers who prioritize accessibility and price sensitivity.
- For instance, Coca-Cola engineered its Freestyle dispenser’s touchless user interface using AWS serverless tech in 150 days, enabling frictionless beverage dispensing and system responsiveness even under high transaction volumes.
By End-User
Athletes lead the end-user segment with a 46% share in 2025, reflecting their consistent reliance on functional flours for energy and performance enhancement. This group values scientifically formulated products and invests heavily in sports nutrition. Fitness lifestyle users account for a growing share, supported by increasing gym memberships and wellness-driven diets among urban populations. The “others” category, including general consumers seeking occasional health boosts, remains smaller but shows gradual expansion. Strong marketing campaigns targeting lifestyle wellness and preventive health trends further support growth across non-athlete demographics.
Key Growth Drivers
Rising Demand for Health and Wellness Products
The functional flours market is expanding due to increasing consumer focus on health and wellness. Consumers actively seek nutrient-rich flours that support digestion, weight management, and overall immunity. The rise in chronic health conditions, coupled with awareness of preventive nutrition, accelerates demand. Functional flours enriched with fibers, proteins, and bioactive compounds align well with these needs. Health-conscious urban populations and younger demographics drive sustained consumption, making health benefits a central factor influencing product innovation, brand positioning, and market growth.
- For instance, AmeriGas, a part of UGI Corporation, operates a vast network across the United States. Recent UGI financial filings confirm a network of approximately 1,360 propane distribution locations serving customers across the country.
Expansion of Functional Food and Beverage Industry
The growing functional food and beverage sector significantly drives the functional flours market. Manufacturers integrate functional flours into bakery, dairy, beverages, and snack products to meet consumer demand for fortified offerings. Product launches highlight clean-label, gluten-free, and plant-based innovations that cater to diverse dietary preferences. The expansion of fortified categories in supermarkets and online platforms also fuels growth. This integration not only enhances product value but also strengthens brand competitiveness, leading to higher adoption rates across both developed and emerging economies.
- For instance, Nutrien’s retail arm markets its Riser® in-furrow nutrition system for row crops, which applies micronutrient blends (e.g., zinc, boron) at a rate of 2.0 to 5.0 gallons (approximately 7.6 to 18.9 liters) per acre along with base fertilizer, ensuring forage or feed crops receive balanced nutrition early in growth.
Technological Advancements in Food Processing
Advancements in food processing technologies strengthen the market by improving quality, texture, and nutritional stability of functional flours. Innovations in extrusion, milling, and enzyme applications enhance flour fortification while retaining natural properties. These developments allow manufacturers to create customized solutions targeting specific health needs such as heart health, gut health, or energy enhancement. Technology also supports shelf-life extension and scalable production, meeting the rising demand across varied regions. Such advancements provide companies with opportunities to diversify offerings and expand market presence.
Key Trends & Opportunities
Growth of Plant-Based and Gluten-Free Products
The surge in plant-based diets and rising gluten intolerance cases present strong opportunities for functional flours. Consumers increasingly choose flours derived from legumes, seeds, and ancient grains for their nutritional value and allergen-free properties. This trend is evident in bakery and snack segments, where gluten-free innovations drive higher shelf visibility. Companies investing in non-wheat functional flours strengthen their market edge, appealing to vegan, vegetarian, and health-conscious buyers. The shift toward plant-forward lifestyles ensures continued expansion of this opportunity.
- For instance, LMK Thermosafe’s Thermosafe Type B Induction Drum Heater warms a 205-liter steel drum using an alternating current power source, such as a 110/120V supply rated at 1,500 watts. Two units can be stacked to cover the full drum height safely in Zone 2 areas.
E-Commerce and Direct-to-Consumer Channels
E-commerce platforms and direct-to-consumer models open new growth avenues for functional flours. Online retail offers greater convenience, diverse product availability, and personalized subscription services. Digital platforms also enable targeted marketing campaigns that highlight nutritional benefits and recipe adaptability, increasing consumer engagement. Smaller brands gain equal visibility, while global players use online strategies to expand reach across emerging markets. The continued shift toward digital retail ensures that e-commerce remains a critical growth driver for sales and consumer connection in the functional flours market.
- For instance, Cochran's official specification shows that the ST25 delivers an exact steam output range of 500 to 6 500 kg/hr at feed-and-allowance 100 °C .This numeric capacity underlines its ability to sustain continuous steam flow in demanding operational.
Key Challenges
High Production and Processing Costs
The functional flours market faces challenges from elevated production and processing costs. Advanced technologies, ingredient sourcing, and quality assurance raise expenses significantly compared to conventional flours. These costs often translate into higher retail prices, limiting affordability among price-sensitive consumers. Small-scale manufacturers struggle to compete, while larger companies require continuous investments to maintain economies of scale. Balancing innovation with cost-efficiency remains essential, as affordability strongly influences adoption rates, especially in developing economies with limited consumer spending power.
Regulatory and Labeling Complexities
Regulatory and labeling requirements present another challenge in the functional flours market. Governments impose strict guidelines on claims related to health benefits, nutritional composition, and product safety. Companies must navigate complex regional compliance frameworks, leading to higher operational and certification costs. Mislabeling risks damage brand credibility and consumer trust. The need for clear, science-backed product communication further complicates marketing strategies. Addressing these challenges requires investment in R&D, transparent labeling practices, and close alignment with evolving food safety regulations across global markets.
Regional Analysis
North America
North America leads the functional flours market with a 34% share in 2025, supported by high demand for fortified and gluten-free products. Rising health awareness, coupled with the popularity of plant-based diets, drives consistent adoption. The U.S. dominates regional growth due to strong retail penetration, innovation in clean-label products, and the presence of leading food manufacturers. Canada follows with rising consumer preference for natural flours and expanding health-conscious lifestyles. Strategic product launches and investments in research further strengthen North America’s position as a dominant and innovation-driven market in the global landscape.
Europe
Europe holds a 29% share in the functional flours market in 2025, driven by increasing consumption of organic and non-GMO products. Countries like Germany, the UK, and France lead demand due to strong regulatory frameworks promoting healthier diets. The region shows high acceptance of plant-based and gluten-free flours, reflecting shifting consumer preferences. Manufacturers focus on expanding fortified bakery and dairy offerings, aligning with sustainability goals. The presence of multinational players and innovation in ancient grain-based flours position Europe as a mature yet evolving market with stable growth prospects.
Asia-Pacific
Asia-Pacific accounts for 24% of the functional flours market in 2025, emerging as the fastest-growing region. China and India drive significant demand due to rising urbanization, disposable incomes, and increasing adoption of functional foods. Japan and South Korea show strong demand for fortified flours in bakery and snacks. The region benefits from a growing middle class that prioritizes preventive health and nutrition. Expansion of e-commerce platforms further accelerates accessibility. Local and international manufacturers are investing heavily, leveraging cultural dietary preferences to introduce innovative products, strengthening Asia-Pacific’s role as a key growth hub.
Latin America
Latin America represents 7% of the functional flours market in 2025, with Brazil and Mexico as primary contributors. Demand is supported by growing health awareness and the rising popularity of fortified bakery and beverage products. Regional adoption is slower compared to developed markets, constrained by pricing challenges and limited product availability. However, urban consumers are increasingly adopting health-focused diets, fueling gradual growth. Multinational companies expand their presence through partnerships and product launches, while local players focus on cost-effective solutions. Latin America remains an emerging market with untapped potential for functional flour innovation and distribution expansion.
Middle East and Africa
The Middle East and Africa capture 6% of the functional flours market in 2025, showing steady growth from rising urbanization and awareness of nutritional benefits. Countries like the UAE and South Africa lead adoption, driven by demand for fortified flours in bakery and processed foods. Affordability challenges and limited consumer awareness in rural areas restrict wider penetration. However, increasing investments in food innovation and retail modernization support market expansion. International brands, alongside regional companies, target premium health-conscious segments. With gradual lifestyle shifts, MEA holds long-term growth opportunities, especially through e-commerce and tailored product offerings.
Market Segmentations:
By Type:
- Energy Drinks
- Dairy-based Beverages
By Distribution Channels:
- Specialty Stores
- Supermarket/ Hypermarket
By End User:
- Fitness Lifestyle Users
- Athletes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the functional flours market features leading players such as Janie’s Mill, Great River Organic Milling, Kaizen Food Company, Ardent Mills, General Mills, Giusto’s, Archer Daniels Midland (ADM), Central Milling, Doves Farm Foods, and Bay State Milling Company. The competitive landscape of the functional flours market is shaped by continuous innovation, strong distribution strategies, and growing emphasis on health-focused product development. Companies in this sector focus on expanding portfolios with fortified, gluten-free, and plant-based flours to meet rising consumer demand for nutritious and clean-label options. Strategic investments in processing technologies enhance product quality, shelf-life, and scalability, enabling businesses to strengthen their global presence. Partnerships with retailers and e-commerce platforms further improve accessibility and market penetration. Additionally, sustainability initiatives, such as organic sourcing and eco-friendly packaging, remain central to competitive positioning and long-term growth in the market.
Key Player Analysis
- Janie’s Mill
- Great River Organic Milling
- Kaizen Food Company
- Ardent Mills
- General Mills
- Giusto’s
- Archer Daniels Midland (ADM)
- Central Milling
- Doves Farm Foods
- Bay State Milling Company
Recent Developments
- In May 2025, Tata Consumers announced plans to expand its food and beverage business with new product launches and acquisitions. With a focus on functional drinks, premium foods, and selective market entry, the FMCG firm targets urban growth and evolving consumer needs to drive future revenue.
- In March 2025, PepsiCo acquired Poppi for to expand into the fast-growing prebiotic soda and functional beverage market. The deal includes USD 300 million in anticipated tax benefits.
- In March 2025, Entertainment icon Snoop Dogg invested in a partnership with Harmony Craft Beverages to release a range of cannabis and functional drinks named Iconic Tonics. As wellness and mindful drinking trends accelerate, the musical artist’s move to release Ikonic Tonics is well-timed for the sector.
- In January 2025, Reliance Consumer Products Ltd (RCPL), a subsidiary of Reliance Industries, launched a new rehydration beverage, RasKik Gluco Energy, priced at an affordable Rs 10 for a single-serve drink. The beverage combines electrolytes, glucose, and real lemon juice, offering a refreshing solution for consumers seeking both hydration and energy.
Report Coverage
The research report offers an in-depth analysis based on Type, Distribution Channels, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The functional flours market will expand with rising demand for health-focused diets.
- Gluten-free and plant-based flours will gain stronger consumer acceptance.
- Advances in food processing will improve quality and nutritional retention.
- E-commerce channels will play a larger role in market growth.
- Clean-label and non-GMO flours will dominate product innovation strategies.
- Emerging economies will drive significant demand due to urbanization and lifestyle shifts.
- Strategic partnerships will enhance product distribution and consumer reach.
- Sustainability and organic sourcing will remain central to competitive differentiation.
- Customized functional flours targeting specific health benefits will increase adoption.
- Strong marketing of nutritional advantages will boost consumer awareness and loyalty.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Health and Wellness Focus
Consumers are increasingly seeking nutrient-rich flours that support digestion, weight management, and immunity, driving demand for functional flours enriched with fibers, proteins, and bioactive compounds.
Expansion of Functional Food and Beverage Industry
Manufacturers are integrating functional flours into a wide range of products such as bakery, dairy, beverages, and snacks, responding to consumer demand for fortified, clean-label, and plant-based offerings.
Technological Advancements in Food Processing
Innovations in milling, extrusion, and enzyme applications are enabling the production of customized, high-quality functional flours with improved nutritional stability and shelf-life, supporting market growth.
Growth of Plant-Based and Gluten-Free Products
Rising adoption of plant-based diets and increased gluten intolerance are fueling demand for flours derived from legumes, seeds, and ancient grains, especially in bakery and snack segments.
E-Commerce and Direct-to-Consumer Channels
The rapid growth of online retail and subscription models is making functional flours more accessible, allowing brands to reach a broader audience and educate consumers about health benefits.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Functional Flours Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Functional Flours Market projected to grow between 2025 and 2032?
Which Functional Flours Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Functional Flours Market?
Who are the leading companies in the Functional Flours Market?
Which region commanded the largest share of the Functional Flours Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Energy Drinks
- 1.2.2 Dairy-based Beverages
- 1.2.3 Sports Drinks
- 1.2.4 Juices
- 1.2.5 Plant-based Beverages
- 1.2.6 Others
- 1.3 By End User
- 1.3.1 Athletes
- 1.3.2 Fitness Lifestyle Users
- 1.3.3 General Consumers
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 79.74 billion → 2032: USD 148.69 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Functional Flours Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Functional Flours Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Functional Flours Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Functional Flours Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Functional Flours Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Functional Flours Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Functional Flours Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Functional Flours Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 79.74 billion → 2032: USD 148.69 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Functional Flours Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Energy Drinks
- 12.3.7.2 Dairy-based Beverages
- 12.3.7.3 Sports Drinks
- 12.3.7.4 Juices
- 12.3.7.5 Plant-based Beverages
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Athletes
- 12.4.7.2 Fitness Lifestyle Users
- 12.4.7.3 General Consumers
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Functional Flours End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Functional Flours Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Functional Flours Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Functional Flours Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Archer Daniels Midland (ADM)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ardent Mills
- 18.4 Bay State Milling Company
- 18.5 Central Milling
- 18.6 General Mills
- 18.7 Giusto’s
- 18.8 Great River Organic Milling
- 18.9 Janie’s Mill
- 18.10 Doves Farm Foods
- 18.11 Kaizen Food Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

