
Market Overview:
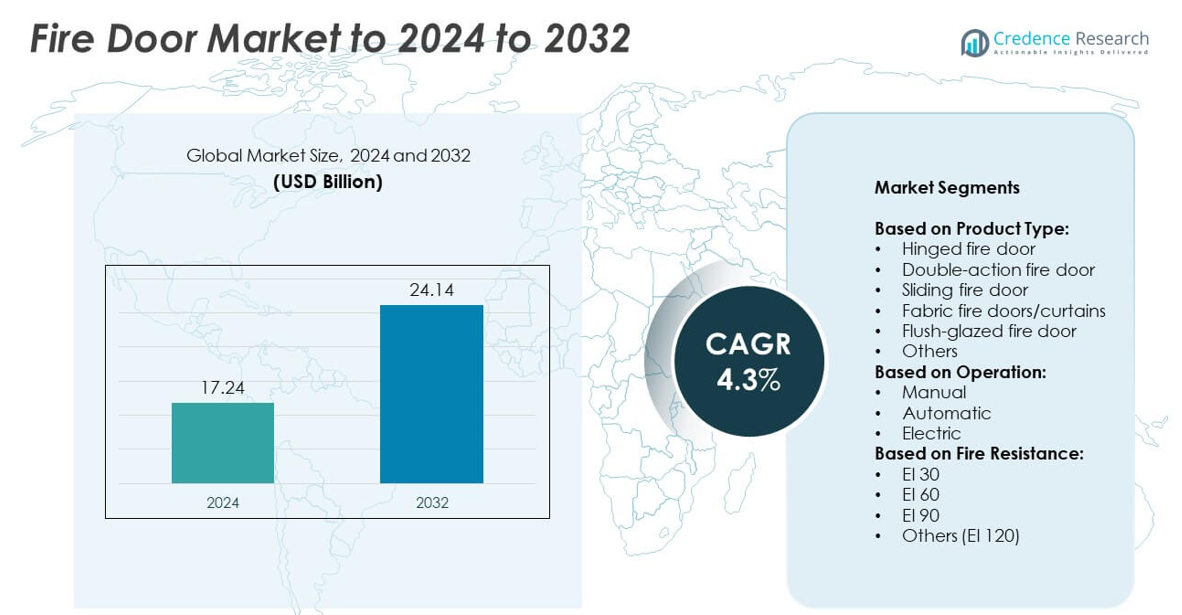
Fire Door Market size was valued USD 17.24 Billion in 2024 and is anticipated to reach USD 24.14 Billion by 2032, at a CAGR of 4.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fire Door Market Size 2024 | USD 17.24 billion |
| Fire Door Market, CAGR | 4.3% |
| Fire Door Market Size 2032 | USD 24.14 Billion |
The fire door market is shaped by prominent players such as ASSA ABLOY, Allegion plc, Hormann Beteiligungs, Republic Doors and Frames, and Agta Record, who focus on enhancing fire resistance ratings, sustainable materials, and automated solutions to meet stringent safety regulations. These companies emphasize product innovation and global expansion strategies to strengthen their market presence. North America emerged as the leading region in 2024, commanding 34% of the global share, driven by strict regulatory enforcement, high construction activity, and widespread adoption of fire-rated doors across commercial, residential, and industrial infrastructure projects.
Market Insights
- The fire door market was valued at USD 17.24 Billion in 2024 and is projected to reach USD 24.14 Billion by 2032, growing at a CAGR of 4.3%.
- Growth is fueled by strict fire safety regulations, rising construction of high-rise buildings, and increasing awareness of fire protection solutions in both developed and developing regions.
- Market trends highlight the adoption of automatic and smart fire doors with IoT integration, along with the rising use of eco-friendly and sustainable materials to meet green building standards.
- The competitive landscape is moderately fragmented, with global players investing in product innovation, mergers, and regional expansion to strengthen presence, while regional firms compete on cost and regulatory compliance.
- North America led with 34% share in 2024, followed by Europe at 28% and Asia Pacific at 24%, while Latin America held 8% and the Middle East & Africa accounted for 6%, showing balanced global demand.
Market Segmentation Analysis:
By Product Type
The hinged fire door segment dominated the fire door market in 2024 with a share of 41%. These doors are widely adopted across commercial and residential buildings due to their durability, easy installation, and compliance with stringent fire safety codes. Their reliability in compartmentalizing fire and smoke, along with lower maintenance requirements, makes them the preferred option. Demand is further supported by government regulations mandating fire-rated solutions in high-rise and institutional facilities. Sliding fire doors and fire curtains are gaining ground in industrial and large-space applications, but hinged doors remain the leading sub-segment.
- For instance, Teckentrup supplied almost 2,000 steel doors for the London Elizabeth Line project across multiple stations, including Whitechapel and Liverpool Street. The doors covered areas like platforms, tracks, and station bridges, demonstrating large-scale deployment.
By Operation
Manual fire doors held the largest share of 55% in 2024, reflecting their extensive use in residential and small commercial structures. Their cost-effectiveness, simple design, and low maintenance requirements drive widespread preference. These doors are particularly suitable in retrofit projects and settings where automated systems are not economically viable. However, the automatic segment is expanding rapidly in airports, malls, and hospitals due to enhanced safety, accessibility, and integration with building management systems. Despite this growth, manual fire doors remain the dominant segment, supported by affordability and regulatory compliance in mainstream construction.
- For instance, Allegion (Briton) hinges were fire-tested on a single-leaf 120 kg steel door, confirming manual door suitability for heavy, fire-rated assemblies.
By Fire Resistance
The EI 60 segment accounted for the highest share of 38% in 2024, positioning it as the dominant fire resistance rating in the market. EI 60 doors provide up to 60 minutes of fire containment, making them the standard requirement in commercial and institutional buildings. Their balance between safety, cost, and compliance with international standards has driven widespread adoption. Increasing installation in office spaces, hospitals, and public facilities continues to strengthen this category. While EI 30 doors are common in residential use and EI 90 in critical infrastructure, EI 60 remains the preferred industry benchmark.
Key Growth Drivers
Stringent Fire Safety Regulations
Regulatory compliance is the primary growth driver of the fire door market. Governments worldwide have enforced strict fire safety standards for commercial, residential, and industrial buildings. Building codes such as the International Building Code (IBC) and EN standards in Europe mandate the installation of fire-rated doors in critical infrastructure. This legal obligation fuels consistent demand across sectors. The growing emphasis on occupant safety, coupled with insurance requirements for fire protection, further strengthens market growth, making regulatory enforcement the most influential driver.
- For instance, Intertek performs field labeling and inspection for fire doors, applying certification on door assemblies annually to enforce compliance under NFPA 80.
Urbanization and Infrastructure Development
Rapid urbanization and increasing construction of high-rise buildings significantly boost the fire door market. Large-scale infrastructure projects in emerging economies demand enhanced fire protection systems to meet modern safety benchmarks. Growing investments in residential complexes, shopping malls, airports, and hospitals have raised the need for reliable fire containment solutions. Hinged and automatic fire doors are increasingly installed to meet the safety requirements of dense urban structures. The expanding global construction industry ensures a steady pipeline of demand for fire doors in both new projects and retrofits.
- For instance, UL Solutions certifies fire door assemblies at the manufacturing level based on performance standards such as UL 10B and UL 10C. These certifications help ensure the products can meet the requirements of building codes like NFPA and the IBC. While NFPA 80 mandates that the installed fire door assemblies undergo an inspection and testing at least annually, this is a separate requirement from the initial product certification and is typically performed by qualified inspection services, not a new UL certification each year.
Rising Awareness of Fire Safety
Growing public awareness about fire safety is driving adoption beyond regulatory needs. Educational campaigns, workplace training, and increased media coverage of fire incidents highlight the importance of fire prevention systems. Consumers and businesses are now more proactive in investing in certified fire doors to protect lives and assets. Demand is particularly strong in healthcare facilities, schools, and manufacturing plants where risk is higher. This shift from compliance-driven to safety-conscious buying behavior has emerged as a critical driver, pushing manufacturers to develop innovative and high-performance fire door solutions.
Key Trends and Opportunities
Smart and Automated Fire Doors
The adoption of smart fire doors integrated with IoT and automated systems is a growing trend. Automatic fire doors with sensors, remote monitoring, and integration with building management systems enhance operational safety and convenience. These doors are particularly valuable in airports, hospitals, and data centers where quick, seamless fire containment is essential. Manufacturers are increasingly developing products with advanced access control, smoke detection, and emergency response features. This technological innovation presents significant opportunities for premium product adoption and is shaping the future of the fire door industry.
- For instance, FAAC’s A952 swing operator is TÜV-certified for emergency exits and EN 16005 compliant. It has been spring-tested for over 1,000,000 cycles, and the unit also supports remote connectivity through Simply Connect.
Sustainable and Innovative Materials
The industry is witnessing a strong shift toward eco-friendly and innovative fire door materials. Manufacturers are using recyclable metals, low-VOC coatings, and composite cores to comply with green building standards. Rising adoption of LEED-certified projects and sustainable construction practices has accelerated demand for environmentally responsible fire doors. Lightweight yet high-performance designs are also emerging to support architectural flexibility. These advancements present a key opportunity for companies to differentiate in competitive markets while aligning with global sustainability goals and expanding their reach in eco-conscious construction projects.
- For instance, Halspan’s Prima Plus FD60 door blank is 54 mm thick and FSC-certified. Halspan cores are listed for fire resistance ratings from 20 to 120 minutes across product families.
Key Challenges
High Installation and Maintenance Costs
The high cost of installation and maintenance continues to limit fire door adoption in cost-sensitive markets. Premium fire doors with advanced fire ratings and automation features often involve significant upfront investment. Maintenance and compliance inspections add recurring expenses, which are burdensome for small enterprises and residential buyers. These financial constraints can delay or restrict fire door adoption in developing regions. Balancing cost-effectiveness with performance remains a key challenge for manufacturers aiming to expand penetration across diverse income segments.
Low Awareness in Developing Markets
Limited awareness of fire safety standards and benefits poses a challenge in emerging economies. Many residential builders and small businesses prioritize cost over safety, leading to inadequate installation of fire-rated doors. The absence of strict enforcement of fire safety codes further reduces adoption rates in these regions. This lack of awareness not only increases fire risks but also constrains market potential. Companies face the challenge of investing in education and awareness campaigns to drive adoption and establish compliance in less-regulated markets.
Regional Analysis
North America
North America held the largest share of 34% in the fire door market in 2024. Strong enforcement of fire safety regulations by the National Fire Protection Association (NFPA) and the International Building Code drives widespread adoption across commercial, industrial, and residential buildings. High construction activity in the U.S. and Canada, combined with renovation of aging infrastructure, continues to boost demand. Growing use of automatic and smart fire doors in airports, hospitals, and high-rise buildings further supports market expansion. The region benefits from established manufacturers and early adoption of advanced safety technologies.
Europe
Europe accounted for 28% of the fire door market in 2024, supported by stringent fire safety standards such as EN 1634 and widespread compliance across industries. High adoption rates in Germany, the UK, and France are driven by regulatory enforcement, especially in institutional and public infrastructure. The rising focus on sustainable and recyclable materials in fire doors further strengthens demand, aligning with the EU Green Deal objectives. Increasing renovation of historical structures to meet modern safety requirements also contributes to market growth, with strong demand from both commercial and residential segments.
Asia Pacific
Asia Pacific captured 24% of the global fire door market in 2024, driven by rapid urbanization and infrastructure development. Countries such as China, India, and Japan are witnessing significant demand for fire-rated solutions in high-rise buildings, airports, and shopping complexes. Growing enforcement of local building codes and rising awareness of fire safety in densely populated cities support market expansion. The region is also benefiting from large-scale government investments in smart cities and public infrastructure projects. Strong growth potential exists due to increasing adoption of both hinged and automatic fire doors in new developments.
Latin America
Latin America represented 8% of the fire door market in 2024, with growth concentrated in Brazil, Mexico, and Argentina. Rising construction activities in commercial spaces such as shopping malls, hotels, and offices have increased fire safety product demand. However, limited enforcement of fire safety regulations in some countries restrains faster adoption. Cost-sensitive buyers often prioritize affordability, boosting demand for manual fire doors. Still, growing investments in urban infrastructure and rising awareness of workplace safety are expected to create opportunities for expansion, particularly in modern high-rise buildings and large public facilities.
Middle East and Africa
The Middle East and Africa accounted for 6% of the fire door market in 2024. Market growth is supported by large infrastructure and commercial projects in countries such as the UAE, Saudi Arabia, and South Africa. Rising investments in airports, hotels, and healthcare facilities are increasing the demand for fire-rated doors. However, adoption remains uneven due to varying regulatory frameworks across the region. Growing emphasis on fire safety in high-density developments and ongoing urban expansion are expected to support future growth, with demand shifting toward automatic and high-resistance fire door solutions.
Market Segmentations:
By Product Type:
- Hinged fire door
- Double-action fire door
- Sliding fire door
- Fabric fire doors/curtains
- Flush-glazed fire door
- Others
By Operation:
- Manual
- Automatic
- Electric
By Fire Resistance:
- EI 30
- EI 60
- EI 90
- Others (EI 120)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The competitive landscape of the fire door market is shaped by established global and regional players such as Nihon Funen, Republic Doors and Frames, Esserford Joinery Works, Taotao Group, Vista Panels, Hormann Beteiligungs, Chase Doors, Rapp Bomek, China Buyang, Fusim Group, UK Fire Doors, Allegion plc, Mesker Openings Group, Agta Record, National Firefighting Manufacturing, and ASSA ABLOY. These companies compete on factors such as product innovation, fire resistance ratings, material quality, and compliance with international safety standards. The market is increasingly driven by rising demand for sustainable, smart, and automated fire door solutions integrated with advanced safety systems. Players are focusing on expanding their global reach through mergers, partnerships, and distribution networks to strengthen market presence. Investment in research and development remains critical to meet evolving regulatory requirements and customer expectations. The competition is further intensified by growing emphasis on eco-friendly materials and advanced fire-rated technologies across all regions.
Key Player Analysis
- Nihon Funen
- Republic Doors and Frames
- Esserford Joinery Works
- Taotao Group
- Vista Panels
- Hormann Beteiligungs
- Chase Doors
- Rapp Bomek
- China Buyang
- Fusim Group
- UK Fire Doors
- Allegion plc
- Mesker Openings Group
- Agta Record
- National Firefighting Manufacturing
- ASSA ABLOY
Recent Developments
- In 2025, ASSA ABLOY Acquired Door System, a Danish firm specializing in high-performance doors, including fire-rated products, in April.
- In 2025, Allegion plc Continued to offer comprehensive door and security solutions, including fire-rated hardware, to both domestic and international markets.
- In 2024, Hörmann (including Shakti Hörmann) Began operations at its new Jaipur facility in March (for wooden doors) and July (for steel doors).
Report Coverage
The research report offers an in-depth analysis based on Product Type, Operation, Fire Resistance and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The fire door market will grow steadily with stronger global fire safety regulations.
- Rising construction of high-rise buildings will boost demand for certified fire doors.
- Automatic and smart fire doors will see wider adoption in commercial projects.
- Sustainable and recyclable fire door materials will gain preference in green buildings.
- Asia Pacific will emerge as the fastest-growing region due to rapid urbanization.
- Manual fire doors will continue to dominate in cost-sensitive residential markets.
- Hospitals, airports, and data centers will drive adoption of advanced fire-rated doors.
- EI 60 fire doors will remain the standard rating across most applications.
- Renovation of older infrastructure will create opportunities for fire door retrofitting.
- Growing awareness campaigns will encourage wider fire safety compliance in developing regions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Fire Door Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fire Door Market projected to grow between 2025 and 2032?
Which Fire Door Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Fire Door Market?
Who are the leading companies in the Fire Door Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fire Door Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fire Door Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 17.24 Billion → 2032: USD 24.14 Billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fire Door Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fire Door Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fire Door Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fire Door Market Drivers
- 3.3 Fire Door Market Restraints & Challenges
- 3.4 Fire Door Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fire Door Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fire Door Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fire Door category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fire Door Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Fire Door Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Fire Door. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fire Door Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fire Door Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Fire Door Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fire Door (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Fire Door
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fire Door Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Fire Door Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fire Door Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fire Door Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fire Door Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fire Door Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fire Door Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fire Door Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
