
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| General Display Technologies Market Size 2024 | USD 165005 million |
| General Display Technologies Market, CAGR | 3.7 % |
| General Display Technologies Market Size 2032 | USD 220661 million |
Market Overview:
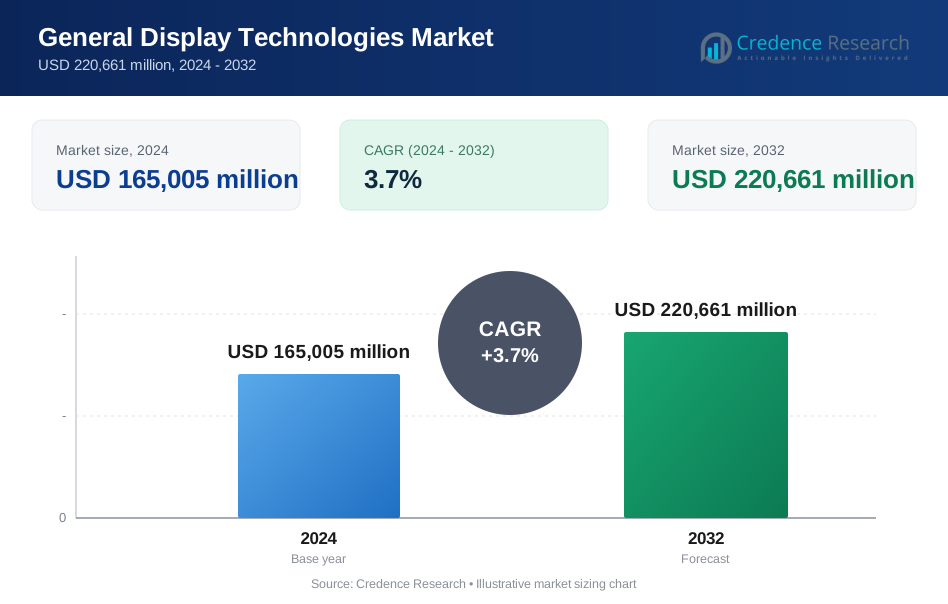
The General Display Technologies Market is projected to grow from USD 165005 million in 2024 to an estimated USD 220661 million by 2032, with a compound annual growth rate (CAGR) of 3.7 % from 2024 to 2032.
Key market drivers for the general display technologies market include the widespread adoption of smart consumer electronics such as smartphones, tablets, televisions, and wearables, which increasingly rely on advanced display solutions to deliver superior visual experiences. Companies are heavily investing in research and development to innovate in areas such as flexible and foldable displays, high-resolution OLED, QLED, and microLED panels that offer improved performance and efficiency. The rising demand for digital signage, driven by the growth of smart cities and public information systems, is another major contributor to market expansion. Display technologies are also gaining traction in the automotive industry, particularly in heads-up displays (HUDs), digital dashboards, and infotainment systems, enhancing safety, navigation, and user engagement. Additionally, regulatory measures emphasizing energy efficiency and environmental sustainability are pushing manufacturers to develop eco-friendly, low-power display solutions that cater to a wide range of applications.
From a regional perspective, the Asia-Pacific region remains the dominant market for general display technologies, largely due to its robust manufacturing ecosystem, strong government support, and growing demand for display solutions in electronics, automotive, and retail sectors. Countries such as China, Japan, and South Korea lead in display panel production, driving market growth through innovation and economies of scale. North America closely follows, fueled by a high adoption rate of advanced technologies, a well-established consumer electronics market, and ongoing innovations in display technologies, including AR/VR applications. Europe demonstrates steady growth, supported by a focus on energy-efficient and high-definition displays, particularly in automotive and industrial sectors. Meanwhile, emerging markets in Latin America and the Middle East & Africa are poised for expansion due to increasing digital transformation initiatives, rising disposable incomes, and the proliferation of smart devices and public digital communication systems.
Market Drivers:
Increasing Demand for Smart Consumer Electronics:
The rapid adoption of smart consumer electronics, including smartphones, tablets, smartwatches, and smart TVs, is a key driver of growth in the general display technologies market. Consumers increasingly demand high-quality visual experiences, leading to the widespread adoption of advanced display technologies such as OLED, QLED, and microLED. These technologies offer superior resolution, vibrant colors, and enhanced energy efficiency compared to traditional displays, fueling their adoption across a range of devices. For instance, Samsung's Galaxy S24 Ultra demonstrates cutting-edge display technology by featuring a 6.8-inch Dynamic AMOLED 2X display with a 120Hz adaptive refresh rate and peak brightness of 2,600 nits, showcasing the industry's push for superior visual experiences. As technology continues to evolve, manufacturers focus on developing displays with improved performance, including faster refresh rates, better color accuracy, and thinner, more flexible form factors. This trend reflects changing consumer preferences and the shift toward immersive, visually engaging content, significantly impacting the market trajectory.
Innovations in Display Technologies:
The push for innovation within display technologies has been relentless, with companies investing heavily in research and development to stay competitive. Emerging trends such as flexible and foldable displays, microLED technology, and transparent displays are reshaping how display solutions are designed and utilized. Foldable displays have already been introduced in smartphones and tablets, offering greater flexibility and portability. Meanwhile, microLED displays are gaining traction due to their superior brightness, energy efficiency, and longer lifespan compared to traditional LCD and OLED displays. These innovations create new possibilities for applications in diverse industries, ranging from automotive and healthcare to retail and beyond, thereby expanding market growth opportunities.
Growing Use of Digital Signage and Advertising:
The increasing use of digital signage for advertising, communication, and public information is another significant driver of the general display technologies market. As businesses seek to engage with customers in more impactful and dynamic ways, digital displays have become integral for marketing campaigns, events, and branding initiatives. The growth of smart cities and public infrastructure projects has led to a surge in demand for display technologies used in digital billboards, interactive kiosks, and wayfinding solutions. These displays provide real-time content delivery and increased interactivity, making them an attractive option for both businesses and consumers. As digital transformation continues across sectors, the need for high-resolution, energy-efficient, and visually compelling displays is anticipated to grow further.
Expansion of Automotive Display Applications:
The automotive sector has become a key growth area for the display technologies market. Display systems are now extensively used in automotive applications, such as heads-up displays (HUDs), digital instrument clusters, infotainment systems, and rear-seat entertainment. These displays enhance vehicle safety, driver awareness, and overall user experience, contributing to their growing adoption. Automotive displays increasingly incorporate advanced features such as augmented reality (AR) overlays, touch controls, and customizable digital interfaces. These vehicles require sophisticated display systems to provide crucial information about battery status, range, energy consumption, and charging station locations, driving innovation in automotive display technologies. The ongoing transition to electric and autonomous vehicles also accelerates demand for sophisticated display systems that provide real-time data visualization and interactive user experiences. This sector's expansion is expected to drive significant innovation and further enhance the role of display technologies in automotive design and functionality. For instance, in 2023, nearly 14 million new electric cars were registered globally, bringing the total number of Electric Vehicles (EVs) to 40 million.
Market Trends:
Growing Demand for Advanced Display Solutions:
The general display technologies market has experienced significant growth due to increased demand for advanced display solutions across various sectors, such as consumer electronics, automotive, healthcare, and retail. The popularity of smartphones, tablets, and other personal electronic devices has fueled the demand for high-resolution, energy-efficient displays. Innovations like OLED (Organic Light-Emitting Diode) and MicroLED technologies have emerged as key drivers, offering superior image quality, vibrant colors, and better energy efficiency than traditional LCDs. Flexible and foldable displays are also gaining traction, reshaping mobile and wearable devices. This market expansion is supported by continuous research and development efforts aimed at improving display performance and reducing costs.
Demand for Large-Format and High-Resolution Displays:
The market is witnessing a growing demand for large-format displays, driven by sectors such as advertising, education, and corporate environments. Interactive and immersive displays, including digital whiteboards and touch-enabled screens, are revolutionizing the way businesses communicate and collaborate. Digital signage is becoming increasingly common in the retail sector, leveraging advanced display technologies to engage customers and enhance their shopping experience. For instance, the use of 4K and 8K displays in digital signage has increased significantly, with companies like LG and Sony leading the way in providing high-resolution solutions. As a result, manufacturers are focusing on displays with higher pixel density, wider color gamut, and improved brightness.
Emphasis on Sustainability and Eco-Friendly Displays:
Sustainability is emerging as a critical factor in the general display technologies market, as manufacturers and consumers prioritize reducing environmental impacts. Companies are focusing on eco-friendly materials and manufacturing processes to decrease their carbon footprints. For example, LG Display has committed to reducing its carbon emissions by 50% by 2030 through the use of eco-friendly materials and energy-efficient manufacturing processes. There is a growing trend toward displays with lower power consumption, longer lifespans, and minimal use of hazardous materials. This movement aligns with increasing regulatory demands and consumer preferences for environmentally conscious products. Additionally, the adoption of circular economy principles is gaining momentum, emphasizing recyclable materials and repairable designs to minimize electronic waste.
Competitive Landscape and Regional Dynamics:
The competitive landscape in the display technologies market remains dynamic, with companies engaging in mergers, acquisitions, and partnerships to strengthen their market presence and technological capabilities. Collaborations between semiconductor manufacturers and display technology firms are accelerating the development of next-generation displays. The Asia-Pacific region, led by countries such as China, South Korea, and Japan, dominates the market due to its strong manufacturing base and high demand. Meanwhile, North America and Europe are also seeing substantial growth driven by increasing investments in advanced display solutions and innovation. To remain competitive, companies are focusing on cutting-edge technologies tailored to meet emerging applications and consumer demands.
Market Restraints and Challenges:
High Production Costs and Complex Manufacturing Processes:
One of the primary restraints in the general display technologies market is the high production cost associated with advanced display technologies such as OLED and MicroLED. These displays require complex manufacturing processes and expensive raw materials, which drive up production costs. The intricate processes involved in achieving high-quality, high-resolution displays often lead to lower production yields, impacting profitability for manufacturers. This cost barrier can slow the adoption of these technologies, particularly in price-sensitive markets, limiting their accessibility to broader consumer segments.
Rapid Technological Obsolescence:
The pace of technological advancements in the display industry presents a significant challenge. Display technologies quickly become outdated as newer, more advanced solutions are introduced to the market. This rapid obsolescence creates pressure on manufacturers to continuously invest in research and development to stay competitive, which can strain resources. For consumers, the fast-paced changes in technology can lead to shorter product lifecycles and reluctance to invest in premium displays that may soon be replaced by next-generation options.
Environmental and Regulatory Challenges:
The display industry faces mounting pressure to reduce its environmental impact. Regulatory bodies are increasingly enforcing stringent standards on hazardous materials, energy efficiency, and electronic waste disposal. Compliance with these regulations can increase operational costs for manufacturers, particularly as they transition to eco-friendly materials and processes. The challenge lies in balancing regulatory compliance with the need to maintain cost-effective production while meeting consumer demand for environmentally conscious products.
Supply Chain Disruptions:
The global display technologies market is highly dependent on complex supply chains, making it vulnerable to disruptions. Factors such as geopolitical tensions, trade restrictions, and component shortages can significantly impact production timelines and increase costs. Supply chain disruptions have a cascading effect, affecting manufacturers' ability to meet market demand and maintain stable pricing, ultimately posing a challenge to market growth.
Market Segmentation Analysis:
The general display technologies market is segmented comprehensively across various dimensions to better understand market dynamics, trends, and growth opportunities.
By Technology, key segments include OLED, LED, Micro-LED, Direct-View LED, LCD, and other emerging display technologies. OLED and Micro-LED technologies are gaining momentum due to their superior image quality, flexibility, and energy efficiency. LED and Direct-View LED displays maintain a strong presence, especially in applications requiring large-format displays and digital signage. Meanwhile, LCD continues to be widely used due to its cost-effectiveness and broad adoption in consumer electronics.
By Application, the market spans multiple end-use categories, including smartphones, television sets, PC monitors and laptops, digital signage/large-format displays, automotive displays, tablets, smart wearables, and others. The increasing demand for high-quality displays in smartphones and smart wearables is a major growth driver. Digital signage and large-format displays are revolutionizing advertising, retail, and corporate communication, while automotive displays enhance vehicle functionality and safety.
By End Use, the market serves diverse sectors such as automotive, healthcare, defense and aerospace, education, sports and entertainment, consumer electronics, retail and hospitality, banking, financial services and insurance (BFSI), and transportation and industrial applications. The consumer and automotive sectors remain dominant, driven by the need for cutting-edge displays and enhanced user experiences. Healthcare and defense are also key contributors, with high-precision displays critical for medical imaging and mission-critical operations.
Segmentation:
By Technology
- OLED
- LED
- Micro-LED
- Direct-View LED
- LCD
- Others
By Application
- Smartphones
- Television Sets
- PC Monitors & Laptops
- Digital Signage/Large Format Displays
- Automotive Displays
- Tablets
- Smart Wearables
- Others
By End Use
- Automotive
- Healthcare
- Defence and Aerospace
- Education
- Sports and Entertainment
- Consumer
- Retail and Hospitality
- Banking
- Financial Services and Insurance
- Transportation and Industrial
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The regional analysis of the general display technologies market reveals diverse growth patterns, driven by varying demand, technological capabilities, and market dynamics across key geographic regions.
The Asia-Pacific region holds the largest market share, accounting for over 40% of the global market. This dominance is attributed to a strong manufacturing base in countries such as China, South Korea, and Japan. Major display panel manufacturers, including Samsung Display, LG Display, and BOE Technology, are headquartered in this region, ensuring a steady supply of advanced display technologies. The region’s thriving consumer electronics market, combined with rising demand for OLED, LCD, and MicroLED displays in smartphones, televisions, and automotive applications, further fuels growth.
North America represents the second-largest market share, contributing approximately 25% of the global market. The region benefits from a robust consumer electronics market, high adoption of cutting-edge display technologies, and increasing demand for large-format displays in retail, advertising, and corporate settings. The presence of leading tech firms and their continued investments in R&D further support the development of advanced display technologies. North America's automotive industry also drives demand for high-resolution displays, including heads-up displays and advanced infotainment systems.
In Europe, the market accounts for around 20% of global market share. The region’s growth is fueled by the automotive, retail, and healthcare sectors. European countries, such as Germany, France, and the United Kingdom, are witnessing increasing demand for automotive displays, driven by a shift towards electric vehicles and enhanced in-car display systems. The adoption of digital signage in retail and public spaces continues to rise, while the healthcare sector leverages advanced display technologies for medical imaging and patient monitoring solutions.
Latin America and the Middle East & Africa (MEA) collectively hold a smaller share of the market, contributing approximately 15%. In Latin America, increasing urbanization and the growing popularity of digital advertising are driving demand for digital signage and large-format displays. The MEA region’s market growth is fueled by expanding infrastructure projects, increasing adoption of smart technologies, and a rising demand for consumer electronics. Both regions face challenges such as economic fluctuations and limited local manufacturing capabilities, which can affect market growth.
Key Player Analysis:
- Advantech Co., Ltd (Taiwan)
- AU Optronics Corp. (Taiwan)
- (Belgium)
- BOE Technology Group Co., Ltd. (China)
- Chi Mei Corporation. (Taiwan)
- Chunghwa Picture Tubes, LTD. (Taiwan)
- FUJITSU (Japan)
- HannStar Display Corporation (Taiwan)
- Innolux Corporation (Taiwan)
- LG Display Co., Ltd (South Korea)
- Mitsubishi Electric Corporation (Japan)
- Panasonic Corporation (Japan)
- SAMSUNG (South Korea)
- Schneider Electric (France)
- SHARP CORPORATION (Japan)
- Siemens (Germany)
- SONY INDIA. (India)
Competitive Analysis:
The competitive landscape of the general display technologies market is characterized by intense competition among key players striving for technological leadership and market dominance. Major companies such as Samsung Display, LG Display, BOE Technology, AU Optronics, and Japan Display Inc. lead the market with innovations in OLED, MicroLED, and high-resolution LCD technologies. These players focus on continuous R&D investment, strategic collaborations, and new product launches to enhance display performance, reduce costs, and meet evolving consumer demands. Emerging players are also gaining traction by offering niche solutions and targeting specific applications such as automotive displays and digital signage. Strategic partnerships between display manufacturers, semiconductor firms, and software providers further intensify competition and foster technological advancements. The competitive environment is shaped by rapid technological changes, price competition, and evolving customer expectations, prompting market leaders to differentiate through innovation and customization.
Recent Developments:
- In January 2023, Samsung Electronics Co., Ltd. introduced the world’s first touch-integrated OLED display. This innovation replaces traditional plastic touch film with touch-integrated panels, marking a significant step forward in display technology. The new On-Cell Touch AMOLED (OCTA) technology integrates the touch sensor directly into the panel itself, eliminating the need for separate touch screen layers. This integration enhances display thinness and responsiveness while reducing manufacturing complexity and costs.
- In December 2023, LG Display Co., Ltd. unveiled a 97-inch OLED display panel, offering users an immersive and enhanced cinematic viewing experience thanks to its substantial size. Additionally, the company introduced a 77-inch 8K OLED panel that delivers exceptional ultra-high-resolution images. This display achieves the highest level of resolution by managing 33 million self-emissive pixels, resulting in a stunning level of detail and image clarity that sets a new benchmark in high-end display technology.
Market Concentration & Characteristics:
The general display technologies market is moderately concentrated, with a few dominant players capturing a significant market share due to their technological expertise, strong manufacturing capabilities, and robust global distribution networks. Key companies such as Samsung Display, LG Display, BOE Technology, and Japan Display Inc. lead innovation and production in advanced display segments, including OLED and MicroLED technologies. These players benefit from economies of scale, extensive research and development activities, and strategic partnerships that enable them to stay competitive. Market characteristics are defined by rapid technological advancements, high competition, and a focus on innovation to meet evolving consumer demands. Companies continuously strive to improve display resolution, energy efficiency, flexibility, and overall performance. The market also sees a strong trend towards sustainability, with manufacturers focusing on eco-friendly materials and production processes. As technology evolves, niche players are emerging to cater to specialized applications such as automotive displays and digital signage.
Report Coverage:
The research report offers an in-depth analysis based on By Technology, By Application and By End Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing consumer demand for allergen-free and sensitive skin-friendly skincare products drives market expansion.
- Rising awareness of coconut allergies and intolerances leads consumers to seek coconut-free alternatives.
- Growth in natural and organic skincare preferences boosts the appeal of coconut-free formulations.
- Innovation in plant-based and synthetic alternatives to coconut-derived ingredients supports market diversification.
- Rising e-commerce platforms facilitate accessibility and visibility of niche coconut-free brands globally.
- Influencer and social media-driven marketing raises consumer awareness of coconut-free skincare benefits.
- Expanding vegan and cruelty-free certification trends align with the market's growth trajectory.
- Increasing regulatory scrutiny on allergens and product labeling creates opportunities for compliant brands.
- Growing demand for hypoallergenic skincare solutions encourages market players to innovate safer formulations.
- Asia-Pacific and North America are expected to lead growth due to heightened consumer awareness and spending power.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the general display technologies market?
What are the key market drivers for this growth?
Which region dominates the market?
What are the main challenges facing the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 General Display Technologies Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global General Display Technologies Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 165,005 million → 2032: USD 220,661 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 General Display Technologies Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. General Display Technologies Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 General Display Technologies Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 General Display Technologies Market Drivers
- 3.3 General Display Technologies Market Restraints & Challenges
- 3.4 General Display Technologies Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 General Display Technologies Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 General Display Technologies Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, General Display Technologies category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 General Display Technologies Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. General Display Technologies Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the General Display Technologies market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 General Display Technologies Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 General Display Technologies Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 General Display Technologies Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in General Display Technologies (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New General Display Technologies Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global General Display Technologies Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America General Display Technologies Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe General Display Technologies Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific General Display Technologies Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America General Display Technologies Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East General Display Technologies Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa General Display Technologies Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. General Display Technologies Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
