
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Gluten-Free Prepared Food Market Size 2024 | USD 5,882.1 Million |
| Gluten-Free Prepared Food Market, CAGR | 7.5% |
| Gluten-Free Prepared Food Market Size 2032 | USD 10,490.59 Million |
Market Overview
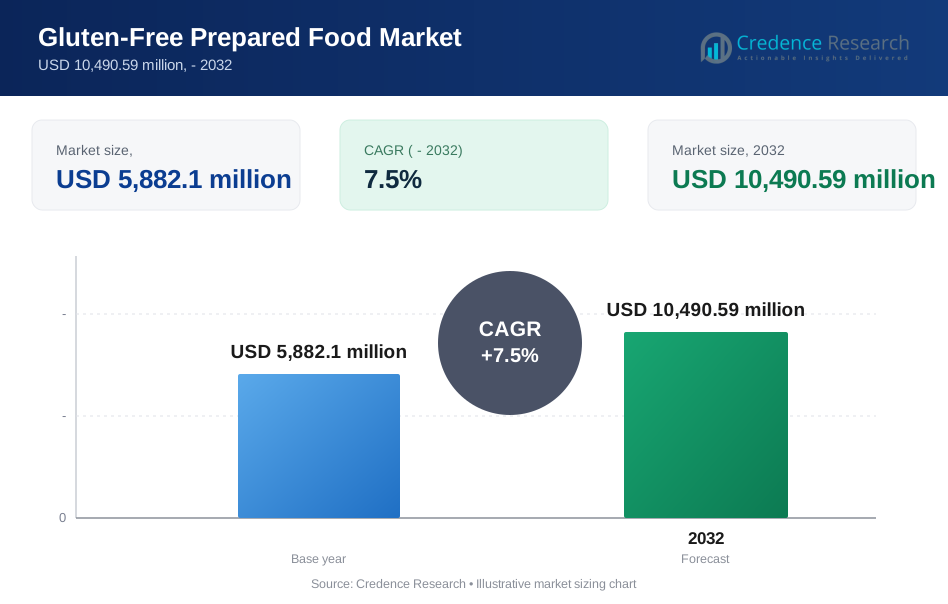
The Gluten-Free Prepared Food Market is projected to grow from USD 5,882.1 million in 2024 to USD 10,490.59 million by 2032, with a compound annual growth rate (CAGR) of 7.5%.
The gluten-free prepared food market is driven by the rising prevalence of coeliac disease and gluten intolerance, leading consumers to seek healthier and allergen-free food options. Increasing awareness of gluten-related health issues and the growing trend of adopting gluten-free diets, even among non-coeliac individuals, further fuel market demand. The convenience of ready-to-eat gluten-free meals caters to the busy lifestyles of modern consumers, while manufacturers are continuously innovating to enhance taste, texture, and nutritional value. In addition, the expanding availability of gluten-free products in mainstream retail channels and the influence of social media and wellness trends have amplified consumer interest. These factors, combined with increasing global health consciousness, are key drivers in the market’s growth.
The gluten-free prepared food market is expanding across various regions, with North America leading the market, holding a significant share of approximately 45% in 2024. Europe follows closely, accounting for around 30% of the market, driven by strong demand in countries like the UK, Germany, and Italy. The Asia Pacific region, with a market share of 15%, is experiencing rapid growth due to increasing health awareness and urbanisation. Meanwhile, regions like Latin America, the Middle East, and Africa make up the remaining 10%, showing steady growth potential. Key players such as Hero AG, Raisio PLC, Barilla G.E.R. Fratelli S.P.A., Kellogg’s Company, and General Mills are focusing on expanding their presence in these regions, introducing innovative gluten-free products to cater to diverse consumer needs and regional preferences.
Market Insights
- The gluten-free prepared food market is projected to grow from USD 5,882.1 million in 2024 to USD 10,490.59 million by 2032, with a CAGR of 7.5%.
- The increasing prevalence of coeliac disease and gluten intolerance is driving demand for gluten-free options.
- Growing health and wellness awareness, with more consumers adopting gluten-free diets, fuels market growth.
- Manufacturers are heavily investing in innovation to improve the taste, texture, and nutritional value of gluten-free products.
- The convenience and increased accessibility of gluten-free products, especially through e-commerce, are enhancing market reach.
- North America leads the market, holding 45% of the market share in 2024, followed by Europe with 30%.
- The Asia Pacific region is experiencing rapid growth, holding a 15% market share in 2024, while Latin America and the Middle East contribute 10%.
Market Drivers
Rising Prevalence of Coeliac Disease and Gluten Intolerance
The increasing prevalence of coeliac disease and gluten intolerance is a significant driver in the gluten-free prepared food market. With more individuals being diagnosed with these conditions, there is a growing demand for gluten-free options to accommodate their dietary needs. For instance, companies like Schär and Bob's Red Mill are developing a wide range of gluten-free products to cater to this growing consumer base. As awareness of the health risks associated with gluten for these individuals rises, consumers are turning to gluten-free products that offer safe alternatives, boosting market growth.
Growing Health and Wellness Awareness
Health-conscious consumers are increasingly adopting gluten-free diets, even without medical conditions like coeliac disease or gluten intolerance. The perception of gluten-free products as healthier and more natural alternatives has attracted a broader audience, including those looking to reduce inflammation, improve digestion, and enhance overall well-being. This trend has led to the development of diverse gluten-free prepared foods, catering to a wide range of health and wellness needs, thereby driving demand in the market.
Increased Innovation in Gluten-Free Product Development
Manufacturers are investing heavily in innovation to improve the taste, texture, and nutritional value of gluten-free prepared foods. Advanced food technologies and ingredient formulations have enabled companies to create gluten-free products that closely resemble traditional options in flavour and quality. For instance, companies like General Mills and Enjoy Life Foods are focusing on innovative formulations to enhance the taste and texture of their gluten-free offerings. This focus on innovation has attracted more consumers, including those who previously avoided gluten-free products due to taste or texture concerns, thus contributing to the market’s expansion.
Convenience and Accessibility of Gluten-Free Products
The growing availability of gluten-free prepared foods in mainstream retail channels has made it easier for consumers to access these products. With the rise of e-commerce, gluten-free products are now widely available online, increasing their reach to a broader consumer base. Online platforms like Amazon and Thrive Market are expanding their gluten-free product offerings, making them accessible to more consumers. This enhanced convenience, combined with a variety of choices in gluten-free offerings, has significantly contributed to the growth of the market.
Market Trends
Increasing Demand for Nutritionally Balanced Gluten-Free Products:
Consumers are no longer satisfied with just gluten-free options; they are increasingly seeking nutritionally balanced products that provide essential vitamins, minerals, and protein. This trend has led manufacturers to enrich gluten-free prepared foods with added nutrients like fibre, antioxidants, and superfoods, ensuring these products not only cater to gluten-free diets but also offer overall health benefits. For instance, companies like Enjoy Life Foods and Bob's Red Mill are developing gluten-free products that include added nutrients to cater to health-conscious consumers. This shift towards healthier options is gaining momentum, driving innovation in the market.
Expansion of Plant-Based and Vegan Gluten-Free Offerings:
The rise of plant-based and vegan diets has merged with the gluten-free trend, resulting in an increased demand for products that address both dietary preferences. For example, brands like Amy's Kitchen and Daiya are launching gluten-free, plant-based products to cater to this growing market. This convergence of trends supports growth in both markets. Manufacturers are now developing gluten-free prepared foods that are also free from animal-based ingredients, creating a growing segment of products that appeal to both gluten-free consumers and the expanding base of plant-based eaters.
Focus on Clean Label and Organic Ingredients:
Consumers are paying closer attention to ingredient transparency, prompting a growing interest in clean-label and organic gluten-free products. Prepared foods that are free from artificial preservatives, additives, and processed ingredients are becoming more popular. Companies like Simple Mills and Nature's Path are producing clean-label, organic gluten-free products to align with consumer preferences. This trend has encouraged manufacturers to focus on developing gluten-free options with minimal ingredients, using organic and natural components to meet consumer demand for clean, wholesome foods.
Rise of Ready-to-Eat and On-the-Go Gluten-Free Meals:
With busy lifestyles driving the need for convenience, ready-to-eat and on-the-go gluten-free meals are becoming increasingly popular. Consumers are looking for quick, easy-to-prepare options that do not compromise on taste or nutrition. As a result, manufacturers are launching a variety of gluten-free frozen meals, snack bars, and portable options to meet this growing demand for convenience.
Market Challenges Analysis
High Production Costs and Pricing Challenges One of the significant challenges in the gluten-free prepared food market is the higher production costs associated with manufacturing gluten-free products. Sourcing certified gluten-free ingredients often comes at a premium, and the stringent production standards needed to avoid cross-contamination with gluten-based products add further costs. Additionally, specialised processing and testing contribute to the overall expense of producing gluten-free foods. As a result, gluten-free products are typically priced higher than their conventional counterparts, making them less accessible to price-sensitive consumers. The cost disparity can limit market growth, especially in regions with lower disposable incomes, where affordability is a key purchasing consideration. Manufacturers are continually seeking ways to reduce costs while maintaining quality to attract a broader customer base. Additionally, the pressure to maintain competitive pricing in an increasingly saturated market adds further complexity for companies trying to balance cost-efficiency and consumer expectations.
Taste and Texture Limitations Despite advancements in food technology, achieving taste and texture parity with traditional gluten-containing products remains a challenge for gluten-free prepared foods. Many consumers, particularly those not medically required to follow a gluten-free diet, find that gluten-free alternatives may lack the same taste and mouthfeel as their conventional counterparts. Gluten plays a crucial role in providing elasticity and structure to baked goods, and replicating these qualities with alternative ingredients can be difficult. This perceived difference in quality can deter consumers from adopting gluten-free products unless they are specifically required to do so for health reasons. Overcoming these sensory limitations while maintaining a clean label and nutritional profile continues to be a key challenge for manufacturers aiming to broaden their consumer base in the gluten-free prepared food market. Additionally, maintaining shelf life without compromising quality adds further complexity in product development.
Market Opportunities
The gluten-free prepared food market presents significant growth opportunities, driven by increasing consumer demand for healthier and specialised dietary options. As awareness of gluten intolerance and coeliac disease continues to rise, more individuals are adopting gluten-free diets, creating a larger target market for manufacturers. In addition, the expanding interest in gluten-free diets among health-conscious consumers, even without medical necessity, opens opportunities for product diversification. Manufacturers can capitalise on this trend by offering a wide variety of innovative, gluten-free products that combine convenience with nutritional benefits, including plant-based and organic options, to appeal to a broader audience.
The rise of e-commerce and direct-to-consumer channels offers another key opportunity for companies in the gluten-free prepared food market. As consumers increasingly turn to online platforms for grocery shopping, particularly for speciality products, companies can expand their reach and tap into a global customer base by optimising their online presence. Collaborating with health-focused retailers and developing strategic partnerships with influencers and health advocates can further enhance brand visibility and attract new customers. Additionally, as gluten-free diets gain traction in emerging markets, companies that focus on localising their product offerings and pricing strategies to meet regional demands can unlock untapped growth potential. Overall, the gluten-free prepared food market remains primed for expansion, with opportunities for innovation, market penetration, and global reach.
Market Segmentation Analysis:
By Product Type
The gluten-free prepared food market is segmented by product type, including baked goods, snacks, meals, and beverages. Baked goods, such as bread and cookies, represent a significant share due to their popularity among gluten-sensitive consumers. Ready-to-eat meals and snacks are also growing rapidly, driven by convenience-seeking customers looking for quick, gluten-free options.
By Source
The market is categorised by source, including rice, corn, quinoa, and others. Rice-based products dominate the market due to their wide use in gluten-free formulations, while quinoa and other superfoods are gaining attention for their nutritional benefits. This segmentation allows manufacturers to target health-conscious consumers seeking nutrient-dense gluten-free alternatives.
By Sales Channel
Sales channels for gluten-free prepared foods include supermarkets, health food stores, and online platforms. Supermarkets hold the largest share due to their extensive reach, while online sales are experiencing fast growth, driven by the increasing preference for convenient, direct-to-door shopping experiences, especially for speciality products.
Segments:
Based on Product Type
- Bakery and Confectionery
- Snacks and RTE Products
- Dairy Products
- Sauces and Dressings
- Meat and Meat Substitutes
- Others
Based on the source
- Plant-based
- Animal-based
Based on Sales Channel
- Hypermarket/Supermarket
- Convenience Store
- Speciality Store
- Pharmacies
- Online Retail
- Others
Based on the geography:
- North America
- S.
- Canada
- Mexico
- Europe
- Germany
- France
- K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America is the dominant region in the gluten-free prepared food market, accounting for a significant market share of 45% in 2024. This region is driven by high consumer awareness of gluten-related health issues, including coeliac disease and gluten sensitivity. The demand for gluten-free products is further supported by the growing health-conscious population, with both individuals with dietary restrictions and those seeking to adopt healthier lifestyles contributing to market growth. The United States is the largest consumer of gluten-free prepared foods, with a robust retail environment, including supermarkets, health food stores, and an expanding e-commerce sector. This market is expected to maintain its leadership due to continued innovation in gluten-free product offerings and a favourable regulatory environment supporting gluten-free labelling.
Europe
Europe holds the second-largest share of the gluten-free prepared food market, estimated at 30% in 2024. The European market is particularly driven by countries such as the United Kingdom, Germany, and Italy, where gluten-free diets are increasingly popular due to rising awareness about coeliac disease and gluten intolerance. The region has a strong focus on clean-label and organic gluten-free products, aligning with the growing demand for natural, minimally processed foods. Additionally, the rise of e-commerce and the expansion of gluten-free products in mainstream retail outlets have contributed to the market’s growth. Europe is expected to see steady growth in the coming years as manufacturers focus on product innovation and expanding their distribution networks.
Asia Pacific
The Asia-Pacific region is witnessing rapid growth in the gluten-free prepared food market, with an estimated market share of 15% in 2024. While the region has traditionally had a lower awareness of gluten-related issues, increasing globalisation, urbanisation, and rising health concerns are driving the demand for gluten-free products. Countries such as Japan, China, and India are seeing increasing adoption of gluten-free diets, especially in urban areas. Additionally, the rise of health-conscious young consumers in these markets is pushing manufacturers to innovate and cater to local preferences. The market in Asia Pacific is projected to expand significantly, with opportunities for growth in both established and emerging economies.
Rest of the World
The rest of the world, including regions such as Latin America, the Middle East, and Africa, represents a smaller share of the gluten-free prepared food market, estimated at 10% in 2024. However, these markets are beginning to see a shift in consumer behaviour, with growing interest in gluten-free products due to increasing health awareness and dietary changes. Latin America, in particular, is experiencing rising demand for gluten-free foods, driven by health trends and expanding retail infrastructure. While the market share is relatively small, it is expected to grow steadily as manufacturers increase awareness and access to gluten-free products in these regions.
Key Player Analysis
- Hero AG
- Raisio PLC
- Barilla G.E.R. Fratelli S.P.A.
- Enjoy Life Foods
- Kellogg’s Company
- Alara Wholefoods Ltd.
- ConAgra Brands Inc.
- The Kraft Heinz Company
- Prima Foods Ltd.
- General Mills
- Freedom Foods Group Limited
- The Hain Celestial Group Inc.
Competitive Analysis
The gluten-free prepared food market is highly competitive, with leading players like Hero AG, Raisio PLC, Barilla G.E.R Fratelli S.P.A, Enjoy Life Foods, Kellogg’s Company, Alara Wholefoods Ltd., ConAgra Brands Inc., The Kraft Heinz Company, Prima Foods Ltd., General Mills, Freedom Foods Group Limited, and The Hain Celestial Group Inc. These companies are actively innovating to cater to the growing demand for gluten-free options, with a focus on product diversification, clean labels, and enhanced nutritional profiles. Key strategies include expanding product lines to include gluten-free snacks, meals, and baked goods while improving taste and texture to match conventional offerings. For instance, General Mills and The Kraft Heinz Company are expanding their product lines to include gluten-free snacks, meals, and baked goods while improving taste and texture to match conventional offerings. Strategic partnerships, acquisitions, and increased distribution channels, especially through e-commerce platforms, are vital in strengthening their market presence. With rising consumer interest in health-conscious foods, these companies are investing in R&D to develop gluten-free solutions that align with broader dietary trends, such as plant-based and organic offerings.
Recent Developments
- In February 2024, GOODLES, a U.S.-based food manufacturer, introduced a line of gluten-free products, including gluten-free Cheddy Mac and gluten-free Vegan Be Heroes pasta.
- In December 2023, Oreo, a brand under Mondelez, expanded its product line with the launch of gluten-free golden cookies. These cookies come in two key flavours: chocolate soft snack cakes filled with peanut butter and peanut butter casters.
- In 2023, Nestlé introduced a new gluten-free range of ready-to-eat meals under its Lean Cuisine brand, catering to the growing demand for nutritious and convenient food options.
- In 2023, Kellogg’s expanded its gluten-free offerings by launching protein bars that feature superfoods such as chia seeds, flaxseeds, and almonds.
- In May 2023, London-based food and beverage company Crosta and Mollica unveiled a new gluten-free margherita pizza. Made entirely from wheat flour, it is an ideal option for those adhering to a coeliac-friendly diet.
Market Concentration & Characteristics
The gluten-free prepared food market exhibits a moderately concentrated structure, with a mix of well-established multinational corporations and smaller, specialised players. Key players such as Hero AG, Raisio PLC, Barilla G.E.R Fratelli S.P.A., and Kellogg’s Company dominate the market, leveraging strong brand recognition, extensive distribution networks, and significant investments in research and development. These companies focus on product innovation, catering to the increasing consumer demand for convenient, nutritious, and allergen-free food options. Smaller players, including niche gluten-free producers, contribute by offering unique, specialised products, often focusing on organic, plant-based, or clean-label offerings to appeal to health-conscious consumers. The market is characterised by high competition, with manufacturers striving to differentiate through taste, texture, and nutritional benefits. Additionally, the rise of e-commerce and direct-to-consumer sales channels has created a dynamic and evolving landscape, pushing companies to adapt and stay competitive through enhanced online visibility and strategic partnerships.
Report Coverage
The research report offers an in-depth analysis based on product type, source, sales channel and geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The gluten-free prepared food market is expected to continue its growth trajectory, reaching USD 10,490.59 million by 2032.
- Increasing awareness of coeliac disease and gluten intolerance will drive demand for gluten-free options.
- Health-conscious consumers without gluten-related disorders will continue to adopt gluten-free diets, expanding the target market.
- Manufacturers will focus on improving the taste and texture of gluten-free products to appeal to a broader audience.
- There will be an increased emphasis on clean-label and organic gluten-free options, responding to growing health trends.
- E-commerce platforms will become even more significant in reaching a global consumer base for gluten-free products.
- Expansion into emerging markets, particularly in Asia Pacific and Latin America, will present new growth opportunities.
- Innovation in gluten-free ingredients, such as plant-based and superfoods, will further diversify product offerings.
- Partnerships between gluten-free brands and health-focused retailers will strengthen market visibility.
- Increased regulatory support for gluten-free labelling and certifications will foster consumer trust and boost market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the gluten-free prepared food market?
What factors are driving the growth of the gluten-free prepared food market?
What are the key segments within the gluten-free prepared food market?
What are some challenges faced by the gluten-free prepared food market?
Who are the major players in the gluten-free prepared food market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Gluten-Free Prepared Food Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Gluten-Free Prepared Food Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 5,882.1 million → 2032: USD 10,490.59 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Gluten-Free Prepared Food Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Gluten-Free Prepared Food Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Gluten-Free Prepared Food Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Gluten-Free Prepared Food Market Drivers
- 3.3 Gluten-Free Prepared Food Market Restraints & Challenges
- 3.4 Gluten-Free Prepared Food Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Gluten-Free Prepared Food Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Gluten-Free Prepared Food Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Gluten-Free Prepared Food category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Gluten-Free Prepared Food Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Gluten-Free Prepared Food Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Gluten-Free Prepared Food market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Gluten-Free Prepared Food Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Gluten-Free Prepared Food Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Gluten-Free Prepared Food Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Gluten-Free Prepared Food (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Gluten-Free Prepared Food Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Gluten-Free Prepared Food Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Gluten-Free Prepared Food Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Gluten-Free Prepared Food Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Gluten-Free Prepared Food Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Gluten-Free Prepared Food Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Gluten-Free Prepared Food Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Gluten-Free Prepared Food Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Gluten-Free Prepared Food Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
