
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hip Replacement Implants Market Size 2024 | USD 3,923.14 million |
| Hip Replacement Implants Market, CAGR | 3.04% |
| Hip Replacement Implants Market Size 2032 | USD 4,971.26 million |
Market Overview
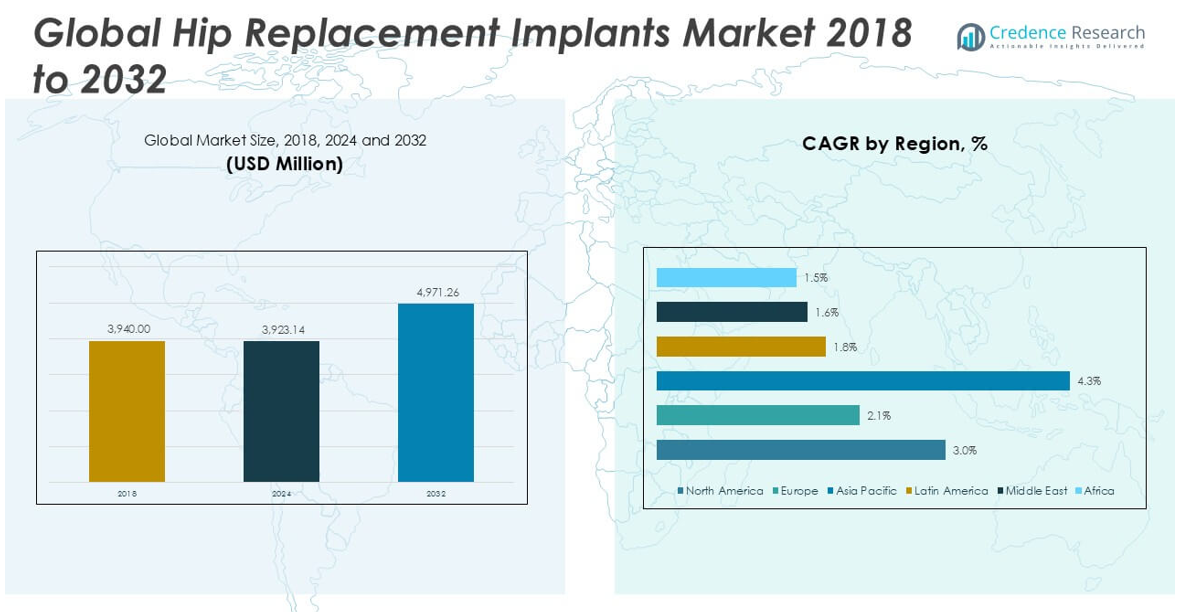
The Hip Replacement Implants market size was valued at USD 3,940.00 million in 2018, reached USD 3,923.14 million in 2024, and is anticipated to reach USD 4,971.26 million by 2032, at a CAGR of 3.04% during the forecast period.
The Hip Replacement Implants market is highly competitive, with key players such as Zimmer Biomet, Johnson & Johnson, Stryker Corporation, Smith & Nephew Plc, MicroPort Scientific Corporation, Exactech, Inc., OMNIlife Science, Inc., B. Braun Melsungen AG, DJO Global, Inc., Aesculap Implant Systems, LLC, and ConMed Corporation actively shaping the industry landscape. These companies focus on strategic partnerships, product innovation, and geographical expansion to strengthen their market positions. North America leads the global market, commanding a significant share of approximately 43.1% in 2024, driven by advanced healthcare infrastructure, high procedure volumes, and favorable reimbursement policies.
Market Insights
- The Hip Replacement Implants market was valued at USD 3,940.00 million in 2018, reached USD 3,923.14 million in 2024, and is projected to reach USD 4,971.26 million by 2032, growing at a CAGR of 3.04% during the forecast period.
- Rising geriatric population, increasing cases of osteoarthritis, and growing preference for minimally invasive surgeries are key drivers fueling market growth.
- The Total Hip segment holds the largest market share of over 50% in 2024, while North America leads regionally with a 43.1% share, followed by Asia Pacific with 24.6%.
- Key players like Zimmer Biomet, Johnson & Johnson, and Stryker Corporation dominate the competitive landscape through product innovation, partnerships, and global expansion strategies.
- High treatment costs, risks of implant failure, and stringent regulatory approvals remain significant restraints, particularly in low- and middle-income countries.
Market Segmentation Analysis:
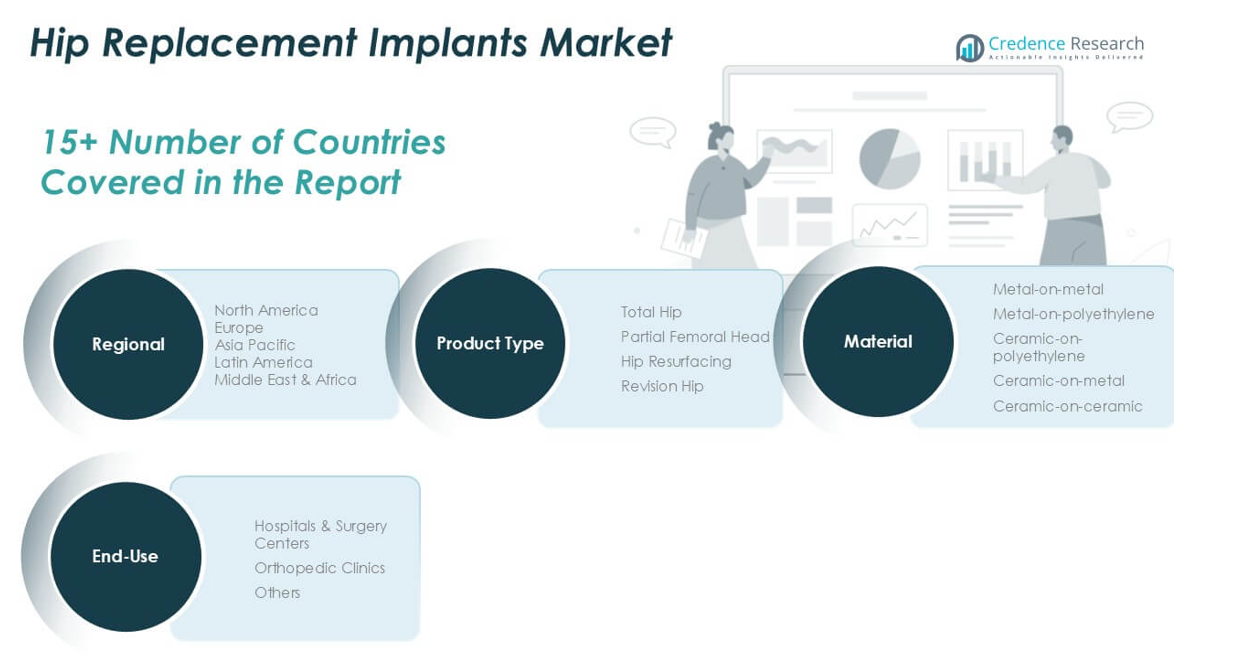
By Product:
The Hip Replacement Implants market is segmented by product into Total Hip, Partial Femoral Head, Hip Resurfacing, and Revision Hip. Among these, the Total Hip segment dominates the market, accounting for the largest share of over 50% in 2024. This dominance is driven by the growing prevalence of osteoarthritis, improved surgical outcomes, and the increasing adoption of minimally invasive procedures. The total hip replacement offers enhanced mobility and pain relief, making it the preferred choice for both patients and healthcare providers. Rising elderly populations and advancements in implant design further support the growth of this segment.
- For instance, Zimmer Biomet’s G7 Acetabular System has achieved more than 150,000 implantations globally since its introduction, demonstrating its reliability and surgeon preference in total hip replacements.
By Material:
Based on material, the market is categorized into Metal-on-metal, Metal-on-polyethylene, Ceramic-on-polyethylene, Ceramic-on-metal, and Ceramic-on-ceramic implants. The Metal-on-polyethylene segment holds the largest market share, exceeding 40% in 2024, due to its affordability, durability, and lower complication rates compared to metal-on-metal options. This material combination provides excellent wear resistance and compatibility with body tissues, which has led to its widespread use in primary hip replacements. Additionally, increasing clinical preference for materials that minimize post-surgical issues and the availability of advanced polyethylene variants further accelerate the adoption of this segment.
- For instance, Stryker’s X3 Advanced Bearing Technology has been clinically proven to reduce wear by 97% compared to conventional polyethylene, significantly enhancing the lifespan of metal-on-polyethylene implants.
By End Use:
In terms of end use, the Hip Replacement Implants market is divided into Hospitals & Surgery Centers, Orthopedic Clinics, and Others. Hospitals & Surgery Centers are the dominant sub-segment, commanding more than 60% of the market share in 2024. This is primarily due to the availability of advanced surgical infrastructure, skilled orthopedic surgeons, and comprehensive post-operative care. The increasing volume of hip replacement procedures in hospital settings, driven by favorable reimbursement policies and the growing elderly population, supports the continued dominance of this segment. Moreover, hospitals offer a higher level of patient trust and surgical safety standards, contributing to sustained growth.
Market Overview
Rising Geriatric Population
The increasing global geriatric population is a major growth driver for the hip replacement implants market. Older adults are more susceptible to degenerative joint diseases, including osteoarthritis, which significantly boosts the demand for hip replacement procedures. As life expectancy rises, the incidence of age-related bone disorders also grows, leading to a higher volume of surgeries. Additionally, elderly patients increasingly seek to maintain mobility and quality of life, prompting the adoption of hip implants. This demographic trend is expected to sustain market expansion over the coming years.
- For instance, Johnson & Johnson’s DePuy Synthes has reported conducting over 1 million hip replacement surgeries globally, particularly catering to the aging population with its broad product portfolio designed for elderly patients.
Advancements in Implant Technology
Continuous advancements in implant materials and surgical techniques are significantly propelling the hip replacement implants market. The development of highly durable, biocompatible materials such as advanced ceramics and improved polyethylene variants has enhanced implant longevity and reduced complication rates. Minimally invasive surgical approaches and robotic-assisted procedures have further improved patient outcomes and recovery times, increasing patient acceptance. These technological innovations not only drive procedural efficiency but also strengthen the trust of both surgeons and patients, thereby supporting consistent market growth.
- For instance, Smith & Nephew’s CORI Surgical System, a handheld robotic-assisted solution, has been successfully used in over 50,000 procedures, significantly improving precision in implant positioning and reducing recovery times.
Increasing Prevalence of Osteoarthritis and Hip Fractures
The rising prevalence of osteoarthritis and the increasing number of hip fractures are contributing significantly to the market’s growth. Sedentary lifestyles, obesity, and sports-related injuries have led to a surge in joint-related issues across all age groups. Osteoarthritis, being the most common condition necessitating hip replacement, is escalating due to these risk factors. Additionally, the growing incidence of accidental falls, especially among the elderly, is driving the need for both primary and revision hip implants, further accelerating market demand globally.
Key Trends & Opportunities
Growing Preference for Outpatient Hip Replacement
A key trend shaping the market is the growing preference for outpatient or same-day discharge hip replacement surgeries. Enhanced surgical techniques and improved pain management protocols have reduced hospital stays, allowing patients to recover in home environments. This shift not only minimizes healthcare costs but also increases the accessibility of hip replacement procedures. Outpatient settings offer quicker turnaround times and cater to the rising demand for convenient, patient-centric care, creating substantial opportunities for healthcare providers and implant manufacturers.
- For instance, Exactech reported that more than 40% of its hip replacement procedures in the United States in 2023 were performed in outpatient settings, demonstrating a significant shift in surgical practice.
Rising Adoption of Customizable and 3D-Printed Implants
The increasing adoption of customizable and 3D-printed hip implants presents a significant opportunity in the market. These implants offer patient-specific solutions that improve fit, comfort, and post-surgical mobility. 3D printing technology allows manufacturers to design implants tailored to individual anatomical needs, enhancing surgical precision and reducing the risk of implant rejection. This trend is gaining traction as it addresses the limitations of traditional implants and supports improved long-term outcomes, especially for complex cases and younger patients seeking high-performance solutions.
- For instance, ConMed Corporation has successfully deployed over 10,000 patient-specific, 3D-printed hip implants globally, enabling improved fit and surgical outcomes for anatomically challenging cases
Key Challenges
High Cost of Hip Replacement Procedures
One of the primary challenges in the hip replacement implants market is the high cost associated with the procedures. The expense of the implant itself, combined with surgical fees, hospital charges, and post-operative care, can make the treatment unaffordable for many patients, especially in low- and middle-income countries. Limited access to advanced healthcare facilities and insufficient insurance coverage in several regions further exacerbate this issue, restricting the market’s growth potential among cost-sensitive patient populations.
Risk of Post-Surgical Complications and Implant Failures
Post-surgical complications, including infections, dislocation, and implant loosening, pose significant challenges in the hip replacement implants market. These risks can lead to revision surgeries, which are typically more complex and costly. Additionally, concerns about long-term implant durability, especially in younger and more active patients, hinder wider acceptance. Despite technological improvements, managing these complications remains critical, as they directly impact patient safety, recovery times, and overall procedural success rates, potentially limiting market growth.
Stringent Regulatory Approvals
The hip replacement implants market faces stringent regulatory approval processes, which can delay product launches and increase development costs. Regulatory bodies require extensive clinical data to ensure the safety and efficacy of implants, resulting in lengthy approval timelines. Compliance with varying international standards further complicates global market entry for manufacturers. These regulatory hurdles can slow innovation and limit the availability of new products, posing a challenge for companies seeking to rapidly expand their portfolios and geographic reach.
Regional Analysis
North America
North America dominates the Hip Replacement Implants market, holding the largest regional share of approximately 43.1% in 2024, with a market size of USD 1,689.28 million. In 2018, the market was valued at USD 1,713.90 million and is projected to reach USD 2,138.15 million by 2032, growing at a CAGR of 3.0%. This growth is driven by the high prevalence of osteoarthritis, advanced healthcare infrastructure, and increasing adoption of minimally invasive surgeries. Strong reimbursement frameworks and the presence of leading orthopedic implant manufacturers further strengthen North America’s market leadership.
Europe
Europe accounts for a significant share in the Hip Replacement Implants market, representing 20.3% of the market in 2024, with a value of USD 795.51 million. The market size was USD 839.22 million in 2018 and is anticipated to reach USD 938.34 million by 2032, expanding at a CAGR of 2.1%. Market growth in Europe is supported by rising elderly populations, increasing awareness about hip replacement options, and advancements in implant technologies. However, slower growth compared to other regions is influenced by stringent regulatory frameworks and the gradual adoption of outpatient surgical procedures.
Asia Pacific
Asia Pacific is the fastest-growing regional market, capturing 24.6% of the global share in 2024, with a market value of USD 964.49 million. It was valued at USD 925.90 million in 2018 and is forecast to reach USD 1,353.68 million by 2032, advancing at a CAGR of 4.3%. This rapid growth is driven by the rising aging population, increasing healthcare investments, and growing awareness of joint replacement procedures. Expanding medical tourism, particularly in countries like India and China, along with improving access to quality orthopedic care, further accelerates the regional market expansion.
Latin America
Latin America holds a moderate position in the Hip Replacement Implants market, accounting for 4.7% of the global share in 2024, with a market size of USD 185.92 million. The market was valued at USD 189.12 million in 2018 and is expected to reach USD 213.12 million by 2032, registering a CAGR of 1.8%. Growth in this region is supported by improving healthcare infrastructure and a gradual rise in the number of hip replacement procedures. However, economic constraints and limited access to advanced surgical technologies continue to challenge market expansion across several countries.
Middle East
The Middle East represents a smaller but stable portion of the Hip Replacement Implants market, with a market share of 3.3% in 2024, valued at USD 128.65 million. In 2018, the market stood at USD 138.69 million and is projected to reach USD 145.69 million by 2032, growing at a CAGR of 1.6%. Market growth is supported by increasing investments in healthcare infrastructure and a steady rise in the elderly population. However, slower adoption of advanced orthopedic procedures and limited regional manufacturing capabilities somewhat restrain more significant growth potential.
Africa
Africa holds the smallest share in the Hip Replacement Implants market, accounting for 3.9% of the global market in 2024, with a size of USD 159.30 million. The market was valued at USD 133.17 million in 2018 and is expected to reach USD 182.29 million by 2032, growing at a CAGR of 1.5%. Market growth in Africa is primarily driven by gradual improvements in healthcare services and increasing awareness of joint replacement solutions. However, challenges such as limited access to specialized surgical care and high treatment costs continue to restrict the region’s overall growth pace.
Market Segmentations:
By Product
- Total Hip
- Partial Femoral Head
- Hip Resurfacing
- Revision Hip
By Material
- Metal-on-metal
- Metal-on-polyethylene
- Ceramic-on-polyethylene
- Ceramic-on-metal
- Ceramic-on-ceramic
By End Use
- Hospitals & Surgery Centers
- Orthopedic Clinics
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Hip Replacement Implants market is highly competitive, with several global and regional players striving to strengthen their market positions through product innovation, strategic partnerships, and geographical expansion. Leading companies such as Zimmer Biomet, Johnson & Johnson, Stryker Corporation, Smith & Nephew Plc, and MicroPort Scientific Corporation dominate the landscape by continuously investing in research and development to introduce advanced, durable, and patient-specific implant solutions. These key players also focus on enhancing their manufacturing capabilities and leveraging minimally invasive technologies to gain a competitive edge. Mergers, acquisitions, and collaborations are common strategies aimed at broadening product portfolios and expanding regional presence. Smaller companies and emerging players are increasingly focusing on niche markets and developing cost-effective implants to address the needs of price-sensitive regions. The competitive intensity is further heightened by the growing demand for 3D-printed and customized implants, which presents both opportunities and challenges for existing market leaders and new entrants alike.
Key Player Analysis
- Zimmer Biomet
- Johnson & Johnson
- Stryker Corporation
- Smith & Nephew Plc
- MicroPort Scientific Corporation
- Exactech, Inc.
- OMNIlife Science, Inc.
- Braun Melsungen AG
- DJO Global, Inc.
- Aesculap Implant Systems, LLC
- ConMed Corporation
Recent Developments
- In February 2024, Hip Innovation Technology, LLC (HIT) unveiled its flagship product, the Reverse Hip Replacement System (Reverse HRS) at the 2024 American Academy of Orthopaedic Surgeons (AAOS) annual meeting in San Francisco
- In February 2024, Zimmer Biomet received the U.S. Food and Drug Administration approval for its Rosa Shoulder System offering. Its application includes robot-assisted surgeries for shoulder, knee, and hip replacement.
- In August 2023, Stryker introduced a nationwide marketing campaign called “Scan. Plan. Mako Can.” This initiative aims to raise awareness among patients about Mako SmartRobotics, an advanced solution for individuals in need of hip joint replacement surgery due to arthritis
- In August 2023, Smith+Nephew introduced the OR3O Dual Mobility System for primary and revision hip arthroplasty in India. The new launch features a unique design where a smaller femoral head securely fits into a larger polyethylene insert. This innovative configuration enhances stability, reduces the risk of dislocation, and provides an improved range of motion compared to traditional hip implant solutions. The Managing Director, South Asia, Smith+Nephew stated, “Smith+Nephew’s OR3O Dual Mobility System is a groundbreaking introduction for India that offers technology not available in other systems”.
- In January 2023, Exactech revealed that the first hip resurfacing surgery was effectively completed employing the novel JointMedica Polymotion hip implant, which is built on a metal-on-polyethylene formulation
Market Concentration & Characteristics
The Hip Replacement Implants Market demonstrates a moderately consolidated structure, with a few key players holding significant market shares. It features strong competition driven by innovation, product quality, and surgical outcomes. Leading companies such as Zimmer Biomet, Johnson & Johnson, and Stryker Corporation maintain dominance through continuous product development and global distribution networks. The market prioritizes technological advancements like minimally invasive procedures and customizable implants to meet evolving patient and surgeon expectations. Pricing pressure remains a characteristic in cost-sensitive regions, pushing manufacturers to offer affordable solutions without compromising quality. Regulatory compliance and clinical performance remain central to product acceptance, shaping market entry and growth opportunities. The market benefits from a consistent demand base supported by an aging population and the rising prevalence of joint disorders. It relies heavily on hospital networks and orthopedic specialists to sustain sales and procedural volumes. Companies with a diverse product range and strong brand reputation maintain competitive advantages. The Hip Replacement Implants Market remains sensitive to post-surgical complication rates and implant longevity, which directly influence purchasing decisions. Strategic collaborations and acquisitions frequently support market consolidation and expansion into emerging markets.
Report Coverage
The research report offers an in-depth analysis based on Product, Material, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Hip Replacement Implants market is expected to witness steady growth driven by the rising elderly population worldwide.
- Increasing adoption of minimally invasive and outpatient hip replacement procedures will continue to support market expansion.
- Technological advancements in implant materials and surgical techniques will improve patient outcomes and implant longevity.
- Customizable and 3D-printed implants are likely to gain significant traction, offering patient-specific solutions.
- Demand for revision hip implants is expected to grow due to the increasing number of primary hip replacement surgeries.
- Emerging markets in Asia Pacific and Latin America will present growth opportunities due to improving healthcare access and infrastructure.
- High treatment costs and limited reimbursement in some regions may continue to restrain market penetration.
- The market is expected to face increasing regulatory scrutiny, requiring more extensive clinical validation for new implants.
- Competition among leading manufacturers will intensify, encouraging continuous product innovation and portfolio diversification.
- The shift towards value-based healthcare and improved post-operative care will play a key role in shaping purchasing decisions and patient preferences.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Geriatric Population
The increasing global elderly population is leading to a higher prevalence of degenerative joint diseases such as osteoarthritis, which significantly boosts the demand for hip replacement implants as older adults seek to maintain mobility and quality of life.
Advancements in Implant Technology
Continuous improvements in implant materials, such as advanced ceramics and polyethylene, along with minimally invasive and robotic-assisted surgical techniques, are enhancing implant longevity and patient outcomes, driving greater adoption of hip replacement procedures.
Increasing Prevalence of Osteoarthritis and Hip Fractures
The growing incidence of osteoarthritis, sports injuries, and accidental falls—especially among the elderly—necessitates both primary and revision hip replacements, fueling market growth globally.
Growing Preference for Outpatient and Minimally Invasive Procedures
Enhanced surgical techniques and improved pain management have enabled more hip replacements to be performed in outpatient settings, reducing hospital stays and costs, and making the procedure more accessible to a broader patient base.
Rising Adoption of Customizable and 3D-Printed Implants
The trend toward patient-specific, 3D-printed hip implants is improving fit, comfort, and surgical outcomes, particularly for complex cases, thereby expanding the market by addressing limitations of traditional implants.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Hip Replacement Implants Market?
What are the key segments within the Hip Replacement Implants Market?
What are some challenges faced by the Hip Replacement Implants Market?
Who are the major players in the Hip Replacement Implants Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Hospitals & Surgery Centers
- 1.2.2 Orthopedic Clinics
- 1.2.3 Others
- 1.3 By Product
- 1.3.1 Total Hip
- 1.3.2 Partial Femoral Head
- 1.3.3 Hip Resurfacing
- 1.3.4 Revision Hip
- 1.4 By Material
- 1.4.1 Metal-on-metal
- 1.4.2 Metal-on-polyethylene
- 1.4.3 Ceramic-on-polyethylene
- 1.4.4 Ceramic-on-metal
- 1.4.5 Ceramic-on-ceramic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,923.14 million → 2032: USD 4,971.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hip Replacement Implants Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hip Replacement Implants Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hip Replacement Implants Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hip Replacement Implants Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hip Replacement Implants Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hip Replacement Implants Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hip Replacement Implants Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hip Replacement Implants Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,923.14 million → 2032: USD 4,971.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hip Replacement Implants Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals & Surgery Centers
- 12.3.7.2 Orthopedic Clinics
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Total Hip
- 12.4.7.2 Partial Femoral Head
- 12.4.7.3 Hip Resurfacing
- 12.4.7.4 Revision Hip
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Metal-on-metal
- 12.5.7.2 Metal-on-polyethylene
- 12.5.7.3 Ceramic-on-polyethylene
- 12.5.7.4 Ceramic-on-metal
- 12.5.7.5 Ceramic-on-ceramic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hip Replacement Implants End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hip Replacement Implants Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hip Replacement Implants Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hip Replacement Implants Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Zimmer Biomet
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Johnson & Johnson
- 18.4 Stryker Corporation
- 18.5 Smith & Nephew Plc
- 18.6 MicroPort Scientific Corporation
- 18.7 Exactech, Inc.
- 18.8 OMNIlife Science, Inc.
- 18.9 B. Braun Melsungen AG
- 18.10 DJO Global, Inc.
- 18.11 ConMed Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

