
Market Overview:
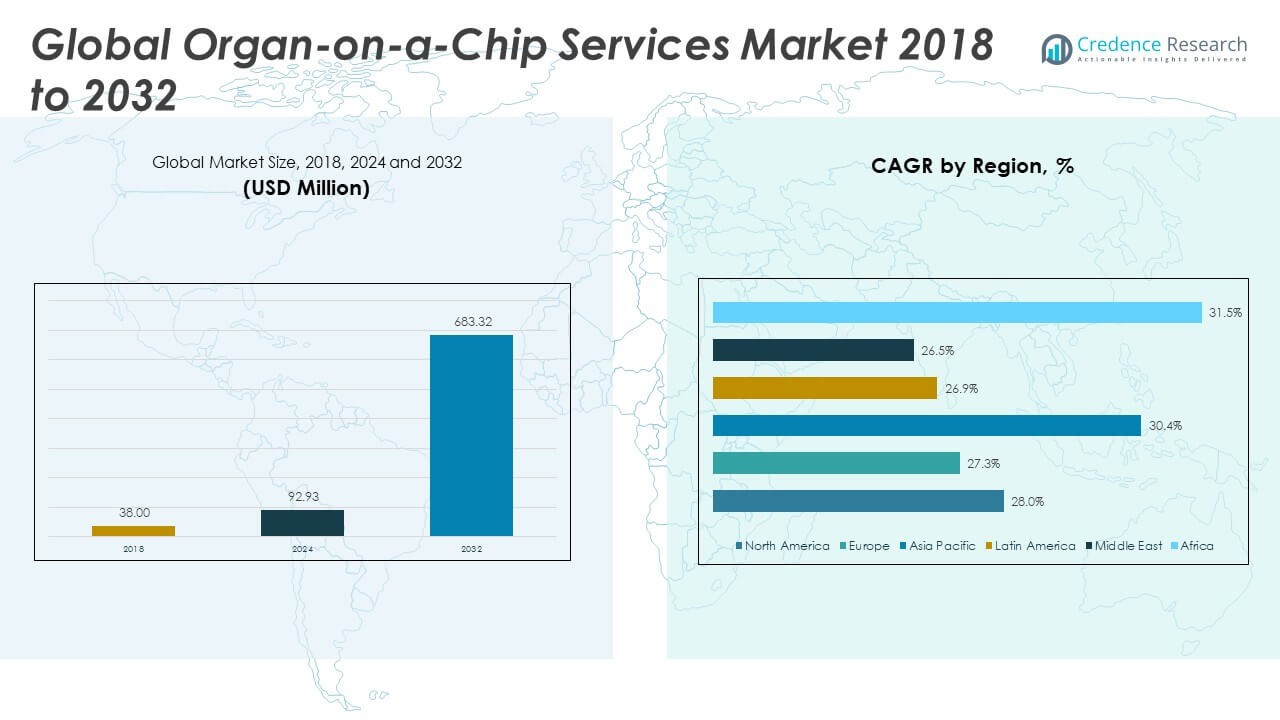
The Global Organ-on-a-Chip Services Market size was valued at USD 38.00 million in 2018 to USD 92.93 million in 2024 and is anticipated to reach USD 683.32 million by 2032, at a CAGR of 28.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Organ-on-a-Chip Services Market Size 2024 | USD 92.93 Million |
| Organ-on-a-Chip Services Market, CAGR | 28.45% |
| Organ-on-a-Chip Services Market Size 2032 | USD 683.32 Million |
This market is gaining momentum due to the increasing demand for alternatives to animal testing, growing investment in drug discovery and personalized medicine, and advancements in microfluidics and 3D cell culture technologies. Pharmaceutical companies, research organizations, and regulatory bodies actively adopt organ-on-a-chip services to enhance preclinical analysis, reduce trial failures, and shorten product development timelines. These services provide a high degree of human relevance, which significantly improves drug efficacy and toxicity prediction.
North America leads the organ-on-a-chip services market, driven by strong research funding, robust biotechnology infrastructure, and early adoption by pharmaceutical giants. Europe follows closely due to supportive regulations and innovation initiatives. Asia Pacific is an emerging region, fueled by increasing government support, expanding pharmaceutical R&D activities, and a growing biotechnology sector in countries like China, India, and Japan. These regional dynamics reflect the market’s broadening global footprint and the rising importance of biologically relevant in vitro models.
Market Insights:
- The Global Organ-on-a-Chip Services Market was valued at USD 38.00 million in 2018, reached USD 92.93 million in 2024, and is projected to hit USD 683.32 million by 2032, growing at a CAGR of 28.45%.
- Rising demand for accurate, human-relevant preclinical testing models fuels the adoption of organ-on-a-chip services across pharmaceutical and biotech industries.
- Growing investment in personalized medicine and precision therapeutics increases the need for organ-specific testing platforms.
- High development costs, technical complexities, and lack of standardization limit widespread adoption and scalability.
- Regulatory uncertainty and absence of global validation protocols pose challenges for industry-wide acceptance and integration.
- North America leads the market due to robust R&D infrastructure and early adoption by pharmaceutical firms, followed by Europe with strong regulatory support.
- Asia Pacific is emerging as a high-growth region driven by increasing R&D investments, expanding biotech sectors, and government-led innovation programs.
Market Drivers:
Rising Demand for Human-Relevant Preclinical Models Accelerates Market Growth:
The Global Organ-on-a-Chip Services Market benefits from rising demand for more accurate and predictive preclinical testing models. Traditional 2D cell cultures and animal models often fail to replicate human physiological responses. Organ-on-a-chip platforms overcome this limitation by mimicking organ-level functions using human cells. Pharmaceutical and biotech companies increasingly adopt these services to enhance drug screening and reduce clinical trial failures. This shift improves R&D productivity and supports early-stage decision-making. Regulatory agencies are also recognizing the limitations of animal testing, encouraging industry-wide adoption. It plays a vital role in reducing drug development costs and timelines. The market grows as demand for translational accuracy intensifies across therapeutic domains.
- For instance, Emulate, Inc. reported in 2024 that over 27 of the top 30 global pharmaceutical companies have adopted its Organ-Chip technology for preclinical drug discovery and toxicology. In a collaboration with the U.S. FDA, Emulate’s Liver-Chip demonstrated an 87% sensitivity and 100% specificity in predicting hepatotoxicity of 27 tested drugs, results published in Nature Communications. This underscores the significant accuracy improvement over traditional animal and 2D cell models and supports regulatory acceptance for drug safety evaluation.
Expanding Investment in Personalized Medicine Fuels Service Adoption:
Personalized medicine drives the need for organ-specific, patient-derived models that offer high biological relevance. The Global Organ-on-a-Chip Services Market gains traction from increasing focus on patient-centric therapies and precision diagnostics. Companies and research institutions use these platforms to simulate disease-specific environments and evaluate targeted responses. It supports better understanding of drug behavior in genetically diverse populations. Government and private sector investments into precision medicine initiatives create a strong demand pipeline. Integration with omics technologies enhances the granularity of data obtained from these systems. The push for individualized treatment strategies fosters demand for scalable, customizable testing models. It positions organ-on-a-chip services as a critical enabler in the personalized medicine ecosystem.
- For instance, MIMETAS partnered with Roche in 2023 to develop patient-derived tumor-on-a-chip models for high-throughput drug testing, enabling biologically relevant tumor microenvironment simulation. In one oncology study, MIMETAS’ OrganoPlate® 3-lane platform supported co-culture of patient cancer cells and stromal cells, improving predictive accuracy of individualized drug response compared to spheroid cultures. The company’s custom services now allow up to 96 parallel chip assays per plate, increasing experimental personalization and scalability aligned with precision medicine.
Growing Prevalence of Chronic Diseases Boosts Need for Organ-Specific Models:
The rising burden of chronic illnesses such as cardiovascular disease, diabetes, and respiratory conditions prompts demand for organ-specific research tools. The Global Organ-on-a-Chip Services Market supports modelling of disease microenvironments that traditional systems cannot replicate. These platforms allow researchers to study disease mechanisms, drug metabolism, and long-term responses. It offers valuable insight into the progression and treatment of complex conditions. Public and private health organizations are investing in organ-on-a-chip platforms to explore more effective therapies. Growing geriatric populations and lifestyle-related disorders drive continuous research. Organ chips serve as predictive tools for early-stage screening and toxicity assessments. Their ability to simulate pathological conditions enhances therapeutic development for chronic diseases.
Pharmaceutical Industry’s Shift Toward Cost-Effective R&D Enhances Demand:
R&D inefficiencies and rising costs compel pharmaceutical firms to seek faster, cost-effective alternatives. The Global Organ-on-a-Chip Services Market supports this shift by offering platforms that deliver high-throughput data with reduced need for animal testing. It minimizes clinical trial attrition and improves early candidate selection. Faster turnaround and predictive outcomes optimize resource allocation across research pipelines. Drug repositioning and combination therapies also benefit from these advanced models. Contract research organizations increasingly integrate organ-on-a-chip into their service portfolios. This reinforces outsourcing trends and strengthens market growth. The pharmaceutical sector’s emphasis on reducing time-to-market continues to expand the role of these services.
Market Trends:
Integration of Artificial Intelligence Enhances Chip-Based Data Analysis:
AI technologies gain prominence in enhancing organ-on-a-chip data interpretation and decision-making processes. The Global Organ-on-a-Chip Services Market increasingly adopts machine learning models to analyze complex datasets from chip simulations. It enables real-time predictive analytics and pattern recognition. AI integration improves throughput, reproducibility, and result accuracy. Companies develop platforms that couple chips with cloud-based software for automated reporting. AI-driven systems identify biomarkers and therapeutic targets with greater precision. These tools support scalable modelling across diverse disease states. The convergence of digital technologies with bioengineering transforms how researchers interact with chip-based data and accelerates drug discovery timelines.
- For instance, CN Bio Innovations in 2024 launched PhysioMimix® CX AI-powered data analysis software, integrating advanced machine learning algorithms to analyze multi-parametric chip datasets from liver and multi-organ systems. This upgrade enables automated cytotoxicity, metabolic, and transcriptomic data interpretation with batch-to-batch reproducibility exceeding 95%. Pharma partners using the AI-enhanced platform have reduced data analysis time by more than 50% and improved detection of subtle pharmacodynamic signatures in preclinical studies.
Development of Multi-Organ and Body-on-a-Chip Systems Gains Momentum:
Organ-on-a-chip technologies evolve toward creating interconnected, multi-organ systems that replicate full-body interactions. The Global Organ-on-a-Chip Services Market witnesses increasing demand for platforms that simulate multi-organ metabolism and systemic drug effects. It supports advanced pharmacokinetics and pharmacodynamics modelling. Researchers use these systems to study complex drug interactions and off-target effects. Multi-organ chips bridge the gap between single-tissue studies and human clinical trials. Integration of immune system modules further enhances translational relevance. Such comprehensive models enable holistic disease simulation and personalized therapy evaluation. The trend expands the application scope and sophistication of organ-on-a-chip services.
- For instance, in 2023, TissUse GmbH deployed its two-organ and four-organ HUMIMIC® platforms to model human ADME (absorption, distribution, metabolism, excretion) profiles. Notably, the four-organ chip system allowed simultaneous perfusion and interconnection of liver, intestine, kidney, and skin tissues, supporting applications such as systemic toxicity testing and drug-drug interaction studies. Internal validation reports from the company demonstrate successful maintenance of cell viability and function across all tissues for up to 28 days under continuous flow, enabling long-term, physiologically relevant compound testing.
Academic and Industrial Collaborations Foster Innovation and Standardization:
Collaborations between universities, start-ups, and pharmaceutical companies shape product innovation and validation. The Global Organ-on-a-Chip Services Market benefits from joint efforts that aim to refine technology and align with regulatory standards. It creates a shared ecosystem for testing, scaling, and commercializing new models. Collaborative research generates high-impact publications and drives investor interest. Standardized protocols improve reproducibility and facilitate global adoption. Academic institutions serve as innovation hubs while industrial partners support manufacturing and distribution. These partnerships streamline translation from lab to market and drive continuous product refinement. The cooperative model strengthens the overall maturity of the industry.
Increasing Regulatory Attention Encourages Adoption of Ethical Alternatives:
Global regulators evaluate organ-on-a-chip systems as viable replacements for animal models. The Global Organ-on-a-Chip Services Market gains traction as authorities push for ethical, human-relevant testing methods. It aligns with long-term goals of reducing animal use in research. Regulatory support creates confidence among pharmaceutical firms to integrate chip services in preclinical workflows. Validation studies and published guidance help establish credibility. Regional bodies in North America and Europe are leading policy shifts. Regulatory frameworks evolve to recognize data generated from chip models during drug submissions. This trend accelerates mainstream acceptance and builds momentum for the service market.
Market Challenges Analysis:
High Development Costs and Technical Complexity Hinder Widespread Adoption:
The development and integration of organ-on-a-chip platforms involve significant costs, especially in early-stage R&D. The Global Organ-on-a-Chip Services Market faces barriers due to specialized fabrication, maintenance, and skilled labor requirements. It limits access for smaller laboratories and start-ups. The complexity of simulating dynamic biological functions across organ systems demands advanced microengineering and biointerface design. Variability in materials and protocols also affects reproducibility. High costs associated with custom chips and tailored assays restrict commercial scalability. Limited plug-and-play compatibility across systems further complicates integration with existing lab infrastructure. These challenges slow broader implementation across the scientific community.
Lack of Standardization and Regulatory Harmonization Delays Global Expansion:
The absence of uniform performance standards and validation criteria limits regulatory acceptance and cross-border adoption. The Global Organ-on-a-Chip Services Market remains fragmented due to varying regional guidelines and technical specifications. It creates inconsistencies in data interpretation and delays clinical translation. Regulatory bodies have yet to fully define protocols for evaluating chip-based data. Without harmonized frameworks, pharmaceutical firms remain cautious in committing to large-scale adoption. Unclear pathways for compliance discourage long-term investment in service models. Standardization efforts are ongoing but remain uneven across geographies. This slows industry-wide confidence in chip-based testing systems.
Market Opportunities:
Emerging Demand from Toxicology and Environmental Testing Drives Expansion:
The Global Organ-on-a-Chip Services Market finds new growth avenues in toxicology and environmental safety testing. It supports high-resolution analysis of chemical exposure and toxicity in human-like conditions. Regulatory agencies and consumer safety bodies seek ethical, accurate alternatives to animal testing. Demand grows for models that detect long-term effects of pollutants and drugs on organ systems. These services offer repeatable and customizable solutions for diverse testing requirements. Expansion into these segments supports the market beyond pharmaceutical applications and creates a resilient growth pathway.
Rising Investments in Asia Pacific Unlocks New Commercial Potential:
Rapid development of the pharmaceutical and biotech sectors in Asia Pacific boosts demand for organ-on-a-chip services. It benefits from increasing R&D expenditure, growing regulatory modernization, and government incentives. Countries like China, India, and South Korea emerge as key contributors. Local start-ups and global players collaborate to establish service hubs and academic tie-ups. It enhances access to cutting-edge tools across developing regions. Growing talent pools and lower operational costs further strengthen regional competitiveness. The market expands with the rise of innovation-driven healthcare infrastructure in Asia.
Market Segmentation Analysis:
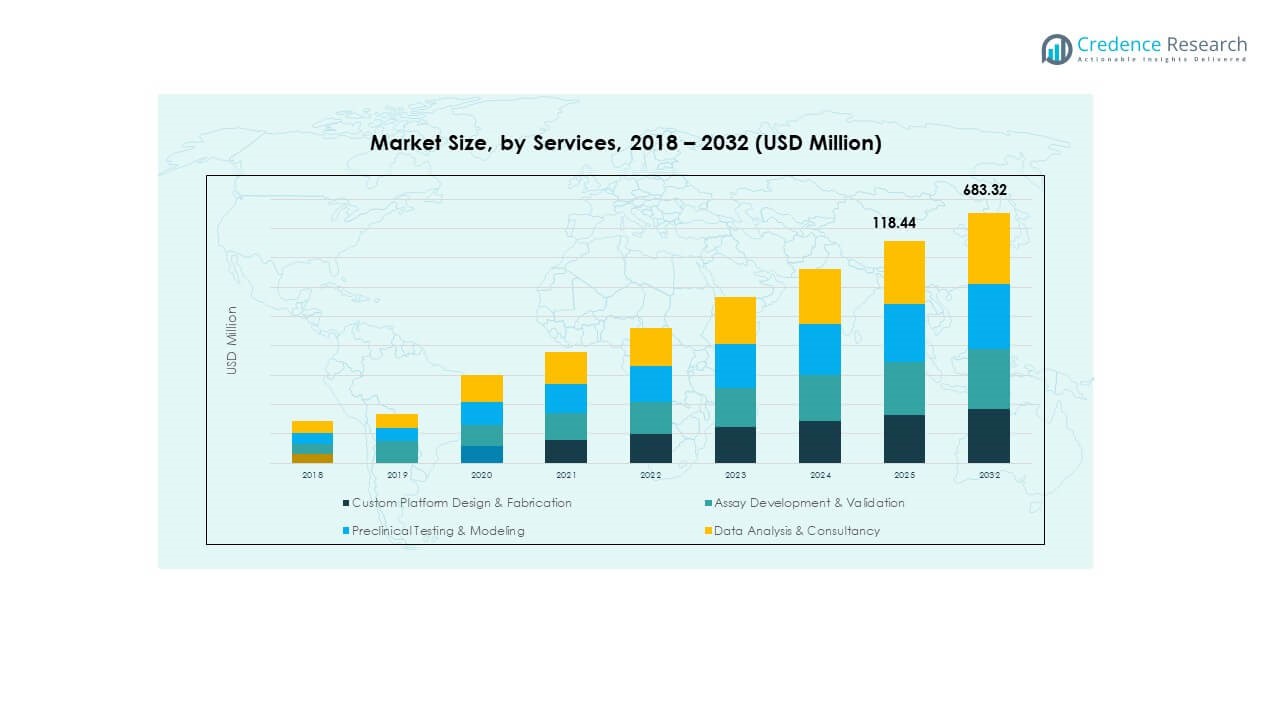
By Services Segment
The Global Organ-on-a-Chip Services Market is segmented into custom platform design & fabrication, assay development & validation, preclinical testing & modeling, and data analysis & consultancy. Preclinical testing & modeling dominates due to its utility in drug efficacy and safety screening. Custom design services see rising demand as researchers seek organ-specific and disease-relevant chips. Assay development supports consistent data generation and reproducibility. Data analysis & consultancy becomes essential as users require expert guidance to interpret complex biological outcomes generated by chip systems.
- For instance, Altis Biosystems, in a 2024 case study, reported support for over 100 client projects annually with its custom platform design and preclinical testing services using its RepliGut® planar intestinal chip model. The company documented that 90% of clients using preclinical modeling services for gut toxicity achieved reproducible results verified across repeat assays, demonstrating the critical role of standardized service delivery for translational research and data consistency.
By Organ Type Segment
Liver-on-a-chip holds the largest share, widely used for evaluating drug metabolism and hepatotoxicity. Lung-, kidney-, and heart-on-a-chip models support respiratory, renal, and cardiovascular research, respectively. Intestine- and brain-on-a-chip systems gain momentum for microbiome and neurodegenerative studies. Skin-on-a-chip assists in dermatological testing, while multi-organ-on-a-chip platforms attract attention for simulating whole-body responses and inter-organ communication, pushing the boundaries of systemic drug development.
- For instance, CN Bio’s Liver-on-a-Chip platform has been validated against primary human hepatocyte cultures to deliver more accurate drug-induced liver injury predictions, with studies reporting 87% true positive rates for hepatotoxicity and correlation coefficients above 0.9 for CYP enzyme activity and albumin production. Emulate’s Lung-Chip has been used in respiratory disease modeling by 15+ major pharma companies, and MIMETAS’ Kidney-on-a-Chip has supported nephrotoxicity screening for over 30 renal drug compounds with a two-fold improvement in detection sensitivity versus conventional cell culture.
By End-user Segment
Pharmaceutical and biotechnology companies lead adoption across the Global Organ-on-a-Chip Services Market due to their focus on faster, cost-efficient R&D. Academic and research institutes use these services for fundamental biological and disease studies. Contract research organizations (CROs) enhance service portfolios by offering organ-on-a-chip platforms to clients. Hospitals and diagnostic centers leverage the technology for personalized diagnostics and therapy testing. The “others” category includes cosmetic and chemical testing companies exploring alternatives to animal models.
By Application Segment
Drug discovery and development remains the primary application, with organ-on-a-chip systems improving candidate screening and reducing attrition rates. Toxicology research grows steadily due to the need for human-relevant safety assessments. Disease modeling enables the study of complex pathologies in controlled environments. Personalized medicine benefits from patient-specific chip models. Regenerative medicine explores cell-based therapies using chip platforms. Cancer research utilizes tumor-on-a-chip models for treatment evaluation. Other applications include microbiome research and inflammation studies.
Segmentation:
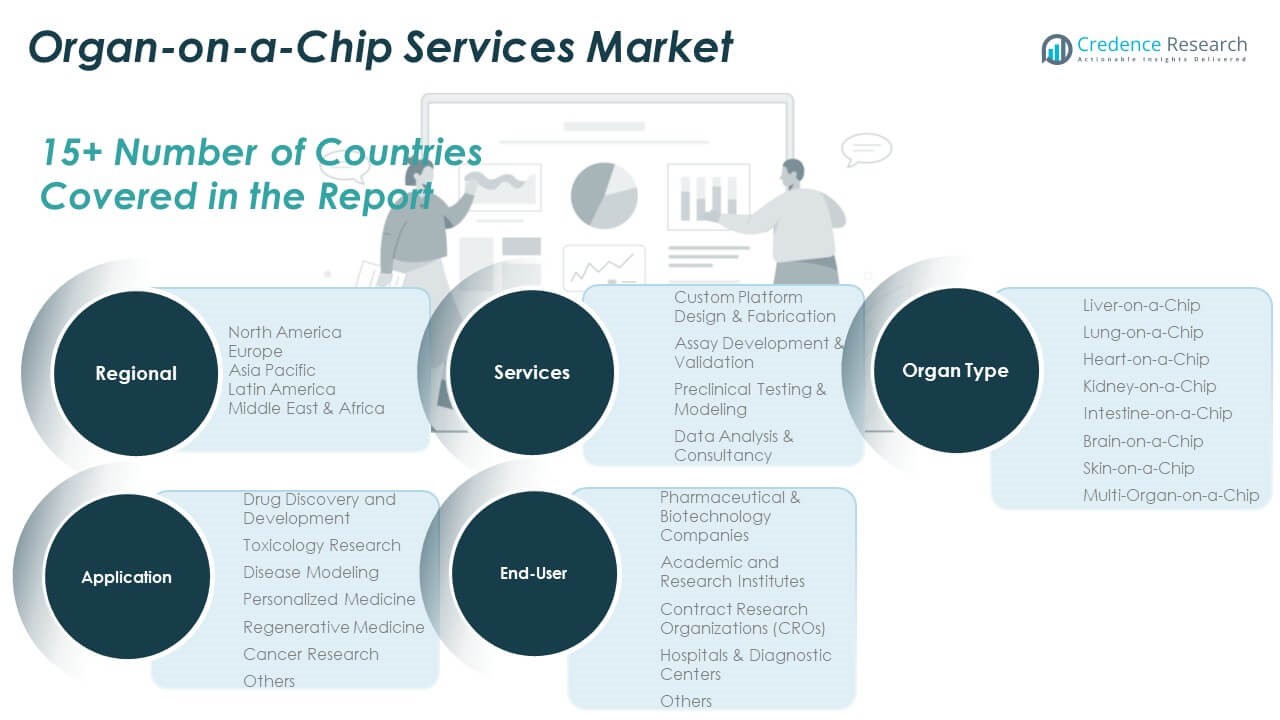
By Services Segment
- Custom Platform Design & Fabrication
- Assay Development & Validation
- Preclinical Testing & Modeling
- Data Analysis & Consultancy
By Organ Type Segment
- Liver-on-a-Chip
- Lung-on-a-Chip
- Heart-on-a-Chip
- Kidney-on-a-Chip
- Intestine-on-a-Chip
- Brain-on-a-Chip
- Skin-on-a-Chip
- Multi-Organ-on-a-Chip
By End-user Segment
- Pharmaceutical & Biotechnology Companies
- Academic and Research Institutes
- Contract Research Organizations (CROs)
- Hospitals & Diagnostic Centers
- Others
By Application Segment
- Drug Discovery and Development
- Toxicology Research
- Disease Modeling
- Personalized Medicine
- Regenerative Medicine
- Cancer Research
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Organ-on-a-Chip Services Market size was valued at USD 18.45 million in 2018 to USD 44.72 million in 2024 and is anticipated to reach USD 321.02 million by 2032, at a CAGR of 28.0% during the forecast period. North America accounts for the largest share of the Global Organ-on-a-Chip Services Market at approximately 47%. It leads due to early adoption of advanced in vitro testing technologies and the presence of key pharmaceutical and biotech players. The United States dominates the region with robust research funding, a strong innovation ecosystem, and regulatory openness to alternative models. Academic institutions and CROs contribute significantly to service demand. Government agencies and private investors continue to fund organ-on-a-chip start-ups. Regulatory bodies such as the FDA recognize the potential of these platforms in preclinical drug evaluation. The region’s highly developed infrastructure supports quick deployment and scalability of chip-based solutions. Industry partnerships further strengthen market expansion.
Europe
The Europe Organ-on-a-Chip Services Market size was valued at USD 7.76 million in 2018 to USD 18.04 million in 2024 and is anticipated to reach USD 123.03 million by 2032, at a CAGR of 27.3% during the forecast period. Europe represents roughly 18% of the Global Organ-on-a-Chip Services Market. It benefits from a well-established regulatory environment that promotes ethical research and the reduction of animal testing. Countries such as Germany, the UK, and France lead adoption through strong academic-industry collaboration. The Horizon Europe program and national initiatives support innovation in life sciences. European companies actively commercialize organ-on-a-chip technologies through partnerships with pharma clients. Research organizations adopt these systems to study chronic diseases, personalized therapy, and toxicology. Regulatory advancements align with global harmonization efforts. Market participants gain traction by aligning services with EU-wide sustainability and healthcare goals.
Asia Pacific
The Asia Pacific Organ-on-a-Chip Services Market size was valued at USD 8.09 million in 2018 to USD 20.80 million in 2024 and is anticipated to reach USD 172.69 million by 2032, at a CAGR of 30.4% during the forecast period. Asia Pacific holds approximately 25% share of the Global Organ-on-a-Chip Services Market. It grows rapidly due to increased pharmaceutical R&D investment and government support in countries like China, Japan, India, and South Korea. The region leverages cost-efficient manufacturing and rising biotech capabilities. Academic institutions collaborate with global firms to bring chip-based platforms to the research forefront. Contract research organizations expand service portfolios with chip-based solutions. Governments provide incentives for advanced healthcare technologies. Asia Pacific’s growing middle class and healthcare demand drive personalized medicine research. The region shows strong potential for scaling organ-on-a-chip testing.
Latin America
The Latin America Organ-on-a-Chip Services Market size was valued at USD 1.82 million in 2018 to USD 4.40 million in 2024 and is anticipated to reach USD 29.29 million by 2032, at a CAGR of 26.9% during the forecast period. Latin America captures around 4% of the Global Organ-on-a-Chip Services Market. Brazil and Mexico lead regional adoption, supported by improving research infrastructure and pharmaceutical investment. Universities and medical centers show growing interest in disease modeling and toxicology services. International collaborations help bridge technical gaps and bring global standards into local markets. Regulatory reforms support the validation of new in vitro models. Market growth remains gradual due to limited funding and awareness. However, increasing demand for efficient drug testing methods creates new opportunities. Regional players begin to explore integration of chip-based services in CRO and academic workflows.
Middle East
The Middle East Organ-on-a-Chip Services Market size was valued at USD 1.22 million in 2018 to USD 2.75 million in 2024 and is anticipated to reach USD 17.84 million by 2032, at a CAGR of 26.5% during the forecast period. The region holds nearly 3% of the Global Organ-on-a-Chip Services Market. Growth is driven by government-led initiatives to modernize healthcare and research sectors. Countries like the UAE, Saudi Arabia, and Israel invest in biotechnology and advanced diagnostics. Hospitals and academic centers adopt chip models for research into genetic disorders and drug safety. Cross-border partnerships enhance access to organ-on-a-chip technologies. Limited manufacturing capabilities restrict faster expansion. Regional focus on reducing dependency on imported research tools supports demand. Medical tourism hubs look to integrate advanced testing platforms. The Middle East continues to invest in high-end life sciences capabilities.
Africa
The Africa Organ-on-a-Chip Services Market size was valued at USD 0.65 million in 2018 to USD 2.22 million in 2024 and is anticipated to reach USD 19.44 million by 2032, at a CAGR of 31.5% during the forecast period. Africa represents about 3% of the Global Organ-on-a-Chip Services Market. South Africa leads regional growth with active research in infectious diseases and toxicology. Institutions begin integrating chip-based services to enhance testing accuracy. International aid and research partnerships play a key role in capacity building. Limited infrastructure and high equipment costs remain key barriers. Nigeria, Egypt, and Kenya show early signs of adoption in academic sectors. Growing health concerns and need for localized research models encourage exploration of organ-on-a-chip platforms. The region gains traction as funding and awareness gradually improve. Africa emerges as a long-term growth opportunity with rising biomedical investment.
Key Player Analysis:
- BioIVT
- Valo Health
- Kirkstall Ltd.
- Altis Biosystems
- Alvéole
- Hesperos, Inc.
- MIMETAS B.V.
- InSphero AG
- TissUse GmbH
- Cherry Biotech
- SynVivo
- Nortis, Inc.
Competitive Analysis:
The Global Organ-on-a-Chip Services Market features a moderately fragmented competitive landscape with a mix of established biotechnology companies and innovative startups. Key players focus on expanding their service portfolios, enhancing platform versatility, and forming strategic collaborations with pharmaceutical companies and academic institutions. Companies such as BioIVT, MIMETAS B.V., Hesperos, InSphero AG, and Altis Biosystems lead market activity through investments in R&D and proprietary chip technologies. It sees strong competition around customized organ models, assay development, and data interpretation capabilities. Players differentiate through technical expertise, scalability, and regulatory alignment. The market continues to attract new entrants with specialized services and niche organ models.
Recent Developments:
- In June 2025, BioIVT launched its Visionaire™ platform, a centralized cloud-based solution designed to integrate clinical, imaging, and multi-omics datasets with advanced AI and bioinformatics. This system streamlines access to biospecimen data and accelerates drug development by improving reproducibility and scalability in AI-driven research workflows. Additionally, on May 26, 2025, BioIVT signed an exclusive commercial agreement with Handok Biotech to advance research innovation in South Korea, strengthening its international partnerships.
- In January 2025, Valo Health expanded its strategic collaboration with Novo Nordisk to include up to 20 novel drug discovery programs focused on obesity, type 2 diabetes, and cardiovascular disease. Leveraging Valo’s Opal Computational Platform™ and rich human data resources, this agreement builds on their original 2023 partnership and brings near-term payments and significant co-development commitments, further enhancing the use of AI-powered platform technologies in the organ-on-a-chip and advanced models sector.
- In May 2025, Hesperos, Inc. won the American College of Cardiology ACC.25 Pitch Competition, showcasing its Human-on-a-Chip® platform that enables multi-organ disease modeling and drug safety assessment. The company’s multi-organ chip data was accepted by the U.S. FDA to support four clinical Phase II drug development programs, with two already advancing to Phase III. Hesperos also announced a partnership with Psilera in June 2025 to accelerate the preclinical pipeline for neurodegenerative therapies using human-relevant chip models, highlighting regulatory advances in animal-free preclinical studies.
- In July 2025, MIMETAS B.V. launched OrganoPlate UniFlow (UF), a commercially available unidirectional, gravity-driven flow organ-on-a-chip platform tailored for drug discovery and high-throughput screening. Earlier in the year, the company published new peer-reviewed research presenting a microfluidic artery-on-a-chip model for vascular disease, reinforcing its leadership in innovation and real-world organ simulation.
- As of June 2025, InSphero AG advanced its Akura™ 3D InSight™ Discovery Platforms, providing scalable and reproducible 3D human tissue and organ-on-a-chip solutions with next-generation formats for drug testing. Their platforms support major pharmaceutical companies with liver, oncology, and cardiac applications and are now automation- and AI-compatible, facilitating the adoption of organ-on-a-chip systems in the mainstream preclinical pipeline
Market Concentration & Characteristics:
The Global Organ-on-a-Chip Services Market shows medium concentration, led by a few dominant players offering highly specialized and customizable services. It is innovation-driven, with companies leveraging proprietary microfluidic designs and organ models to serve pharmaceutical and academic clients. Entry barriers remain high due to the need for technical expertise and infrastructure. Service providers focus on reproducibility, human relevance, and regulatory compatibility to maintain competitive positioning. Continuous innovation, cross-sector collaboration, and geographic expansion define the evolving market structure.
Report Coverage:
The research report offers an in-depth analysis based on services, organ type, end-user, application, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing adoption of organ-on-a-chip platforms will redefine preclinical testing across pharma and biotech pipelines.
- Rising demand for alternatives to animal testing will drive regulatory and commercial acceptance of chip-based services.
- Growth in personalized medicine will push demand for customized, patient-specific organ models.
- Integration of AI and machine learning will enhance data analytics and predictive modeling within chip platforms.
- Academic-industry collaborations will accelerate innovation and expand validation of complex organ systems.
- Multi-organ-on-a-chip technologies will evolve to simulate full-body responses, supporting systemic drug development.
- Expansion in Asia Pacific will boost service accessibility through local manufacturing and regional R&D funding.
- Toxicology and disease modeling applications will gain traction across non-pharmaceutical sectors including cosmetics and environmental science.
- Contract research organizations will increasingly offer organ-on-a-chip services, strengthening market outsourcing trends.
- Continuous improvement in chip fabrication and microfluidics will reduce costs and support wider adoption.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Human-Relevant Preclinical Models
Pharmaceutical and biotech companies are increasingly adopting organ-on-a-chip services to improve the accuracy of preclinical testing, as these platforms better replicate human physiological responses compared to traditional animal models. This shift enhances drug screening, reduces clinical trial failures, and supports regulatory acceptance.
Growth in Personalized Medicine and Precision Therapeutics
The demand for patient-specific and organ-specific testing platforms is rising as personalized medicine becomes a central focus in healthcare. Organ-on-a-chip services enable the simulation of disease-specific environments and individualized drug response, supporting the development of targeted therapies.
Expansion of Pharmaceutical R&D and Outsourcing
Pharmaceutical firms are seeking cost-effective, high-throughput alternatives to traditional R&D methods, driving the integration of organ-on-a-chip services into their pipelines. Contract research organizations are also expanding their offerings to include these services, reinforcing outsourcing trends and accelerating market growth.
Regulatory Push for Alternatives to Animal Testing
Global regulatory agencies are encouraging the adoption of ethical, human-relevant testing methods, which is accelerating the acceptance and integration of organ-on-a-chip services in preclinical workflows. This regulatory support is fostering confidence among industry stakeholders and driving broader market adoption.
Technological Advancements in Microfluidics and AI Integration
Continuous innovation in microfluidics, 3D cell culture, and artificial intelligence is enhancing the functionality, scalability, and data analysis capabilities of organ-on-a-chip platforms. These advancements are making the technology more accessible and effective for a wider range of applications, further fueling market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Organ-on-a-Chip Services Market?
What factors are driving the growth of the Global Organ-on-a-Chip Services Market?
What are the key segments within the Global Organ-on-a-Chip Services Market?
What are some challenges faced by the Global Organ-on-a-Chip Services Market?
Who are the major players in the Global Organ-on-a-Chip Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user Segment
- 1.2.1 Pharmaceutical & Biotechnology Companies
- 1.2.2 Academic and Research Institutes
- 1.2.3 Contract Research Organizations (CROs)
- 1.2.4 Hospitals & Diagnostic Centers
- 1.2.5 Others
- 1.3 By Services Segment
- 1.3.1 Custom Platform Design & Fabrication
- 1.3.2 Assay Development & Validation
- 1.3.3 Preclinical Testing & Modeling
- 1.3.4 Data Analysis & Consultancy
- 1.4 By Organ Type Segment
- 1.4.1 Liver-on-a-Chip
- 1.4.2 Lung-on-a-Chip
- 1.4.3 Heart-on-a-Chip
- 1.4.4 Kidney-on-a-Chip
- 1.4.5 Intestine-on-a-Chip
- 1.4.6 Brain-on-a-Chip
- 1.4.7 Skin-on-a-Chip
- 1.4.8 Multi-Organ-on-a-Chip
- 1.5 By Application Segment
- 1.5.1 Drug Discovery and Development
- 1.5.2 Toxicology Research
- 1.5.3 Disease Modeling
- 1.5.4 Personalized Medicine
- 1.5.5 Regenerative Medicine
- 1.5.6 Cancer Research
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 38.00 million → 2032: USD 683.32 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Organ-on-a-Chip Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Organ-on-a-Chip Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Organ-on-a-Chip Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Organ-on-a-Chip Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Organ-on-a-Chip Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Organ-on-a-Chip Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Organ-on-a-Chip Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Organ-on-a-Chip Services Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 38.00 million → 2032: USD 683.32 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Organ-on-a-Chip Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user Segment - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Base-Year Market Share, 2018
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Pharmaceutical & Biotechnology Companies
- 12.3.6.2 Academic and Research Institutes
- 12.3.6.3 Contract Research Organizations (CROs)
- 12.3.6.4 Hospitals & Diagnostic Centers
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Services Segment - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Base-Year Market Share, 2018
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Custom Platform Design & Fabrication
- 12.4.6.2 Assay Development & Validation
- 12.4.6.3 Preclinical Testing & Modeling
- 12.4.6.4 Data Analysis & Consultancy
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Organ Type Segment - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Base-Year Market Share, 2018
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Liver-on-a-Chip
- 12.5.6.2 Lung-on-a-Chip
- 12.5.6.3 Heart-on-a-Chip
- 12.5.6.4 Kidney-on-a-Chip
- 12.5.6.5 Intestine-on-a-Chip
- 12.5.6.6 Brain-on-a-Chip
- 12.5.6.7 Skin-on-a-Chip
- 12.5.6.8 Multi-Organ-on-a-Chip
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Application Segment - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Base-Year Market Share, 2018
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Drug Discovery and Development
- 12.6.6.2 Toxicology Research
- 12.6.6.3 Disease Modeling
- 12.6.6.4 Personalized Medicine
- 12.6.6.5 Regenerative Medicine
- 12.6.6.6 Cancer Research
- 12.6.6.7 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Organ-on-a-Chip Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Organ-on-a-Chip Services Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Organ-on-a-Chip Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2018-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Organ-on-a-Chip Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BioIVT
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Valo Health
- 18.4 Kirkstall Ltd.
- 18.5 Altis Biosystems
- 18.6 Hesperos, Inc.
- 18.7 MIMETAS B.V.
- 18.8 InSphero AG
- 18.9 TissUse GmbH
- 18.10 Cherry Biotech
- 18.11 Nortis, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

